Once you have accumulated real money, you might expect your bank to start treating you differently. If you have $100,000, $250,000 or $500,000 spread across an RRSP, a TFSA and a taxable account, surely handing all of it to one institution must buy something. I wanted to know what.
I do not mean private banking, and I do not mean someone with a family office. I mean the much larger group of Canadians who have built a few hundred thousand dollars of investments, own a house with a mortgage or a HELOC, carry a premium credit card, and keep financial accounts scattered across several institutions because that is how they accumulated. For that household, the question is practical: does giving one bank more of my financial life actually pay?
The answer turned out to be more inconsistent than I expected. Some banks barely care how much you hold. Some will waive roughly $30 a month if you leave $6,000 sitting in chequing. One counts the investments you hold at its own discount brokerage as a relationship, and one explicitly refuses to count its brokerage. And a company that is not a bank at all, Wealthsimple, increasingly behaves more like a genuine wealth-tier ecosystem than the traditional banks do.
This article is built on a research dossier I assembled from bank fee schedules, product terms, brokerage pricing pages and deposit-insurance documents as they stood on October 6, 2026. Where something could only be confirmed from secondary sources, I say so, and I have left expiring welcome bonuses out entirely, because they say nothing about what a relationship is worth over time.
“Premium” Means Four Different Things
The first thing I learned is that Canadian banks use the word premium for several unrelated products, and the marketing blurs them together. A $30-a-month premium chequing account is a bundle of conveniences: unlimited transactions, free ATM withdrawals, a credit-card fee rebate. A relationship program changes what you pay according to what you hold. An advisor program, such as CIBC Imperial Service, gives you a person. Private banking, often marketed to households around seven-figure investable wealth, is a different service altogether. Most of what is sold as premium banking sits in the first category, and only a few banks have built anything in the second.
The table below sorts the main programs by that distinction. The column that matters most is the fifth: whether the bank reduces its price because of how much wealth you hold, and whether your self-directed investments count toward that.
| Institution | Program | Monthly fee | Basic waiver | Asset-based threshold | Do self-directed investments count? | Most important benefit |
|---|---|---|---|---|---|---|
| RBC | VIP Banking and Value Program | $30 | None; no balance waives it | None; a count of product categories, fee as low as $17.05 | Yes: an RBC Direct Investing balance above $0 counts as a product | Value Program fee reduction; card rebate up to $120 |
| TD | All-Inclusive Banking Plan | $30.95 | $6,000 daily balance | None found | Not applicable | Card rebate up to $139, no TD ATM fees, small safety deposit box |
| BMO | Premium Plan | $30.95 | $6,000 daily balance | None found | No | No-fee Global Money Transfers, card rebate up to $150 |
| Scotiabank | Ultimate Package | $30.95 | $6,000 daily balance | $100,000 Total Relationship Balance | No: Scotia iTRADE is excluded | Card rebate up to $150, global ABM and transfer perks |
| CIBC | Smart Account tiers | $16.95 at Tier 1 | $4,000 | $40,000 (Tier 2) and $100,000 (Tier 3) | Yes: Investor’s Edge counts | Fee $0 and card rebate up to $139 at Tier 3 |
| National Bank | The Total | $28.95 | $6,000 daily balance | None found | Not applicable | Package convenience; the brokerage is the draw |
| Wealthsimple | Core, Premium, Generation | $0 | None | $100,000 and $500,000 | Its own investments are the tier | Credit and margin pricing, chequing rate, USD account |
The underlying terms come from the current RBC VIP Banking and Value Program, TD All-Inclusive Banking Plan, BMO Premium Plan, Scotiabank Ultimate Package, CIBC tiered banking, National Bank’s Total package and Wealthsimple’s pricing.
Two Different Costs, and Why Mixing Them Up Misleads
The most useful analytical distinction in the research is between two kinds of cost that people routinely lump together. The first I call idle-capital cost. TD, BMO, Scotiabank and National Bank will each waive their roughly $30 monthly fee if you keep about $6,000 in the account every day of the month. That $6,000 earns little or nothing. It has a real, measurable opportunity cost, because you could have held it in a savings account or a GIC.
The second is asset-location cost. CIBC and Scotiabank do not ask you to idle cash; they ask you to hold qualifying assets with them. If I already own $100,000 of an all-in-one ETF such as XEQT, or of Berkshire or Brookfield, at another brokerage, and I transfer those securities in kind to CIBC Investor’s Edge, I have not spent $100,000, converted it to cash or left it idle. I own exactly the same investments. I have changed the custodian. The relevant costs are then trading commissions, currency conversion, the quality of the platform, any transfer fee charged by the broker I am leaving, concentration of risk in one institution, and the friction of leaving later. Those can be large or negligible depending on the person, but they are a different species of cost from $6,000 earning nothing, and an honest comparison keeps them apart.
Is Keeping $6,000 in Chequing Actually Stupid?
Surprisingly, not necessarily. A $30.95 monthly fee is $371.40 a year. Divide that by $6,000 and you get about 6.19%. That is the pre-tax return the cash would have to earn elsewhere before paying the fee becomes the cheaper option. Below that, parking the $6,000 is the better deal. At a 3% yield you forgo $180 a year; at 4%, $240; at 4.5%, $270; at 5%, $300; at 6%, $360. Every one of those is below the fee. Today’s liquid high-interest savings accounts pay somewhere around the low-single digits, and a GIC may pay more, which is why I used 2.75% to 4.5% as a working range rather than assuming an equity-like return.
Tax makes the case stronger. If the alternative is interest in a taxable account, the after-tax opportunity cost is lower than the pre-tax figure. At an illustrative 40% marginal rate, a 4.5% yield costs you $162 after tax rather than $270, and the break-even pre-tax yield rises to roughly 10%. I am not assuming a rate for you; the point is only that the comparison tilts further toward leaving the cash in chequing for a high-income saver. If the alternative sits inside a TFSA there is no tax effect, so the pre-tax numbers apply.
There is one honest caveat. Do not compare this with an expected 7% stock-market return. An expected equity return is uncertain, taxed differently and not a substitute for a cash float you need available. A guaranteed 4% on savings and an uncertain 7% on equities are different bets, and neither is what the waiver is really about. If the $6,000 is money you would keep in chequing anyway, the waiver costs you nothing at all. The arithmetic therefore does not make premium chequing a bargain. It only shows that a $6,000 minimum is less punitive than it looks.
The Traditional Banks, Read for Wealth
I will not give each bank a separate review, because the useful question is the same for all of them: does the program respond to how much you have, to what you hold, or to neither?
RBC is the clearest example of a program that responds to what you hold rather than how much. VIP Banking costs $30 a month and, unusually, cannot be waived by any balance. The way to cut the cost is the Value Program: enrol the account, hold at least two other categories of RBC product, and complete qualifying monthly activity. Qualifying categories include a credit card, a personal investment, a residential mortgage and, notably, an RBC Direct Investing account with a balance above zero. Do that and the fee falls to as low as $17.05, with a card fee rebate of up to $120 on top. The reward arrives quickly and does not improve at $100,000, $250,000 or $500,000. A household with a token balance in Direct Investing and a mortgage can get the same banking fee reduction as one with $500,000 there. It is a useful ecosystem, and RBC ranked highest among the Big Five in J.D. Power’s 2025 overall retail-banking satisfaction study and its 2025 retail-banking advice study, but it is not a wealth ladder.
TD’s All-Inclusive plan is basically a very good premium chequing account. The fee is $30.95, waived if you keep $6,000 in the account at the end of each day, and the waiver arithmetic above works. You get no TD fees at other banks’ ATMs in Canada or abroad, a card fee rebate of up to $139 on an eligible card, and a small safety deposit box. Where TD is genuinely strong is cross-border banking. Its Borderless Plan costs US$4.95 a month, US$1.95 alongside All-Inclusive, or $0 with the required US-dollar balance, and TD has a substantial U.S. banking presence. It is not the only Canadian bank with U.S.-based retail banking—RBC and CIBC also offer genuine U.S. accounts to Canadians—but TD remains a coherent option for a snowbird. Nothing on the All-Inclusive plan page, however, links your mortgage or brokerage balances to a better banking tier. Holding $100,000 or $500,000 at TD changes surprisingly little. TD Direct Investing’sAdvanced Dashboard, which carries real-time streaming data, becomes available by maintaining $500,000 in household assets or meeting the trading threshold; that is a market-data perk, and I would not call it a wealth relationship.
BMO’s Premium Plan is a conventional $30.95 package waived with a $6,000 minimum balance. It carries unlimited transactions, an annual card fee rebate of up to $150, no BMO fee on non-BMO ATM withdrawals worldwide, no-fee Global Money Transfers, a waived monthly overdraft-protection fee, a preferred U.S.-dollar rate, select free cheques and stop payments, a Family Bundle for relatives, and a safety-deposit-box discount of only $12 a year. That is a good premium package, but not a wealth ladder: nothing in it responds to how much you hold. What has changed is the brokerage. Since September 14, 2026, BMO InvestorLine charges $0 commission on online stock and ETF trades, $0 base commission plus $0.90 per contract on options, and has eliminated brokerage administration fees. That makes BMO, in practice, an excellent bank-owned brokerage attached to an ordinary premium account. The brokerage balance earns no banking perk, but it also no longer carries an administration cost.
Scotiabank’s Ultimate Package deserves the closest look, because its $100,000 Total Relationship Balance initially looks like the strongest traditional relationship program. The package costs $30.95 a month, and Scotiabank offers both ways to waive it: $6,000 in the account, or $100,000 across eligible Scotiabank chequing, savings, GICs and mutual funds, including eligible registered accounts. The package also gives you up to a $150 card rebate, no Scotia fee on qualifying non-Scotiabank ABM withdrawals, no Scotiabank fee on international money transfers, a preferred rate on qualifying U.S.-dollar transfers within Scotiabank, and free drafts.
Then comes the catch, and it matters enormously. Scotia iTRADE does not count. A self-directed investor cannot simply move an ETF portfolio from another brokerage to iTRADE and obtain the waiver: $250,000 of ETFs there does not satisfy the $100,000 test, while $250,000 in qualifying Scotiabank GICs, savings or Scotia-managed funds can. For a household whose wealth already sits in GICs and savings, Scotiabank may be excellent. For an ETF investor, qualifying means changing the investment product, not merely the custodian, and that is a much larger economic decision than the one CIBC asks of the same investor.
There is, however, a newly improved iTRADE benefit. Effective September 1, 2026, Ultimate Package holders can receive up to 100 commission-free eligible Scotia iTRADE trades per calendar year. The older 10-trades-in-year-one and 5-each-year-after language still appears on some Scotia pages, but Scotiabank’s current change notice and Ultimate Package legal terms explicitly replace it with up to 100 per year. That makes the brokerage perk much more meaningful, even though the iTRADE balance itself still does not count toward the $100,000 relationship test.
CIBC’s tiered Smart Account is probably the strongest traditional-bank section here, because it is the only Big Five bank whose published tiers explicitly count self-directed investments. Its Smart Account is $16.95 a month at Tier 1, or $0 with $4,000 in the account. At Tier 2, from $40,000 of eligible balances, the fee is $0 on up to three accounts, a card rebate of up to $50 appears, and non-CIBC ATM fees are rebated worldwide. At Tier 3, from $100,000, you keep all of that, the card rebate rises to up to $139 for the primary cardholder plus up to $50 each for up to three authorized users, the overdraft monthly fee is waived, and stop-payment fees are rebated. Eligible balances include chequing and savings, CIBC GICs, CIBC mutual funds, and Investor’s Edge, Imperial Investor Service and Personal Portfolio Services; mortgages and other lending do not count. Balances are averaged monthly, the higher of the prior two months applies, and joint holdings can count toward each accountholder’s relationship balance under the tier rules.
So CIBC may be the best traditional Canadian bank for someone who already has $100,000 or more of self-directed investments and does not mind locating them with CIBC. It is primarily an asset-location decision rather than an idle-cash decision, and for an investor who already likes Investor’s Edge it is economically inexpensive. Keep the number in proportion, though. Tier 3 saves the $203.40 Tier 1 fee or, alternatively, the $110 to $180 a year that $4,000 held idle to waive that fee would forgo at 2.75% to 4.5%; those are alternative baselines, not additive. A card rebate of up to $139 adds value only if you would actually hold that CIBC card and would not receive a comparable rebate elsewhere. With one such card the total is roughly $250 to $350 a year, about 0.25% to 0.35% of $100,000. It is useful. It is not a reason to tolerate a worse investment platform, expensive currency conversion or a materially worse mortgage. CIBC names Investor’s Edge as an eligible tier balance, and Investor’s Edge offers the ordinary registered and non-registered account types an investor would expect, including RRSPs, TFSAs and FHSAs.
National Bank is easiest to treat as two separate stories. The Total is a $28.95-a-month account waived at $6,000 that includes unlimited transactions and an integrated line of credit; it is not especially compelling as a wealth relationship. National Bank Direct Brokerage is different: $0 commission on online Canadian and U.S. stock and ETF trades, with a $100 annual administration fee that is waived when the relevant exemption criteria are met, including at least $20,000 of eligible assets under the same account root. It remains one of the strongest bank-owned brokerage platforms in Canada, though BMO has now largely erased its commission advantage. I would put National Bank in the best-of-breed brokerage category, not in the premium-banking contest.
What If the Best Premium Bank Isn’t a Bank?
Wealthsimple sorts clients into three tiers by total assets with the company: Core from $1, Premium from $100,000 and Generation from $500,000. What makes it interesting for this question is that the tier is not a rebate on a chequing fee. It changes pricing across products that a traditional bank sells separately.
At Premium and Generation, the published changes include the following. The U.S.-dollar account costs $10 a month at Core and is included at Premium and above. Margin and the Portfolio Line of Credit are priced off prime: Core currently pays 4.95%, Premium 4.45% and Generation 3.95%, corresponding to prime plus 0.5%, prime and prime minus 0.5%. Chequing interest is published at 1.25% at Core, 1.75% at Premium and 2.25% at Generation as of October 2026, though rates can change. Outgoing wires cost $15, and Wealthsimple waives its fee on eligible outgoing wires of $10,000 or more for Generation clients. The banking side is also more complete than I first assumed: you can deposit cheques by photo, deposit cash at more than 5,300 Canada Post locations, order bank drafts, hold joint chequing accounts, and receive wires. I could not verify enough about the softer advice and planning benefits to assign them a dollar value, so I leave them out.
The Portfolio Line of Credit is the benefit I would study most carefully. Wealthsimple says you need at least $1,000 of eligible assets to start borrowing, and the credit limit can be up to about 35% of the eligible collateral value. Non-registered accounts and TFSAs can be pledged; RRSPs, FHSAs, RESPs and LIRAs cannot. At Generation the rate is prime minus 0.5%, currently about 3.95%; Premium pays about 4.45%; Core 4.95%.
For context, home-equity lines at the large banks are often quoted around prime plus 0.50% in comparison material, although individual pricing varies. On that illustrative basis the Generation rate would be roughly a point lower. But it is not a HELOC, and the comparison flatters it. A HELOC is secured by real property; this line is secured by your investments. The limit is about 35% of eligible collateral, so $500,000 of eligible assets could support at most about $175,000, and a falling market reduces the collateral value. Because only non-registered and TFSA holdings count, an investor whose wealth sits mostly in an RRSP has far less borrowing capacity than the headline portfolio value suggests.
Wealthsimple Mortgage works the way a broker does, not the way a lender does: clients apply through a Wealthsimple mortgage broker, and Wealthsimple says it searches more than 25 lending partners. Earlier in 2026 it also paid cash back after a new mortgage closed, scaled by mortgage size and client tier. That promotion is now closed; Wealthsimple’s own terms set the promotion period from January 15 through August 14, 2026. I mention it as a sign of how Wealthsimple has used its tiers, not as a current benefit, and I have left it out of the present value of Premium or Generation.
The important point is that a promotion like that is not a lower rate. A 0.40-percentage-point difference on a $500,000 mortgage is about $2,000 of first-year interest as a simple scale comparison. For context, Ratehub’s October 5, 2026 snapshot of advertised Big Five five-year fixed rates ranged from 4.59% at Scotiabank to 4.99% at TD and BMO. That is a point-in-time snapshot of advertised rates, not evidence that any particular borrower would be offered one bank’s rate over another’s; what you would actually pay depends on your file, mortgage characteristics and negotiation. A one-time banking or mortgage perk is useful, but it is a footnote beside a good rate.
What Actually Changes at $100,000?
$100,000 is the first threshold in this research where several institutions publish something that responds to wealth, so it is worth comparing them side by side. The table below sets out what you must hold, whether self-directed investments count, and what you receive. The fee and card figures come from each institution’s current published terms; the value estimates are my arithmetic.
| Program | What you must hold | Self-directed investments count? | Banking fee | Card benefit | Investing and credit benefit | Main catch |
|---|---|---|---|---|---|---|
| CIBC Tier 3 | $100,000 average monthly eligible balances at CIBC | Yes, Investor’s Edge counts | $0 on up to 3 accounts | Up to $139 + up to $50 for each of 3 authorized users | Overdraft monthly fee and stop-payment fees waived; no investing or mortgage discount | Moves assets to CIBC; Investor’s Edge charges $6.95 a trade and has tiered FX |
| Scotiabank TRB | $100,000 in qualifying Scotia chequing, savings, GICs and mutual funds | No, iTRADE excluded | $0 | Up to $150 | Up to 100 eligible commission-free iTRADE trades per year; preferred STEP pricing is not quantified here | An ETF investor cannot qualify merely by moving the ETF portfolio to iTRADE |
| Wealthsimple Premium | $100,000 of Wealthsimple assets | Its own investments are the tier | $0 | $240 card fee waived for Premium/Generation under current card terms | $0 commissions; portfolio line at prime; mortgage brokerage | No branches; credit is a portfolio line, not a HELOC |
| RBC Value Program | No asset test; qualifying product categories plus activity | Yes, Direct Investing can count | As low as $17.05 instead of $30 | Up to $120 | No meaningful wealth-tier investing benefit | Same banking reward at a small brokerage balance as at $500,000 |
| Conventional $6,000 waiver | $6,000 idle in chequing | Not applicable | $0 | Up to roughly $139–$150 depending on bank | None | Roughly $165 to $270 a year of forgone yield at 2.75%–4.5% |
Two things stand out. The first is how modest the dollar values are, and how easy they are to overstate. CIBC Tier 3 is worth roughly $250 to $350 a year, as above. Scotiabank’s value depends on your baseline. If the alternative is paying the $30.95 fee, qualifying through relationship assets saves $371.40 a year. If the alternative is keeping the $6,000 minimum, the gain is that the $6,000 can earn elsewhere, about $165 to $270 a year at 2.75% to 4.5%. Those are alternatives, not a sum. The $150 card rebate counts only if you would hold the eligible card and would not receive a comparable rebate under the alternative package. The conventional waiver is cheaper than it looks, but it delivers nothing that grows.
The second is that the benefit depends on where the $100,000 sits and what kind of asset it is. A household with $100,000 in GICs and savings gets a clean win at Scotiabank. A household with $100,000 in self-directed ETFs gets nothing from Scotia’s relationship-balance test and a modest win at CIBC. A household that wants a credit ladder and a $0 investing platform looks at Wealthsimple. The headline number is the same, and the answers are different.
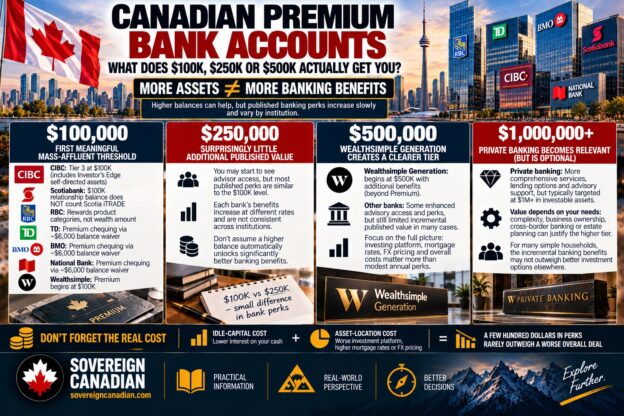
So my conclusion for this tier is that $100,000 is the first meaningful Canadian mass-affluent banking threshold, but what matters more than the number is where it is held and what it consists of.
Does Anything Happen at $250,000?
Not much, and that is itself worth knowing. When I looked for a published fee, rebate or rate tier that applies at $250,000 and not at $100,000, I did not find one at any Big Five bank or at Wealthsimple. CIBC’s Tier 3 starts at $100,000 and stays there; Scotiabank’s test is $100,000; Wealthsimple’s next step is $500,000. A household with a quarter of a million dollars receives essentially the same banking benefits as one with a hundred thousand.
The difference is more likely to be access than pricing. CIBC Imperial Service, which assigns a dedicated advisor, is described by CIBC as most appropriate for households with more than $250,000 in savings and investments. That is an advisory relationship. It is useful if you want an advisor and irrelevant if you do not, and it is not a price break. Many readers will assume that a quarter-million-dollar relationship buys substantially more. It generally does not.
$500,000 Is Where Wealthsimple Gets Interesting
This was the conclusion that changed most when I went back over the research. At $500,000, Wealthsimple’s Generation tier creates an actual additional step. The Portfolio Line of Credit falls to prime minus 0.5%, currently about 3.95%; margin pricing falls with the tier as well; chequing interest is published at 2.25%; USD accounts are included; and eligible outgoing wires of $10,000 or more carry no Wealthsimple fee. None of the Big Five premium-banking programs I looked at creates a comparable published banking tier between $100,000 and $500,000. The traditional banks’ nearest response is TD’s Advanced Dashboard at $500,000 of household Direct Investing assets, which shows how modest that response is.
I want to be careful about how much that is worth, because the most valuable Generation benefits are valuable mostly to someone who borrows. Borrow $100,000 on the portfolio line and the rate difference between Generation and Core is a full point, $1,000 a year. If you are going to borrow against your portfolio, that is real. If you never use margin or a portfolio line, a $500,000 Generation relationship gives you a $0-commission brokerage, free qualifying large wires, the higher chequing rate and other ecosystem benefits, but the incremental economic value is much smaller.
So the honest statement is that $500,000 is where one ecosystem finally publishes a clear additional tier, not where wealth starts to buy a great deal.
What Happens at $1 Million, and the Whole Ladder
At $1 million it is tempting to move straight to private banking. I would resist that, because there are really three separate worlds. Ordinary affluent banking is everything above: the $100,000 and $500,000 programs. Mass-affluent and advisor programs, such as CIBC’s Imperial Service, add a person to talk to. Private banking is a different service, marketed by some institutions around seven-figure investable wealth and often involving separate fees or pricing. It becomes compelling when the household also has complex borrowing, incorporated businesses, trusts, cross-border exposure, estate complications or large foreign assets. A household with $1 million in an RRSP, a TFSA and an ETF portfolio and a simple mortgage does not automatically need any of it. This article is mostly about the first two worlds.
Here is the whole ladder in one place, showing what genuinely changes at each level.
| Assets | What genuinely changes |
|---|---|
| $50,000 | CIBC Tier 2 at $40,000 (fee $0, card rebate up to $50, ATM rebates worldwide) is the clearest asset-based step below $100,000. Elsewhere you generally either use a balance waiver or a product-bundling program. Wealthsimple Core already costs $0 |
| $100,000 | CIBC Tier 3, Scotiabank’s $100,000 relationship-balance waiver and Wealthsimple Premium all start here. The first real inflection |
| $250,000 | Essentially the $100,000 banking benefits, plus access to advisor programs such as CIBC Imperial Service |
| $500,000 | Wealthsimple Generation (portfolio line at prime minus 0.5%, higher chequing rate, free qualifying large wires and other tier benefits). TD’s Advanced Dashboard market-data perk |
| $1,000,000 | The same basic premium-banking benefits; private banking and more complex wealth services become increasingly relevant, but remain optional |
Commissions Are Becoming the Wrong Question
There is one more reason the banking perks look smaller than they first appear. In 2026 the cost of trading stocks and ETFs has collapsed at a few brokers. Wealthsimple, National Bank Direct Brokerage and, since September 14, BMO InvestorLine charge $0 commission on online stock and ETF trades. TD Direct Investing charges $9.99 for standard online stock trades, while CIBC Investor’s Edge charges $6.95 for standard stock trades and also offers selected commission-free ETFs. Once commissions are at or near zero, they stop being the interesting number.
The interesting number is currency conversion. A Canadian buying U.S.-listed securities with Canadian dollars pays a spread on the conversion, and it is rarely shown as a separate commission. At a 1.5% spread, converting $25,000 costs $375. A $9.99 commission is almost irrelevant beside that.
CIBC is unusually useful here because it publishes the schedule. Its current investment-account FX table lists a spread of 1.6% below US$25,000, 0.9% from US$25,000 to US$99,999.99, 0.5% from US$100,000 to US$249,999.99, 0.3% through the next two tiers up to US$999,999.99, and 0.2% at US$1 million and above. Other brokers use different structures, and not all publish a simple flat spread, which is why I would check the live quote before making a large conversion rather than rely on a generic comparison table.
There are two common ways to reduce repeated conversion costs. A U.S.-dollar account lets you keep U.S. dollars rather than converting on every trade; Wealthsimple includes its USD account from Premium upward, while several bank-owned brokerages also support U.S.-dollar sides of eligible accounts. And Norbert’s Gambit uses a dual-listed security such as DLR, journals it to the other currency and sells it. The economics depend on commissions, bid-ask spread, settlement and the size of the conversion, and in a taxable account the process can also create a capital gain or loss.
The point is simple. A $300 banking perk can be erased by a single poor currency decision. Do not choose a bank because it waives a fee and then pay 1.6% to convert your next $25,000. Also keep three FX jobs separate: spending abroad, sending money internationally, and converting inside a brokerage. A specialist such as Wise can be useful for the first two, while brokerage FX is a separate decision.
For the investment side of that decision, I have looked separately at Berkshire Hathaway for Canadian investors and the increasingly complicated choice among Brookfield stocks for Canadian investors.
The Sovereign Part: Access, Insurance and Redundancy
An affluent Canadian should not optimize only for which bank hands over the most free things. The questions that matter more are about access: what happens if one institution freezes an account, whether you can operate in another currency, whether you can move your investments and your mortgage, and whether you have a second place to stand. That is the same optionality principle behind my broader Flag Theory framework for Canadians.
On the international side, TD has a strong integrated cross-border offering, but it is not alone. RBC Bank is a U.S.-based bank designed specifically for Canadians and allows Canadian residents to open U.S. checking accounts without a U.S. address or Social Security number. CIBC Bank USA likewise offers a U.S.-based Smart Account to eligible Canadian CIBC clients with real-time transfers between Canadian and U.S. CIBC accounts. BMO also has U.S. banking capabilities. TD therefore deserves credit for a coherent cross-border stack, not exclusivity.
Scotiabank’s strength is different: its Ultimate Package removes Scotia fees on qualifying international money transfers and non-Scotia ABM withdrawals and offers special pricing on certain foreign-exchange transactions. Wealthsimple has improved quickly too, with globally reimbursed ATM fees, app-based wires, USD accounts and other transfer capabilities. Even so, I would not make any of them do every job. The point of a premium package should not be to avoid comparing the actual FX rate and transfer cost.
Deposit insurance deserves a short, accurate treatment. The Canada Deposit Insurance Corporation protects eligible deposits up to $100,000 per insured category, per member institution, including principal and interest. The categories include deposits in one name, joint deposits, RRSPs, RRIFs, TFSAs, FHSAs, RESPs, RDSPs and trusts, so one institution can provide considerably more than $100,000 of total coverage when assets legitimately fall into different categories. Foreign-currency deposits can be eligible, but foreign currency does not create a separate category.
And the legal member matters more than the brand. CDIC’s current member list identifies Simplii Financial as a trade name under Canadian Imperial Bank of Commerce, so CIBC and Simplii do not create two independent CDIC member-institution limits. Tangerine Bank, by contrast, is separately listed as a CDIC member from the Bank of Nova Scotia. CIBC plus Simplii is one member; Scotiabank plus Tangerine is two.
The Canadian Investor Protection Fund is a different thing and protects eligible client property held by member investment dealers if the dealer becomes insolvent and property is missing. It does not insure investment values against market losses. CIPF generally provides up to $1 million for all general accounts combined, another $1 million for registered retirement accounts combined, and another $1 million for RESPs. A TFSA falls into the general-account group rather than receiving its own separate $1-million limit.
Still, I do not think fear that RBC or TD will fail is the best argument for a second institution. I have looked separately at the economics of owning the banks themselves in Canadian Bank Stocks: Which Bank Gets My Next $1,000?. The Big Five are heavily regulated, and the more plausible household risks are operational: a fraud hold on an account, a compliance review, a technology outage, a lost card in a foreign country, or a mortgage renewal on which you have no leverage. One institution should not be able to interrupt your entire financial life.
Three Ways I Would Structure It
Putting this together, I tested three realistic architectures for a household with about $250,000 of investments, a mortgage and a premium card.
The first is to consolidate at CIBC: Smart Account Tier 3, Investor’s Edge for the investments, a CIBC premium card, and a mortgage or HELOC wherever the pricing is best. It suits someone who already likes CIBC and does not mind relocating investments there. The second is Wealthsimple-centred: Premium or Generation, Wealthsimple investing and banking, its card, the portfolio line where useful and its mortgage brokerage where competitive, with a traditional bank account kept as a branch-access backup and a specialist transfer service where it helps. It suits a digital-first household. The third is best of breed: a traditional bank for branch access, the mortgage and the HELOC; BMO InvestorLine, National Bank or Wealthsimple for investing; a specialist for international transfers where economical; an independently chosen premium travel card; and a second CDIC institution for emergency cash. It creates more logins and more administration, but it also creates optionality and negotiating leverage.
| Consolidate at CIBC | Wealthsimple-centred | Best of breed | |
|---|---|---|---|
| Banking cost | $0 at Tier 3, with a card rebate up to $139 | $0; current card terms waive the $240 annual fee for Premium and Generation | $0 to about $203 a year at the traditional bank, depending on package and waiver |
| Brokerage | $6.95 standard stock trades plus selected commission-free ETFs | $0 stock/ETF commissions, no administration fee | $0 stock/ETF commissions at BMO, National Bank or Wealthsimple |
| Credit | Any mortgage lender; Tier 3 gives overdraft and stop-payment relief | Portfolio line at prime to prime minus 0.5%; mortgage brokerage where competitive; no HELOC | Lowest competitive mortgage quote; property-secured HELOC where appropriate |
| International | CIBC ATM rebates worldwide; tiered brokerage FX; CIBC also offers CIBC Bank USA | ATM reimbursements, wires, USD account at Premium | Compare dedicated cross-border banking and specialist FX/transfer providers |
| Branch access | Full CIBC network | None; keep a bank account if physical access matters | Full network at the chosen traditional bank |
| Redundancy | Low: chequing, brokerage and card concentrated | Moderate: cash and investments concentrated at one non-bank platform, with a bank as backup | Highest |
| Complexity | Lowest | Low | Highest |
None of these dominates. If I already had $100,000 or more at CIBC and wanted its card, the first would be economically inexpensive. If investing at zero cost, a credit ladder and an app-based life mattered more than a branch, the second is a serious alternative. If I wanted to be able to say no to any single institution, I would choose the third as my default, and I would pay for that in complexity. The right answer depends on the household.
What You Actually Get
For most affluent Canadians, I would not consolidate everything simply to qualify for premium banking. The dollar value of most relationship benefits is too small. I would consolidate where the economics are inexpensive: moving investments I already own to CIBC to unlock Tier 3, if I liked Investor’s Edge; using Wealthsimple Premium or Generation if I already wanted its investing and credit ecosystem; keeping $6,000 in a premium chequing account when the alternative is taxable cash earning less than the 6.19% pre-tax break-even. I would not accept a worse mortgage rate, pay materially higher FX, hold expensive investments, give up international capability or eliminate my redundancy to earn $300 or $400 a year of banking perks.
So what does an affluent Canadian actually receive for giving one institution $100,000, $250,000 or $500,000? At $100,000, a few institutions finally notice. CIBC will waive its fee and raise your card rebate if your qualifying assets include investments at its brokerage; Scotiabank will do something similar if your money is in qualifying savings, GICs and funds, while separately giving Ultimate Package clients up to 100 eligible iTRADE trades a year; Wealthsimple begins to price credit and USD accounts in your favour. At $250,000, surprisingly little changes, apart from access to an advisor at some banks. At $500,000, Wealthsimple creates the clearest additional tier, mostly valuable if you borrow. Around seven-figure wealth, private banking and more complex wealth services become options, but they are not automatically useful.
And across all of those levels, the economic value of the perks is generally measured in hundreds, or perhaps low thousands, of dollars. That is small relative to the consequences of a bad mortgage rate, an expensive currency conversion, a poor investment choice, or having every financial account behind a single login that one institution can lock. The reader with real assets should optimize the architecture of the whole financial life, not chase a free chequing account.
Concentrate where concentration pays. Diversify where diversification protects you.