Tag Archives: Investing

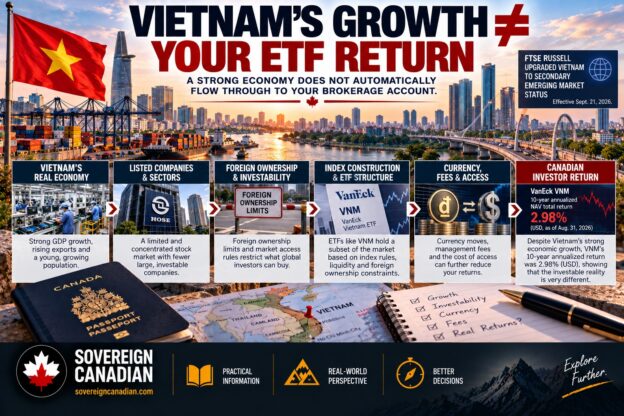
Investing in Vietnam for Canadian investors showing economic growth, foreign ownership limits, ETF structure and investor returns

Investing in Vietnam: Can Canadian Investors Actually Capture Vietnam’s Growth?

Vietnam is the country that gets waved around at every “de-risk from China” panel discussion. Samsung builds phones there. Apple’s suppliers have been moving assembly lines there for years. The population is young. The middle class is expanding. GDP has been growing at rates that would make most finance ministers weep with envy. And in September 2026, FTSE Russell finally did what index watchers had been expecting for years: it moved Vietnam out of frontier-market status and into Secondary Emerging Market status, alongside China, India, Indonesia and the Philippines. FTSE Russell’s Vietnam reclassification

On paper, this is exactly the kind of story that should have made patient foreign investors rich.

Continue reading →
Private REITs and real estate syndicates in Canada comparing illiquid private investments with publicly traded REITs

Private REITs and Real Estate Syndicates in Canada: Are the Higher Yields Worth Giving Up Liquidity?

Say you have $100,000 to invest.

Option one: you buy $100,000 of a Canadian REIT ETF. Tomorrow morning you can check what it is worth. If the bond market has a bad week, you might open your account and see $85,000. You will not like that number, but you will know it, and you can hit sell before lunch if you want to.

Option two: you put the same $100,000 into a private apartment REIT or a five-year real estate syndication. Your statement barely moves. The marketing materials talk about a 7 percent preferred return, a 5 percent cash distribution, institutional-quality buildings and “low historical volatility.” It feels calmer. Nothing is flashing red on a screen.

Continue reading →
Investing in Japan for Canadian investors with Tokyo skyline, weak yen, Japanese equities and corporate reform

Investing in Japan: Is the Weak Yen Creating an Opportunity for Canadian Investors?

I am writing this from Japan. My family and I are here for a few weeks, moving between Osaka, Kyoto and Nara, and the weak yen is impossible to ignore. I was here more than a decade ago, and the difference this time shows up within the first day. Meals that would feel properly expensive back in Ontario come out costing a fraction of that once I convert. Local trains barely register as an expense. Even convenience store snacks, the onigiri and canned coffee that quietly add up on any trip, feel almost free.

I have already looked at Japan from the other direction in Living in Japan as a Canadian: what it costs to live here, how residency works, and where the country fits as an expat destination. This is a different question entirely.

Anyone who has glanced at CAD/JPY over the last couple of years already knows the yen has been weak. But standing in a train station doing currency math in my head, a different question kept nagging at me. If my Canadian dollar buys an unusual amount of Japan at the restaurant, the convenience store and the ticket machine, does it also buy an unusual amount of value on the Tokyo Stock Exchange?

The answer, after spending real time on this, is not necessarily.

Continue reading →
HOOPP pension deep dive showing defined benefit income, early retirement, bridge benefits, CPP, OAS and retirement investments

HOOPP Pension Deep Dive: What Is It Actually Worth, and How Should It Change Your Financial Plan?

Picture two households, both 55, both about to retire.

Household one has $1 million sitting in RRSPs and non-registered accounts. No pension. They look at their net worth statement and feel good about it. A million dollars is a million dollars.

Household two has $600,000 in investments and a HOOPP pension that will pay roughly $45,000 a year for the rest of their life, starting now. Their net worth statement, the conventional kind, says they have $600,000. Six hundred thousand dollars looks a lot smaller than a million.

So which household is actually in the stronger position?

Continue reading →
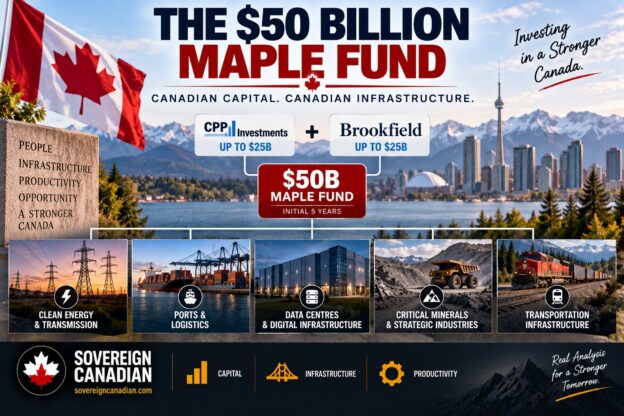
Canada's $50 billion Maple Fund showing CPP Investments and Brookfield funding Canadian infrastructure and strategic industries

Brookfield’s $50 Billion Maple Fund: Can Individual Canadians Invest Alongside It?

One of the announcements that caught my attention coming out of this week’s Canada Investment Summit was the creation of something called the Maple Fund.

The headline number is enormous: $50 billion.

CPP Investments and Brookfield Asset Management have created a new framework to pursue some of the largest infrastructure and strategic investments in Canada. Each organization could put as much as $25 billion into it over the next five years.

Continue reading →
Multi-generational wealth in Canada showing capital and opportunity being passed from one generation to the next

Multi-Generational Wealth in Canada: How Do You Actually Build Wealth That Survives Generations?

CIBC has cited estimates that roughly a trillion CAD will change hands between Canadian generations from 2024 through 2026, the largest transfer of its kind in the country’s history. Statistics Canada reports that the average size of a monetary gift to first-time home buyers rose 73% to $115,000 between 2019 and 2024. Nearly a third of first-time home buyers are now getting help from family to close the deal, up from a fifth in 2019. Whatever else is true about the Canadian economy right now, this is happening, and it is happening at a scale that will shape who owns what in this country for the next generation. It is worth noting, for reasons that will become clear a few sections from now, that some of CIBC’s own wealth commentary on this transfer repeats the claim that seventy percent of family wealth disappears by the second generation. It is a small, useful demonstration of how far that number has travelled, and how little scrutiny it has received along the way.

Continue reading →

Mortgage Prepayment vs Corporate Investing: Should a Business Owner Leave Money in the Company or Pay Down the House?

The previous articles in this series compared mortgage prepayment with a TFSA, RRSP, non-registered investing and an RESP. Corporate investing is a different problem because the money may not start on the personal side of the balance sheet at all.

Suppose I own a profitable Canadian corporation. The company earns more than I currently need to fund its operations or my lifestyle, and I still have a mortgage on my house. I could retain the money inside the corporate structure and use it to grow the operating business, fund an acquisition or build an investment portfolio. Alternatively, I could extract additional money personally, pay whatever tax applies to that extraction, and use the remainder to reduce my mortgage.

Continue reading →
Mortgage prepayment versus non-registered investing in Canada comparing debt reduction with taxable investment returns

Mortgage Prepayment vs Non-Registered Investing: Where Should a Canadian Put Their Extra Money?

The first two articles in this series compared mortgage prepayment with investing inside a TFSA and an RRSP. The TFSA comparison was relatively clean because both sides could be considered largely on an after-tax basis: paying down a non-deductible mortgage avoids an after-tax borrowing cost, while investment growth inside a TFSA is generally tax-free. The RRSP complicated the comparison because the contribution can generate a valuable tax deduction today while withdrawals become taxable income later.

Non-registered investing creates a third version of the same decision, and in some ways it is the hardest one.

Continue reading →
Mortgage prepayment versus RRSP in Canada comparing debt reduction with tax-deferred retirement investing

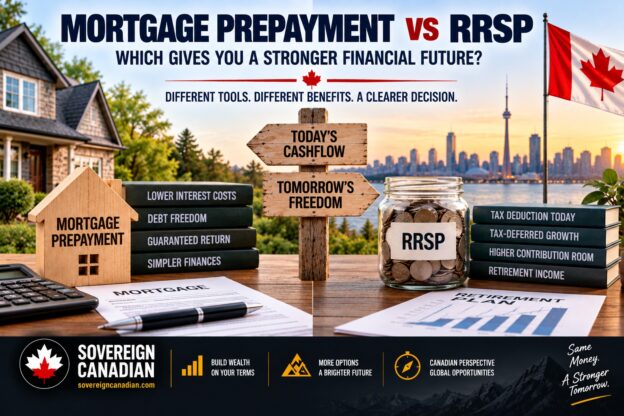
Mortgage Prepayment vs RRSP: Where Should a Canadian Put Their Extra Money?

The mortgage-versus-TFSA decision is relatively clean. If I have $25,000 available, I can use it to reduce a non-deductible mortgage or invest it inside an account where future growth is generally tax-free. The mortgage gives me something economically close to a guaranteed after-tax return equal to the interest I avoid. The TFSA gives me an uncertain investment return, but if that return materializes, I generally keep all of it.

Replace the TFSA with an RRSP and the comparison gets considerably more interesting.

Continue reading →
RRSP versus TFSA in Canada comparing tax deferral, tax-free growth and different life stages

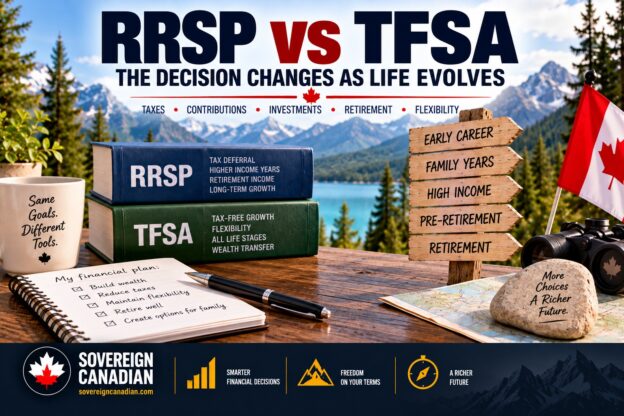
RRSP vs TFSA: The Decision Changes as Your Income Rises

RRSP versus TFSA is one of those Canadian personal-finance questions that seems to have acquired a standard answer: use the RRSP when your income is high and the TFSA when your income is low. That is basically correct, but it is not especially useful until we define what high and low actually mean.

I have thought about this more as my own income has risen. The RRSP contribution I made earlier in my career is fundamentally the same product as the RRSP contribution I make today, but the tax value of the deduction can be dramatically different. That immediately raises another question. If someone earns $80,000 today and reasonably expects to earn $160,000 five years from now, should they use all of their available RRSP room now simply because they have it? What about someone already earning $250,000? What changes if there is a pension waiting in retirement, or if the plan is to retire at 55 and deliberately spend down the RRSP before CPP and OAS arrive?

Continue reading →