Tag Archives: Tax

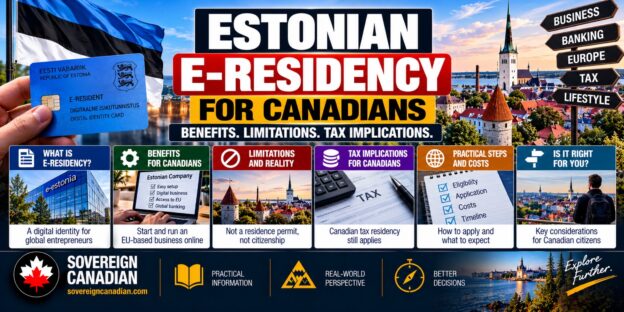
Estonian e-Residency for Canadians featuring Estonia’s digital identity card, Tallinn skyline, business registration, tax implications, residency limitations and application requirements.

Estonian e-Residency: Does It Still Make Sense for Canadians in 2026?

Ten years ago, micro-nations and digital-sovereignty experiments competed for the attention of anyone who liked opting out of the default. Liberland was the romantic version: a claimed sliver of land on the Danube, a flag, a constitution and, so far, no broad recognition from other states. Estonia offered something less theatrical and, frankly, more useful. It is an established, recognized, EU and NATO member state, and it decided to let non-residents plug into its digital government without moving there. That is what Estonian e-Residency for Canadians is really about.

The first thing to get straight is what it is not: a citizenship program, an immigration program or a micro-nation. It is a government-issued digital identity that lets a foreigner sign documents and run an Estonian company online. Liberland asks whether you can create a new sovereign. Estonia asks a much narrower and more practical question: can a state sell you access to its infrastructure? The distinction matters, because the second question has a real answer, and the answer depends heavily on where you pay tax.

This article starts from one question. If I am a Canadian resident operating or considering an international business, why would I establish an Estonian company instead of simply incorporating in Canada? For many people the honest answer is “there is no good reason”. For a narrower group there is a real operational reason, and the tax part is mostly a trap to avoid, not a benefit to chase.

Continue reading →
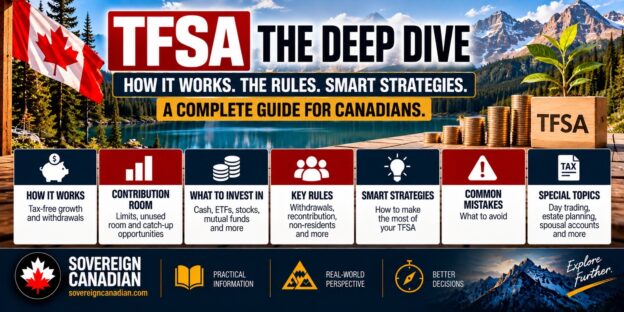
TFSA deep dive for Canadians covering contribution limits, tax-free investment growth, withdrawals, investment options, common mistakes and advanced strategies.

TFSA Deep Dive: The Sovereign Canadian Guide

The Tax-Free Savings Account is the most quietly powerful account most Canadians own, and also the most misunderstood. Its name undersells it. People hear “savings account” and picture a place to park an emergency fund at 2% interest, when in fact it is one of the few tools in the Canadian system capable of sheltering a lifetime of investment growth from tax entirely.

This is a working guide to using it well. We will cover what the account actually is, how contribution room is built and rebuilt, where people get into trouble with the Canada Revenue Agency, and the strategic questions that matter most: TFSA versus RRSP, asset location, early retirement withdrawals, estate planning, and what happens if you leave the country. The goal is not to celebrate the account, but to help you treat it as what it is — a long-term pool of independently controlled, tax-free capital.

Continue reading →
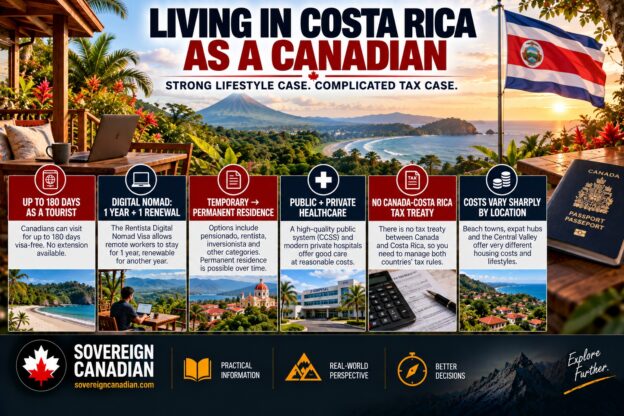
Living in Costa Rica as a Canadian with tropical coastline, Costa Rican flag and Canadian passport highlighting residency, healthcare and tax considerations

Living in Costa Rica as a Canadian: Is Costa Rica Actually a Good Place to Live?

Costa Rica has been sold to Canadians for a generation as a four-part package: tropical weather, cheap living, easy residency and a tax system that supposedly ignores foreign income. In 2026 each of those four parts needs a footnote, and the footnotes are not the same size. The weather is what it always was. The residency routes exist and are easier to understand than most. The “cheap” part now depends on where you live and what you buy. The tax part is the one that breaks down once you read it from a Canadian rather than an American or European point of view.

The reason is structural. Canada and Costa Rica have no income-tax treaty, no social-security agreement and no treaty rule for deciding which country gets to call you a resident. Costa Rica’s territorial tax system is real, but a Canadian who moves there is not entering a tax-free zone. They are entering a gap between two systems that were never negotiated against each other. CPP, OAS and RRIF payments default to a 25% Canadian withholding rate. Leaving Canada triggers its own tax event. The widely repeated claim that a remote worker can sit in Escazú, bill Canadian clients and owe nothing locally is, at best, unresolved. Costa Rica went to the trouble of writing a special exemption for digital nomads, which is a good clue that ordinary residents may not enjoy the same treatment.

Continue reading →
Living in Georgia as a Canadian with Tbilisi skyline, Georgian flag and Canadian passport highlighting visa-free stays, residence and taxes

Living in Georgia as a Canadian: Is Georgia Actually a Good Place to Live?

Picture a 35-year-old Canadian consultant who lands in Tbilisi with a laptop and a one-way ticket. Canadians can stay in Georgia visa-free for a year, so there is no application to file at the airport. The consultant rents a modern apartment in Saburtalo, signs up for fibre internet, learns the Metro and the Bolt app, and keeps working for Canadian and American clients exactly as before. Within a few weeks there is a favourite cafe, a gym, a bank card and a routine. By any ordinary measure, this person has moved to Georgia.

Legally, something quieter has happened. The visa-free stay is not a residence permit. Nothing about it starts the clock that eventually leads to permanent residence. The consultant’s Georgian life can look far more permanent than their Georgian status is, and, separately, nothing in that arrival has told the Canada Revenue Agency that this person stopped being a Canadian tax resident.

Continue reading →
Snowbird versus full relocation for Canadian retirees comparing tax residence, RRSP and RRIF treatment, pension splitting, OAS, healthcare and foreign taxes

Snowbird vs Full Relocation: Should Canadian Retirees Actually Leave Canada?

A CAD 400,000 gap in how Canada taxes a RRIF at death looks like the whole answer, until you ask how much of that RRIF you will actually have left, and where you will genuinely be living when it matters.

Picture two Ontario retirees who started in nearly identical positions. Both retired at 55 with a RRSP worth about CAD 1.5 million. Both are now in their late eighties, widowed, with no spouse left to roll a RRIF over to. One still lives in Ontario. The other genuinely moved away years ago and has been a non-resident of Canada ever since.

If each of them dies this year with a CAD 1.5 million RRIF still sitting there, the Canadian tax difference between them can be roughly CAD 400,000. The resident’s RRIF is generally included in income on the final return, pushing much of a large balance into Canada’s highest marginal tax brackets. For a genuinely non-resident annuitant, the best-supported Canadian treatment is instead a deemed RRIF payment subject to Part XIII withholding, normally at 25 percent.

Continue reading →
TOSI and income splitting in Canada showing family tax planning strategies for business owners, couples and retirees

TOSI and Income Splitting: The Family Tax-Splitting Toolkit

Ask any Canadian business owner what happened to income splitting and you will get the same answer: TOSI killed it. Before 2018, a private corporation could pay dividends to a spouse who did nothing, to adult children away at school, to whoever in the family sat in the lowest tax bracket that year. Then the rules changed, and the general understanding is that this entire category of planning simply stopped working.

That understanding is half right, which is the most dangerous kind of half right. What actually happened is narrower and more interesting than “income splitting is dead.” The Tax on Split Income did shut down one specific manoeuvre: paying private-company income to family members whose only qualification was being related to the person who owned the business. That manoeuvre is genuinely closed. But it was never the whole of income splitting, and treating it as though it were has left a lot of Canadian households ignoring a real, current, and in some cases newly attractive set of tools, while continuing to half-remember advice that stopped being true eight years ago.

Continue reading →
Mortgage prepayment versus non-registered investing in Canada comparing debt reduction with taxable investment returns

Mortgage Prepayment vs Non-Registered Investing: Where Should a Canadian Put Their Extra Money?

The first two articles in this series compared mortgage prepayment with investing inside a TFSA and an RRSP. The TFSA comparison was relatively clean because both sides could be considered largely on an after-tax basis: paying down a non-deductible mortgage avoids an after-tax borrowing cost, while investment growth inside a TFSA is generally tax-free. The RRSP complicated the comparison because the contribution can generate a valuable tax deduction today while withdrawals become taxable income later.

Non-registered investing creates a third version of the same decision, and in some ways it is the hardest one.

Continue reading →

Wills, Executors, and Tax at Death: Getting Your Parent’s Affairs in Order Before It Matters

This is part eleven of the series on moving an elderly parent into your home. By now you have the multigenerational household running, the power of attorney signed, and maybe home care sorted. The one thing most families never get to is the will – because talking about a parent’s death while they are sitting at your kitchen table feels ghoulish. But the will, the executor you will probably become, and the tax at death are exactly what fall on you when the time comes.

Continue reading →

Moving Money to a Low-Income Parent Without Wrecking Their GIS

Once your parent moves in, the money conversation stops being abstract. You are the higher earner. They are a low-income parent living on Old Age Security, maybe a thin CPP cheque, and the Guaranteed Income Supplement that tops it up. You want to help – cover a dental bill, hand them a cushion, put something in their name. And somewhere in the back of your mind is a warning you half-remember: don’t give them too much or you’ll wreck their benefits.

That warning is half right and half backwards. The part almost everyone gets wrong is the part that matters most.

Continue reading →

The Multigenerational Home Renovation Tax Credit: What It Actually Pays You

Somewhere between deciding your parent is moving in and pouring the footings for the new unit, someone – a contractor, a realtor, a well-meaning brother-in-law – will mention the Multigenerational Home Renovation Tax Credit. Usually with the number “$7,500” attached, said with the confidence of a person who read it once in 2023 and never checked again.

I want to walk through what this credit is, what it actually pays in the year you’d claim it, and where it fits in a build decision you were probably making anyway. This is the twelfth deep dive in the elderly parents moving in series, and it pairs directly with the earlier post on whether to build a secondary unit or just buy a bigger house. The tax credit does not change that decision. But if you’re already building, you should at least claim it correctly.

Continue reading →