Tag Archives: Real Estate

Why High-Income Canadians Still Don’t Feel Wealthy

Earning $200,000 a year sounds like financial success. But a high income, substantial net worth, and genuine financial independence are three very different things.

Canada has plenty of households earning what most people would consider excellent incomes. They own attractive homes, drive good vehicles, take family vacations, and contribute to their retirement accounts.

Yet some of these same households feel surprisingly little financial freedom.

How can someone earning $200,000 or $250,000 annually still feel financially constrained?

The answer isn’t necessarily reckless spending. It’s often the difference between earning money, accumulating wealth, and building assets that provide genuine independence.

Continue reading →
Smith Manoeuvre versus Playa del Carmen rental property comparison showing Canadian home equity investing, Mexican real estate, financing, taxes, risks and long-term returns.

Smith Maneuver vs Rental Property: CAD 400,000 Into a Playa del Carmen Condo or Dividend ETFs

The Smith Maneuver vs rental property question usually gets answered with a flip: buy, wait fifteen years, sell, compare. That isn’t how I’d use either one. Both are building vehicles. The first fifteen years are the build, the next twenty-five are when the asset has to pay me to live, and year forty is when somebody sells it and pays the tax. That’s the test here.

The two candidates are ones I’m personally weighing, funded with the same CAD 400,000 of home equity. Door one is a Playa del Carmen condo rented out 95% of the year, with 5% for my own use. Door two is the static version of the Smith Maneuver: one HELOC draw invested in dividend and REIT ETFs, the version I describe in my Smith Maneuver deep dive.

The short answer is that with the loan in place, the portfolio writes the bigger cheque in every year from year 15 to year 40, in all three condo cases I tested. The condo only closes the lifetime gap if it nets about 6.2% a year after costs, and the figures at that level mostly come from people selling condos. Sell both in the same year and the condo actually leaves more net proceeds. The portfolio wins on cash flow, and on being able to sell in stages. So the condo’s case is about owning something, in a second jurisdiction, in a place you want to be. That’s a legitimate case. It’s just a different one from the spreadsheet’s.

Continue reading →
Foreign real estate buyers in Canada guide featuring Canadian homes, foreign buyer restrictions, non-resident property taxes, provincial differences and international real estate ownership rules.

Foreign Real Estate Buyers in Canada: Who Can Still Buy, What It Costs, and How the Rules Follow Us Abroad

I’ve spent a lot of words on the idea of a second property somewhere warmer for the winter months. I’d use it myself, rent it when I’m not there, and get to know the community around it instead of treating it as a line on a spreadsheet. My second real estate investment post ranks that idea against the other places I could put the capital. Every time I bring it up, someone tells me speculation is what’s pushing real estate prices higher.

That’s partly true. Speculation does move markets, and I still don’t recognize my plan as such. Rather than defend myself again, I turned the question around and looked at the group Canadian policy treats as the speculators: foreign real estate buyers in Canada. Can a non-resident still buy here, and where? What does it cost to buy and to hold? When does the ban end? And what does our ban do to Canadians who want to buy abroad? The last answer surprised me most.

Continue reading →
Cottage Airbnb first summer results showing rental revenue, occupancy, operating costs, profitability, challenges and lessons learned

Our First Summer Renting a Cottage on Airbnb: $21,375 in Revenue and What We Learned

Earlier this year, I wrote about our experience after the first month of renting our cottage in Port Franks, Ontario. At that point, we had only a handful of bookings behind us. We were still figuring out pricing, cleaning, minimum stays, guest expectations and whether the entire idea of combining a family cottage with a short-term rental actually made sense.

Now the first summer is over.

We deliberately approached 2026 differently than someone buying a cottage primarily for personal use. Our objective for the first year was to establish the property as a rental, build reviews and generate as much revenue as reasonably possible. We didn’t spend a single night there recreationally as a family during the rental season.

The result was just over $21,000 in rental revenue, 75 nights booked through Airbnb, and a much better understanding of both the potential and limitations of trying to make a cottage help pay for itself.

This is what our first full season actually looked like.

Continue reading →
Private REITs and real estate syndicates in Canada comparing illiquid private investments with publicly traded REITs

Private REITs and Real Estate Syndicates in Canada: Are the Higher Yields Worth Giving Up Liquidity?

Say you have $100,000 to invest.

Option one: you buy $100,000 of a Canadian REIT ETF. Tomorrow morning you can check what it is worth. If the bond market has a bad week, you might open your account and see $85,000. You will not like that number, but you will know it, and you can hit sell before lunch if you want to.

Option two: you put the same $100,000 into a private apartment REIT or a five-year real estate syndication. Your statement barely moves. The marketing materials talk about a 7 percent preferred return, a 5 percent cash distribution, institutional-quality buildings and “low historical volatility.” It feels calmer. Nothing is flashing red on a screen.

Continue reading →
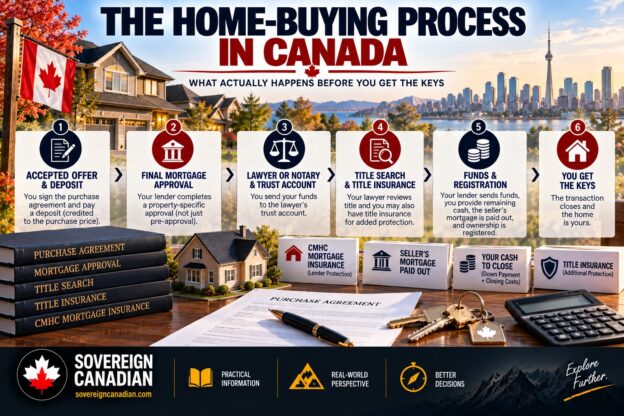
Home-buying process in Canada showing deposit, mortgage approval, lawyer trust account, title insurance, closing funds and registration

The Home-Buying Process in Canada: Title Insurance, Legal Steps, CMHC Mortgage Insurance, and What Actually Happens Before You Get the Keys

You have an accepted offer. You already sent a deposit to somebody. Your bank told you the mortgage is approved. Then your lawyer calls and asks you to send tens of thousands of dollars into something called a trust account, a few days before closing, for reasons nobody explained clearly. Somewhere in the background, your bank is preparing to send hundreds of thousands of dollars to a place you will never see. The seller still has their own mortgage registered against the house. And then, on closing day, the lawyer calls again and says the house has closed, and you can pick up the keys.

What actually happened in between?

Where did the deposit go. Why was pre-approval not the same thing as approval. Who paid off the seller’s bank, and how did your lawyer know that would actually happen. When did the house legally become yours. Why did you pay for title insurance on top of a lawyer who already searched the title. And if you put down less than 20 percent, why did you pay thousands of dollars for an insurance policy that mostly protects your bank and not you.

Continue reading →
Multi-generational wealth in Canada showing capital and opportunity being passed from one generation to the next

Multi-Generational Wealth in Canada: How Do You Actually Build Wealth That Survives Generations?

CIBC has cited estimates that roughly a trillion CAD will change hands between Canadian generations from 2024 through 2026, the largest transfer of its kind in the country’s history. Statistics Canada reports that the average size of a monetary gift to first-time home buyers rose 73% to $115,000 between 2019 and 2024. Nearly a third of first-time home buyers are now getting help from family to close the deal, up from a fifth in 2019. Whatever else is true about the Canadian economy right now, this is happening, and it is happening at a scale that will shape who owns what in this country for the next generation. It is worth noting, for reasons that will become clear a few sections from now, that some of CIBC’s own wealth commentary on this transfer repeats the claim that seventy percent of family wealth disappears by the second generation. It is a small, useful demonstration of how far that number has travelled, and how little scrutiny it has received along the way.

Continue reading →
Living in Cambodia as a Canadian with Angkor Wat, Canadian passport and Cambodian tropical landscape

Living in Cambodia as a Canadian

Cambodia has never been on my radar. I have looked seriously at Thailand, Malaysia, Vietnam, Indonesia, the Philippines, and Singapore. Cambodia never made the list, and I never asked myself why not. That omission is the actual starting point for this piece, because an omission that goes unexamined for years is either a very good instinct or a very lazy one, and I wanted to find out which.

The honest answer, after several weeks of research, is that it is a bit of both. Cambodia has real, documented reasons an affluent Canadian would rationally rank it behind Thailand and Malaysia for almost every serious use case. It also has a genuine, underrated case as a place to watch, and in a couple of narrow respects, a place to use right now. What it does not have is the thing that would justify treating it as a final answer rather than a chapter.

Continue reading →
Mortgages in Canada deep dive covering fixed and variable rates, penalties, HELOCs, porting, refinancing and prepayment privileges

Mortgages in Canada: The Deep Dive

I want to start with the sentence this entire article is built around. The mortgage with the lowest rate is not necessarily the cheapest mortgage.

Most Canadians shop for a mortgage the way they shop for a toaster. They compare a number on a rate sheet, pick the smaller one, and sign. Then, three years later, life happens. They get a job in another city. They have a third kid and need a bigger house. Their marriage ends. They get an inheritance and want to pay down a chunk of principal. They want to buy a rental property. And in that moment, the mortgage they picked because it was 0.10 percent cheaper than the alternative turns out to be a contract that punishes them for doing the ordinary things people do with their lives.

Continue reading →
Mortgage prepayment versus RESP in Canada comparing debt reduction with education savings and CESG grants

Mortgage Prepayment vs RESP: Should You Pay Down the Mortgage or Save for Your Kids?

The previous articles in this series compared mortgage prepayment with investing inside a TFSA, an RRSP, and a non-registered investment account. The RESP creates a different decision because there are really two RESP comparisons hiding inside the same account.

The first is whether I should contribute enough to receive the available Canada Education Savings Grant or put that money against the mortgage instead. The second is what I should do after I have already captured the grant. Should another dollar go into the RESP without receiving any additional CESG, into my TFSA if I still have room, or against the mortgage?

Continue reading →