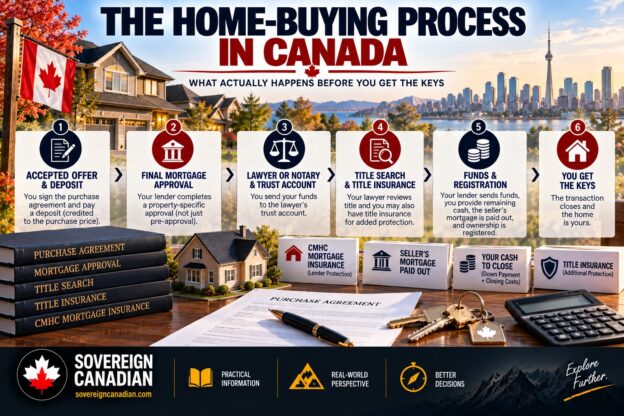
You have an accepted offer. You already sent a deposit to somebody. Your bank told you the mortgage is approved. Then your lawyer calls and asks you to send tens of thousands of dollars into something called a trust account, a few days before closing, for reasons nobody explained clearly. Somewhere in the background, your bank is preparing to send hundreds of thousands of dollars to a place you will never see. The seller still has their own mortgage registered against the house. And then, on closing day, the lawyer calls again and says the house has closed, and you can pick up the keys.
What actually happened in between?
Where did the deposit go. Why was pre-approval not the same thing as approval. Who paid off the seller’s bank, and how did your lawyer know that would actually happen. When did the house legally become yours. Why did you pay for title insurance on top of a lawyer who already searched the title. And if you put down less than 20 percent, why did you pay thousands of dollars for an insurance policy that mostly protects your bank and not you.
This is the part of buying a house that almost nobody explains properly, because most of what gets written about home buying stops at “hire a lawyer and get a mortgage.” Underneath that sentence, several separate transactions are being coordinated to land on the same day: your equity moves, the seller’s old debt gets extinguished, your new debt gets registered, legal ownership changes hands, taxes and utilities get reconciled between two parties who have never met, and title risk gets investigated and often insured. Buying a house is not one transaction. It is several transactions that all have to settle at once, and the whole machine is built around making sure none of them happens without the others.
Your Offer Was Accepted. Here Is What Happens To Your Deposit
The deposit is the first bit of money that moves, and it moves before your mortgage is finalized, before a lawyer has touched the file, and usually before you have thought much about where it actually sits.
In most of the country the deposit goes into the listing brokerage’s real estate trust account, not into the seller’s bank account and not into your lawyer’s trust account, at least not initially. Some deals route the deposit through a lawyer’s trust account instead, particularly where there is no agent involved, but the principle is the same either way: it sits with a regulated party who is not allowed to release it just because the seller wants it. That matters because the deposit is not a separate cost stacked on top of your down payment. It is credited against the purchase price at closing, so the down payment figure you have been told already assumes the deposit is part of it, not an extra amount you owe later.
If the deal closes normally, the deposit simply flows through as part of the funds delivered to the seller. If a condition is properly terminated in accordance with the agreement, the deposit is commonly returned, but that outcome is not automatic. It depends on the specific wording of the agreement, which condition is involved, whether the buyer actually followed the steps the condition required, and applicable provincial law, and the party holding the deposit generally cannot release disputed funds to either side unilaterally if the buyer and seller disagree about who is entitled to it. If you simply change your mind after the conditions are gone, or fail to close for reasons that are your fault, the deposit may be forfeited to the seller, and depending on the contract and the seller’s actual losses, you can be on the hook for more than the deposit itself.
The other thing that trips people up here is the gap between mortgage pre-approval and the mortgage that actually funds your purchase. A pre-approval is primarily an assessment of you: your income, your credit, and roughly how much a lender is willing to lend a person in your position. It does not amount to final approval of the specific house you eventually put an offer on, because the lender has not fully underwritten that property yet. The final approval is property specific, and a lender can decline to fund a pre-approved borrower on a particular property for reasons that have nothing to do with your finances: the appraisal comes in below the purchase price, the property does not meet the lender’s occupancy or access requirements, which comes up constantly with cottages and rural properties, you cannot obtain acceptable property insurance, or your financial picture changed between pre-approval and the offer being accepted. None of this is a technicality. It is the second half of underwriting, and it is the half most buyers do not think about until it goes wrong.
The Lawyer Or Notary Is Not Just Signing Papers
Once the offer is firm, the file moves to a real estate lawyer, or in Quebec to a notary, and this is where the actual settlement machinery starts running.
The lawyer’s job is not to review your offer and then show up on closing day. Between those two points they search the title to confirm who is actually registered as owner and what is registered against the property: existing mortgages, liens, easements, restrictive covenants, judgments against the seller, and anything else that would need to be cleared before you can take clean title. They review whatever the lender has instructed them to do, because the lender is not dealing with you directly at this stage, it is dealing with your lawyer. They arrange title insurance where it is being used. They prepare or review the statement of adjustments, which reconciles who owes what to whom for property taxes and other prepaid items. On closing day they receive your remaining cash and the lender’s mortgage funds into a trust account, confirm every closing condition has actually been satisfied, complete the registration process required in that province, send the appropriate funds to the seller’s lawyer, and only then release the keys.
The trust account is the part people find strangest, but it exists for a specific reason. Your bank is not going to hand you seven hundred thousand dollars and trust you to hand it to a stranger in exchange for a house. The transfer of money and the transfer of legal ownership have to happen together, under the control of a regulated professional subject to trust-account rules and professional obligations, precisely because neither side wants to move first. You do not want to pay before you are protected on title. The seller does not want to hand over title before they are guaranteed the money. The trust account, and the professional obligations that come with it, is how Canadian real estate law solves that problem without requiring buyer and seller to trust each other directly.
Who performs this role differs across the country in ways that are easy to flatten into “you need a lawyer” and leave it there, which understates two genuinely different systems. In Ontario, a lawyer handles the file, and Ontario’s title-insurance regulation specifically prohibits an insurer from issuing a title insurance policy unless it has first received a concurrent certificate of title from a lawyer who is entitled to practise in Ontario and is not employed by the insurer, which is why an independent lawyer stays in the loop even on a file where title insurance is doing a lot of the heavy lifting. In British Columbia, either a lawyer or a BC notary public, a separate regulated profession with its own training path, can carry a standard residential file through to registration at the Land Title and Survey Authority. Quebec is the real outlier: the province is a civil law jurisdiction, residential conveyancing ordinarily runs through a notary rather than a lawyer acting for one side, and an immovable hypothec, which is Quebec’s version of a mortgage, must be granted by notarial act en minute or it is absolutely null under article 2693 of the Civil Code. The notary’s role is structurally different from the common-law model of a lawyer acting for a client.
The detailed province-by-province picture is worth its own section further down, but the short version is that almost everywhere in Canada, a financed purchase runs through a licensed legal professional in practice because lenders and land-registration systems require the legal work necessary to protect and register their security.
What Title Actually Means, And What A Search Cannot Tell You
People use the word title loosely, as if it were a document you could frame and hang on a wall. It is better understood as a legal status, and the specific mechanics of that status depend on provincial land-registration law rather than one uniform national rule. In Ontario, for example, the land registry identifies the registered owner against a specific, legally described parcel identified by a PIN. British Columbia and Nova Scotia use an equivalent parcel identifier called a PID, and other provinces use their own numbering systems, but the underlying idea carries across much of the country: the land-registration system records the legally recognized interests in a specific parcel.
Many Canadian provinces use land-titles systems derived from Torrens principles, where registration carries particularly strong legal significance and the system is designed to provide reliable registered title rather than requiring every purchaser to reconstruct ownership indefinitely into the past. The exact legal effect of registration, and the exceptions to registered title, differ by province. Quebec operates its own civil-law land register, while Prince Edward Island and Newfoundland and Labrador continue to use registry-of-deeds systems where the registry records instruments rather than providing the same form of government-backed registered title.
A clean title search means no undischarged mortgages, liens, or other registered claims turned up beyond what you already agreed to accept, and the registered ownership information is consistent with the transaction. It does not mean nothing could possibly be wrong. A search cannot reliably catch fraud that has not yet come to light, certain unregistered interests, boundary or encroachment problems that only a current survey would reveal, some municipal work orders, or access and right-of-way issues that may not be apparent from a straightforward review of the registered record. That gap between what a clean search confirms and what it cannot rule out is exactly the space that title insurance was built to fill, and it is worth understanding on its own terms before deciding how much weight to put on it.
Why Almost Everyone Ends Up Buying Title Insurance
Title insurance is a one-time premium, paid at closing, that insures against a defined list of ownership and title-related losses. It is not a guarantee that your title is perfect, and it is not a substitute for the lawyer who actually conducts the transaction. Both of those points get lost in how the product is usually sold.
There are two separate policies that can be involved in a typical financed purchase, and conflating them is one of the most common misunderstandings. The lender’s policy protects the lender’s security interest in the property. The owner’s policy protects the homeowner’s interest, subject to the wording, limits, exclusions, and continuation provisions of that specific policy. Standard owner’s policies are generally designed to continue while the insured owner retains an interest in the property, rather than disappearing simply because the mortgage is later refinanced.
That distinction matters. A lender can require protection for its own mortgage without that being the same thing as the homeowner having equivalent personal protection. On a later refinance, the new lender may require a new lender policy for its new charge, while an existing owner’s policy may continue according to its terms. If you are not sure which coverage you actually bought when you purchased the house, it is worth asking your lawyer or checking the policy rather than assuming “title insurance” means the lender and homeowner are protected in exactly the same way.
What the coverage typically includes is fraud and forgery affecting your title, liens or registration defects that a search missed, certain survey and encroachment problems, lack of legal access to the property, and some municipal work order, permit, or zoning defects. What it typically excludes is anything you already knew about before closing, environmental contamination, the physical condition of the house, market value declines, and other matters excluded by the particular policy. Policy wording is not standardized across every insurer and every situation, and it has mattered in practice: in MacDonald v. Chicago Title, an Ontario case, the specific language of the policy became central to whether the homeowners were covered for the problem affecting their property, which is a reminder that “I have title insurance” and “I am covered for this specific problem” are not the same sentence.
This raises a fair question for a country with land titles systems as robust as Canada’s: if the government registry already provides its own protection, backed in some provinces by land-title assurance funds that can compensate for certain losses involving the registration system, why is private title insurance so common?
Ontario’s Land Titles Assurance Fund, for example, exists to compensate eligible claimants for certain losses involving Ontario’s land-registration system. But the fund is a narrower backstop than it can initially sound. Ontario’s statutory scheme has been interpreted in Land Titles Assurance Fund decisions as making the fund a fund of last resort rather than first resort: a claimant generally has to meet specific statutory eligibility requirements and, depending on the circumstances, show that recovering from the person actually responsible for the loss is unavailable or impractical, and claims are subject to a six-year limitation period.
Private title insurance tends to offer a different claims route and covers a broader set of risks than a provincial assurance fund was designed to address, including some off-title problems such as survey defects and work orders, depending on the policy. It can also protect against covered fraud discovered after you already own the property, which a one-time title search obviously cannot predict.
Some lawyers will tell you the government protection plus a competent title search already deals with much of the core title risk and that title insurance is sometimes oversold as a result. Others will tell you the private product’s breadth and claims process make it worthwhile given the relatively modest one-time premium. Both positions have a rational basis. The useful conclusion is not that title insurance replaces the land-registration system, nor that the government system makes title insurance pointless. They solve overlapping but not identical problems.
The fraud question deserves the same balance. In Lawrence v. Wright, also reported as Lawrence v. Maple Trust Company, an imposter fraudulently transferred an Ontario woman’s home and then mortgaged it. The Ontario Court of Appeal’s application of Ontario’s land-titles rules protected the true owner’s interest while leaving the lender that dealt with the fraudster to pursue the remedies available to it.
That is reassuring for homeowners in principle, but it also confirms that title fraud is a real category of loss, just one where the allocation of the loss can depend heavily on the province’s land-registration law and the specific facts. Industry figures describing increases in attempted title and mortgage fraud should also be recognized for what they are when they come from insurers rather than independent government statistics. The more grounded way to think about it is that successful title fraud against an individual homeowner remains unusual, while the financial severity of a serious title problem can be substantial. Those are two different facts that are easy to blur together.
CMHC Insurance Protects Your Lender, Not You
If you make a high-ratio purchase that qualifies for mortgage default insurance, the most persistent misunderstanding is what that insurance is actually for. You pay the premium. The insurer’s protection is primarily for your lender, not for you.
This is not a design flaw. It is the entire point of the product: it lets lenders make high loan-to-value mortgages they would otherwise be unwilling to make by transferring much of the mortgage-default risk to an insurer. It is also why an insured borrower can sometimes receive mortgage pricing as good as, or better than, a borrower with substantially more equity but an uninsured mortgage. The lender’s risk profile is different even though the insured borrower put less money down.
Three companies write this insurance in Canada: CMHC, a federal Crown corporation, and two private insurers, Sagen and Canada Guaranty. Your lender generally decides which insurer receives the application, not you, and while the three broadly line up on the standard premium schedule for an ordinary owner-occupied purchase, their products and eligibility rules are not necessarily identical once you move outside that standard case. Recreational and vacation properties turn out to be one of the clearest examples of why CMHC, Sagen, and Canada Guaranty should not simply be treated as interchangeable.
The current rules changed meaningfully at the end of 2024, and a lot of what still circulates online reflects the old version. The minimum down payment is 5 percent on the first CAD 500,000 of the purchase price and 10 percent on the portion above CAD 500,000 up to the insured-mortgage price limit. Effective December 15, 2024, the federal government increased that price cap from CAD 1 million to CAD 1.5 million.
That creates a genuine cliff in the normal high-ratio insured route. A home priced at CAD 1,499,999 can still qualify for insured financing with roughly CAD 125,000 down, subject to the other underwriting rules. At CAD 1,500,000, the property is outside that standard insured-purchase price limit, so the borrower generally needs at least 20 percent down for a conventional purchase mortgage.
The same December 2024 reforms expanded 30-year insured amortizations to all first-time home buyers and all buyers of newly built homes. For an insured mortgage eligible for an amortization beyond 25 years, CMHC applies an additional 0.20 percentage-point premium surcharge.
CMHC’s current premium schedule runs from 0.60 percent of the loan amount at 65 percent loan to value or below up to 4.00 percent at 95 percent loan to value, with a higher 4.50 percent tier for certain non-traditional down payment sources. This premium can normally be added directly to your mortgage principal, so you are financing it and paying interest on it rather than necessarily paying the premium itself out of pocket.
The part that cannot be added to the mortgage is provincial sales tax charged on the insurance premium. CMHC’s current guidance identifies Ontario, Quebec, and Saskatchewan as the provinces where this applies. That tax has to be paid in cash at closing, on top of everything else, and it is one of the more common surprises for buyers who budgeted for their down payment but never realized there would be a cash tax on the insurance premium.
A concrete example makes this easier to hold in your head than a list of percentages. On a CAD 700,000 home with the legally required minimum down payment under the current tiered rule, 5 percent on the first CAD 500,000 and 10 percent on the remaining CAD 200,000, the down payment works out to CAD 45,000, or just under 6.5 percent of the purchase price, not the flat 5 percent people sometimes assume.
That leaves a base mortgage of CAD 655,000 at a 93.6 percent loan to value, which lands in the 4.00 percent premium tier, adding CAD 26,200 to the mortgage. The financed mortgage becomes CAD 681,200. In Ontario, the 8 percent provincial tax on that CAD 26,200 insurance premium adds another CAD 2,096 that has to be paid in cash at closing.
| Loan to value | CMHC premium |
|---|---|
| Up to 65 percent | 0.60 percent |
| 65.01 to 75 percent | 1.70 percent |
| 75.01 to 80 percent | 2.40 percent |
| 80.01 to 85 percent | 2.80 percent |
| 85.01 to 90 percent | 3.10 percent |
| 90.01 to 95 percent | 4.00 percent |
| 90.01 to 95 percent, non-traditional down payment | 4.50 percent |
There is a fair amount of loose terminology in this space worth untangling briefly, without turning this into a separate mortgage-products discussion.
An insured mortgage is usually what people mean when they talk about “CMHC insurance”: the mortgage is covered by mortgage default insurance, commonly because the borrower has less than 20 percent down, and the borrower pays the insurance premium.
An insurable mortgage is generally a lower loan-to-value mortgage that still satisfies an insurer’s eligibility criteria and can be insured at the lender’s expense rather than through a borrower-paid high-ratio premium. That distinction helps explain why mortgage pricing can differ even between borrowers who both have at least 20 percent equity.
An uninsured or uninsurable mortgage falls outside those insurance structures. Refinances and properties or mortgage structures that do not satisfy insurer criteria can land here.
Rental properties are a partial exception worth flagging rather than folding them into the uninsurable category by default. CMHC separately insures non-owner-occupied residential properties containing two to four units at up to 80 percent loan to value, with a separate small-rental premium schedule. That is a genuine mortgage-insurance program even though it looks nothing like the low-down-payment product available on an owner-occupied purchase.
The deeper mechanics of rate pricing across these categories belong in a mortgage-focused piece rather than this one. I cover that side of the transaction in Mortgages in Canada: The Deep Dive, including penalties, portability, refinancing, HELOCs, collateral charges, and what actually matters beyond the advertised rate.
The House Has To Qualify Too
A lender is not only underwriting you. It is underwriting the specific property, and a financially strong borrower with excellent credit can still lose their financing because the house itself does not clear the bar.
Part of that is the appraisal, which exists to confirm the property provides adequate security for the amount being lent. Lenders may use automated valuation systems for straightforward properties and order a full appraisal where the property, value, location, or transaction warrants one. If the lender’s accepted value comes in below your purchase price, the mortgage amount can be calculated against that lower value rather than the price you agreed to pay, leaving you to cover the difference in cash.
On a CAD 900,000 purchase with an appraisal that comes back at CAD 850,000, a buyer who planned on borrowing CAD 720,000 against the CAD 900,000 purchase price may suddenly have a problem. If the lender limits the loan to 80 percent of the CAD 850,000 accepted value, it will advance only CAD 680,000. The buyer now needs another CAD 40,000 from somewhere else before the deal can close.
Property insurance runs into the same underwriting logic from a different angle. A mortgage lender generally requires evidence of acceptable property insurance effective on closing, with its interest properly noted, before it will advance the mortgage funds. Older homes with certain electrical systems, buried oil tanks, elevated wildfire or flood exposure, and seasonal cottages can all be more difficult or expensive to insure. If you cannot produce insurance acceptable to the lender in time, the lender may not fund regardless of how strong the rest of your application looks.
This is the same underlying idea as the appraisal: the property has to clear a bar independent of you, and personal financial strength does not automatically make every piece of real estate acceptable collateral.
Where Does All That Money Actually Go
The statement of adjustments is where the actual cash to close gets calculated, and it is almost never as simple as down payment minus deposit.
Property taxes are the most common item. If the seller already paid the full year’s taxes and you are taking possession partway through the year, you may owe them a prorated credit for the period after closing. If the taxes remain unpaid for a period during which the seller owned the property, the adjustment can run the other way. Condo or strata fees, prepaid fuel, rents, and other transaction-specific items can be reconciled in similar fashion.
Put the full picture together on a realistic CAD 850,000 Ontario resale purchase with 10 percent down and a CAD 25,000 deposit already paid.
The down payment is CAD 85,000, and CAD 60,000 of that is still owed after crediting the deposit. The base mortgage of CAD 765,000 sits at a 90 percent loan to value, which carries a 3.10 percent CMHC premium. That adds CAD 23,715 and produces a financed mortgage of approximately CAD 788,715.
Ontario’s 8 percent sales tax on that CAD 23,715 insurance premium, payable in cash rather than financed into the mortgage, comes to CAD 1,897.20.
Add illustrative legal fees and disbursements of a couple thousand dollars, a modest title-insurance premium, and a property-tax adjustment in the buyer’s favour or against them depending on the timing, and the buyer is looking at something in the neighbourhood of CAD 66,000 in total cash still required to close in this example, before land transfer tax is added. None of those individual professional-fee figures are standardized, so treat them as illustrative rather than exact, but the shape of the calculation holds regardless of which lawyer or insurer you use.
Land transfer tax, which can be one of the largest single closing costs in the country and varies significantly by province and, in Toronto’s case, by municipality on top of the province, belongs to its own analysis rather than a paragraph here. For this piece, treat it as a real, often substantial line item that has to be funded at closing without getting into the specific rates, exemptions, and rebates that vary by jurisdiction.
There is also a practical risk here that has nothing to do with mortgage mathematics. Real estate closings involve unusually large transfers of money, which makes fraudulent payment instructions particularly dangerous. If wiring or transfer instructions arrive by email, especially if they suddenly change, independently confirm them with the lawyer’s office using contact information you already know to be legitimate rather than relying on the contact details contained in the new message.
What Happens On Closing Day
By closing day, most of the real decisions have already been made, and what is left is a synchronization problem.
Your remaining cash arrives in your lawyer’s trust account first, usually before closing. You will already have signed the transfer and mortgage documents, sometimes days earlier. The lender releases its mortgage funds once the lawyer can satisfy the lender’s funding requirements.
The buyer’s and seller’s legal professionals then complete the exchange of funds and registration steps required in that province. The seller’s lawyer uses part of the sale proceeds to deal with the seller’s existing mortgage and other obligations that must be cleared, while the transfer of the property and the buyer’s new mortgage or hypothec are registered through the applicable provincial system.
The seller does not simply receive the full purchase price on closing day. Their lawyer first has to account for whatever is registered against the property, most commonly the existing mortgage, deal with the adjustments worked out between the two sides, and then release whatever remains as net proceeds.
The old mortgage is not magically cancelled because the house was sold. It has to be paid out and its registered charge discharged. In common-law provinces, the buyer’s lawyer can rely on professional undertakings from the seller’s lawyer to complete that discharge even where the administrative registration of the discharge follows the actual closing. Title insurance may provide another layer of protection against certain covered problems involving an old charge that was supposed to be discharged but was not, depending on the terms of the policy.
Exactly when ownership legally changes is not identical everywhere, and it turns on each province’s own land-registration law rather than one Canada-wide rule. What does hold broadly is the practical point: signing the purchase documents is not the same thing as the transaction having completed.
In Ontario’s electronic registration system, registration normally occurs as part of the closing process, so the gap between signing and registration is small. Alberta is a useful contrast. Documents submitted to Alberta Land Titles can remain pending while the registration system processes them. Alberta’s conveyancing system uses trust conditions, professional undertakings, and mechanisms designed to allow transactions to close without forcing buyer and seller to wait for the registration queue itself to finish.
Neither approach is wrong. They are simply different solutions to the same underlying problem of coordinating money, possession, registered ownership, and mortgage security without leaving one party exposed while waiting for the other.
How The Process Changes Across Canada
The financial logic of a Canadian home purchase is broadly similar everywhere: a deposit, a firm agreement, legal due diligence, mortgage funding through a regulated closing process, settlement of the seller’s existing secured debt, and a transfer recorded through the provincial or territorial land-registration system.
What changes is the legal machinery underneath that logic, and two provinces in particular are structurally different rather than just procedurally different.
Quebec is a civil-law jurisdiction, which means the conveyancing framework is built differently than in the rest of the country. Residential conveyancing ordinarily runs through a notary, and article 2693 of Quebec’s Civil Code says an immovable hypothec must, on pain of absolute nullity, be constituted by notarial act en minute. The role of the notary and the structure of the transaction therefore differ from the common-law model used elsewhere in Canada.
British Columbia is another important exception because a regulated BC notary public, a distinct profession from a lawyer, can handle many standard residential real estate transactions, including conveyancing and registration work. Buyers can therefore encounter either a lawyer or a BC notary depending on the transaction.
Everywhere else, lawyers generally handle residential conveyancing, but the registration systems themselves still differ.
Alberta’s registration timing and trust-condition system has already been described above. Saskatchewan and Manitoba operate land-titles systems, with Saskatchewan notably one of the provinces where sales tax applies to mortgage-insurance premiums.
The Atlantic provinces are often lumped together, and that hides a real difference. Nova Scotia and New Brunswick have both moved substantially from older registry-of-deeds models toward parcel-based land-registration systems, but conversion occurs parcel by parcel rather than through one single province-wide event. In New Brunswick, conversion is required when land is sold or mortgaged. In Nova Scotia, selling, mortgaging, or subdividing land into three or more lots can trigger migration into the newer system.
Prince Edward Island and Newfoundland and Labrador continue to operate registry-of-deeds systems where the registry records instruments rather than providing the same form of guaranteed registered title, which is part of why the lawyer’s title investigation and review of the chain of ownership remain particularly important.
| Province or territory | Who commonly closes it | Registration system | Notable difference |
|---|---|---|---|
| Ontario | Lawyer | Land titles, electronic registration | Ontario title insurers require a concurrent certificate of title from an independent Ontario solicitor |
| British Columbia | Lawyer or BC notary public | Land titles | Regulated BC notaries can handle many standard residential conveyances |
| Alberta | Lawyer | Land titles | Trust conditions and undertakings help transactions close while registration may still be pending |
| Saskatchewan | Lawyer | Land titles | Provincial sales tax applies to mortgage-insurance premiums |
| Manitoba | Lawyer | Land titles | No provincial sales tax on mortgage-insurance premiums |
| Quebec | Notary | Civil-law land register | An immovable hypothec must be constituted by notarial act en minute |
| New Brunswick, Nova Scotia | Lawyer | Parcel-based land-registration systems, with properties migrated from older systems | Conversion occurs parcel by parcel; the precise triggers differ between the two provinces |
| Prince Edward Island, Newfoundland and Labrador | Lawyer | Registry of deeds | Greater reliance on legal review of the chain of title |
| Yukon, Northwest Territories, Nunavut | Lawyer | Land-titles systems | Smaller markets, with territorial registration rules and practices |
Cottages Play By Different Rules
Nowhere does the idea that a lender underwrites the property, not just the borrower, show up more clearly than with a cottage, and this matters directly to a lot of Sovereign Canadian readers who already own a primary residence and are looking at a second one.
The starting mistake is treating CMHC’s rules as the whole story.
CMHC’s Second Home program is designed around properties suitable for full-time, year-round occupancy with year-round access. That rules out a lot of ordinary Canadian cottages before you even get to the rest of the mortgage application.
But CMHC is not the only insurer in this market, and Sagen in particular runs two distinct recreational-property categories that most explanations of cottage financing skip straight past.
Sagen’s Vacation/Secondary Homes program divides qualifying properties into Type A secondary homes and Type B vacation homes.
Sagen’s Type A program is the mainstream version. The property generally needs to be winterized, have a permanent heat source, acceptable running and drinkable water, and appropriate road access. A Type A purchase can reach 95 percent loan to value, subject to the tiered minimum down-payment rules for properties above CAD 500,000. Privately serviced roads can also be acceptable where an appropriate maintenance arrangement exists.
Type B is where the more interesting Canadian finding sits, because Sagen specifically relaxes several of those property requirements.
Its published criteria say a Type B property does not need to be winterized or have a permanent conventional heat source. A wood stove, fireplace, stove, or heat blower can be acceptable. The foundation can be floating, including a structure sitting on blocks. Seasonal road access is permitted even where the road is not ploughed in winter. The water source does not have to be drinkable, although running water is required inside the home. And most strikingly, Sagen explicitly says the property may be accessible only by boat.
That flexibility comes at a cost.
Type B is limited to 90 percent loan to value rather than 95 percent, so the buyer needs at least 10 percent down. Sagen requires a minimum credit score of 680 for all applicants, subject to a limited case-by-case exception where a second applicant has no credit history. The down payment has to come from the borrower’s own eligible resources rather than the broader gifted-down-payment options available under Type A.
The insurance premium is also materially higher. At 85.01 to 90 percent loan to value, Sagen’s current premium tableshows a 4.35 percent premium for Type B compared with 3.10 percent under its standard schedule.
This is not a trivial difference.
Take three versions of the same CAD 600,000 Ontario cottage to see how this actually plays out.
The first sits on a municipally maintained, year-round road, is fully winterized with a permanent heat source, and can be occupied twelve months a year. This behaves financially much more like a conventional second home. Depending on the full underwriting file, it can fit within a standard second-home program and potentially be financed with a relatively small down payment.
The second sits on a private or seasonal road, draws water from a source that is not certified drinkable, and is heated only by a wood stove. That property can fail the conventional second-home test while still sitting remarkably close to the profile Sagen explicitly designed Type B to accommodate. The financing path may therefore be an insured Type B mortgage with at least 10 percent down and a higher insurance premium rather than an automatic fallback to a conventional 20 percent-down mortgage.
The third version is water access only, with no road connection at all. Under CMHC-style year-round-access criteria that creates an obvious problem. Sagen’s published Type B criteria, however, explicitly permit boat-only access.
That does not mean every boat-access cottage can get a 90 percent mortgage. The lender still has to accept the property, the borrower still has to qualify, the appraisal still matters, and marketability, condition, land tenure, insurance, and other underwriting factors can kill the application. The important point is narrower and more useful: CMHC-ineligible does not necessarily mean mortgage-insurance-ineligible.
That distinction is easy to miss because Canadians routinely use “CMHC insurance” as shorthand for all mortgage default insurance.
It is wrong in exactly the kind of transaction where the distinction matters most.
A cottage being rejected under CMHC’s criteria does not necessarily mean it cannot be insured. The three mortgage insurers are not interchangeable, and recreational property is one place where their product differences actually matter.
Refinancing deserves similar caution. Sagen’s Type B criteria describe a specific insured vacation-home product, not a promise that the property will remain eligible for every future mortgage transaction. A later refinance would depend on the lender, the property’s value and characteristics at that time, the owner’s equity, and whatever insured or conventional products are then available. That is different from saying the property can never be refinanced.
The point worth sitting with is not that every unusual cottage will find an insurer, because plenty still will not, especially once genuine rental use, severe marketability problems, unusual construction, or land-tenure complications enter the picture.
The point is that borrower eligibility, property eligibility, lender eligibility, and insurer eligibility are separate questions.
A wealthy, high-credit borrower still cannot make every property acceptable collateral.
But which insurer and lender are actually looking at the property can change what “acceptable” means.
| Cottage scenario | Standard second-home route | Sagen Type B | What typically drives the outcome |
|---|---|---|---|
| Year-round, winterized, conventional road access | Potentially eligible with standard insured financing | Usually unnecessary | Meets mainstream occupancy, access, heat, and property criteria |
| Seasonal road, non-drinkable running water, wood heat only | May fail standard criteria | Potentially eligible with at least 10 percent down and higher premium | Type B specifically relaxes access, heat, foundation, and water requirements |
| Water access only | Major obstacle under standard year-round-access criteria | Possible in principle | Sagen explicitly permits boat-only access, but lender acceptance remains property specific |
Paying Cash Changes Less Than You Would Think
Paying cash removes an entire layer of the process, but it does not remove the underlying legal transaction.
Mortgage approval, lender underwriting, mortgage default insurance, the lender’s appraisal requirements, and lender title-insurance requirements disappear because there is no mortgage lender in the picture.
What remains is everything tied to the actual transfer of ownership. A lawyer or notary still has to perform the legal work appropriate to that province, investigate title, deal with the adjustments, move the purchase funds through the closing process, and complete the transfer through the applicable registration system.
Owner’s title insurance becomes entirely the buyer’s decision rather than something connected to satisfying a mortgage lender’s title requirements. Many lawyers will still recommend it because the premium is small relative to the value of the asset and the potential severity of a covered title problem, but the buyer can evaluate that protection on its own merits.
There is also no mortgage lender demanding property insurance before advancing funds, although condo or strata requirements, contractual obligations, or other arrangements can still create insurance requirements. More importantly, an uninsured catastrophic loss to a house you just purchased with cash would be your problem rather than a bank’s. Removing the lender does not remove the underlying property risk.
Land transfer or property transfer taxes still apply where the jurisdiction imposes them. Legal work still has to happen. Title still has to move.
What a cash purchase actually buys you is discretion and simplicity: there is no lender underwriting the property, no mortgage conditions to satisfy, no mortgage charge to register, no default-insurance application, and no lender waiting for an appraisal or proof of insurance before releasing funds.
What it does not buy you is an exemption from the legal machinery of transferring ownership in the first place.
The Whole Transaction, In One Pass
It is worth holding the entire CAD 850,000 example in your head as a single sequence rather than as a set of separate topics.
The offer is accepted and a CAD 25,000 deposit goes into trust.
Financing is finalized once the borrower and the property clear the lender’s underwriting requirements.
The lawyer searches title and arranges whatever title-insurance coverage is being purchased while the closing figures and adjustments are prepared.
The CAD 23,715 mortgage-insurance premium gets added to the mortgage, and the Ontario sales tax on that premium gets set aside in cash.
The buyer sends the remaining down payment and closing funds, roughly CAD 66,000 in total in this illustrative example before land transfer tax, into the lawyer’s trust account.
The mortgage ultimately provides approximately CAD 788,715, including the financed mortgage-insurance premium.
The buyer’s and seller’s legal professionals then coordinate the funds, the transfer, the new mortgage registration, and the clearing of the seller’s existing secured debt through the procedures used in that province.
The seller’s old mortgage is paid out. The seller receives the remaining net proceeds after the mortgage, adjustments, and other closing obligations are dealt with.
And only once the transaction has actually closed does the phone call happen:
The house is yours. You can pick up the keys.
The Point Of Understanding This
From the buyer’s side, closing can feel almost anticlimactic.
You send money. You sign documents. You wait. Then a lawyer calls and tells you that you own a house.
Behind that phone call, an entire settlement has actually taken place.
Your equity entered the transaction. Your lender funded the rest of it under conditions you may never have read closely. The seller’s old secured debt was dealt with. Title was investigated, transferred, and in many transactions privately insured. Your new mortgage was registered as security against the property. Property taxes and other prepaid items were reconciled between two people who may never have spoken to each other directly. Different risks were investigated and then allocated among the buyer, seller, lender, lawyers, land-registration system, and insurers.
Only once enough of those pieces lined up could the seller receive the net sale proceeds and the buyer receive the property.
None of this requires you to become a real estate lawyer before you buy a house.
But once you understand who is actually holding the money at each stage, why the lender is underwriting the house as well as you, what happens to the seller’s old mortgage, what registration actually accomplishes, and which party each layer of insurance is protecting, the process stops looking like a black box you are simply trusting other people to operate correctly on your behalf.
And there is a broader lesson underneath it.
Buying a house is not one transaction. It is several transactions that have to settle together.
Understanding that is what makes the rest of the process make sense.
This article covers the mechanics of the purchase itself. Land transfer and property transfer taxes, which can be a significant part of the actual cash required at closing, deserve separate treatment because the rules vary so much by province and municipality. For the financing side, including fixed versus variable rates, mortgage penalties, prepayment privileges, portability, refinancing, HELOCs, collateral charges, construction financing, and what happens when you sell before maturity, see Mortgages in Canada: The Deep Dive.
This article is provided for general educational purposes and reflects the Canadian home-buying process as understood as of 2026. It is not legal, tax, insurance, or financial advice. Real estate, land-registration, mortgage, and closing rules vary by province and can change. Speak with a licensed real estate lawyer or notary and an appropriate mortgage professional about your specific transaction before relying on anything above.