Prices are Oct. 2, 2026 TSX closes. All dollar figures are Canadian.
Most Canadian investors already own every major Canadian bank without ever having decided to buy one. A broad TSX index fund holds all six, a balanced fund holds all six, and so does the dividend mutual fund your advisor chose a decade ago. I am in that position. When I say I’m thinking about buying a Canadian bank stock, I am not really asking whether to get bank exposure, because I have it. I am asking whether any one of the six deserves to become a deliberate overweight, a bet that this particular bank will outperform its weight in the index I already hold.
That is a different question from the ones bank articles usually answer. It is not which bank is largest, which has the highest dividend, or which is the “best company.” Those can have different answers, and in this case they do. The best business, the best historical compounder, the cheapest stock, the highest income and the best purchase at today’s price are not the same bank, and treating them as one is how people end up with a 3.5% yield and a decade of disappointing returns.
So the test I applied was narrow. If I had another $1,000, $5,000 or $10,000 and wanted it to do something the index was not already doing for me, where would it go? I looked at what each bank has actually delivered to shareholders, what it is earning now, what the balance sheet looks like, and what the market is asking me to pay today. The answer got less obvious as I went, and it ended up somewhere I did not expect when I started.
Why bank stocks have worked, and why that doesn’t settle anything
The Canadian banking system is concentrated, tightly regulated and unusually profitable. Six banks dominate deposits, mortgages, commercial lending and wealth management, regulators force them to hold large capital buffers, and the result has been a long record of rising dividends and steady compounding. None of that is controversial. What it does not tell you is which of the six has turned that structure into the most wealth per share, and that turns out to be the interesting part.
The gap between the six is much larger than most investors assume. Using a total-return dataset with dividends reinvested and endpoints at or near Oct. 2, 2026, the ten-year annualized return ranges from roughly 10.7% for Scotiabank to roughly 16.5% for CIBC. On $10,000, that is about $27,600 versus about $46,000 after ten years, from owning two banks that sit under the same regulator and sell mostly the same products. The business is a shared structure. The outcomes were not shared.
The historical record
The table below uses a consistent total-return series from FinanceCharts, which covers five of the six banks. I treat it as a secondary source, but its figures are internally consistent. National Bank is not covered cleanly in that dataset, so I handle it separately below rather than pretend its numbers line up.
| Bank | 5-yr annualized | 10-yr annualized | 20-yr annualized | $10,000 over 5 yrs | over 10 yrs | over 20 yrs |
|---|---|---|---|---|---|---|
| RBC | ~18.0% | ~16.3% | ~11.3% | ~$22,900 | ~$45,300 | ~$85,100 |
| CIBC | ~19.1% | ~16.5% | ~9.9% | ~$24,000 | ~$46,000 | ~$66,100 |
| TD | ~16.5% | ~14.7% | ~10.7% | ~$21,500 | ~$39,400 | ~$76,400 |
| BMO | ~14.6% | ~14.2% | ~9.1% | ~$19,800 | ~$37,700 | ~$57,100 |
| BNS | ~13.7% | ~10.7% | ~8.0% | ~$19,000 | ~$27,600 | ~$46,600 |
Dollar outcomes are my compounding of the annualized figures (10,000 × (1 + CAGR)^years). Treat them as approximations; five-year and ten-year figures are sensitive to endpoint dates.
National Bank’s evidence is thinner and older, and I would rather say so than manufacture a number. In its annual report for fiscal 2019, National Bank reported annualized total shareholder returns of 13.9% over ten years and 15.1% over twenty, and described them as industry-leading. Those figures end in October 2019, seven years before the Oct. 2 table above, and I did not find a comparable same-method series for National Bank ending in 2026. Nothing in the more recent material I reviewed contradicts that picture, but none of it gave me a clean number I would publish. So my working conclusion about National Bank is qualitative: it has been one of the strongest long-term compounders among the six, and quite possibly the strongest. Scotiabank, by contrast, ranks last at every horizon in the table above.
Three features of the record are worth stating plainly. Royal Bank has been consistently excellent, near the top at every horizon. CIBC’s five- and ten-year numbers are essentially level with RBC’s, which is not what its reputation would lead you to expect, and I come back to that below. And the order at the bottom does not move: Scotiabank is last at five, ten and twenty years, and BMO sits in the middle at ten and twenty.
Past returns are not forecasts, and some of these returns came from starting points that no longer exist. What the record does tell me is which franchises have actually converted their position into per-share wealth through a full cycle that included a pandemic, a rate shock and the 2022 housing scare. A bank that has done that over twenty years has shown something about management and culture that a single good quarter cannot.
What I’d be paying today
This is the part that changed the argument. The valuation data below is S&P Global Market Intelligence-derived, via StockAnalysis, as of Oct. 2, and the dividends are the current quarterly rates from each bank’s latest declaration multiplied by four.
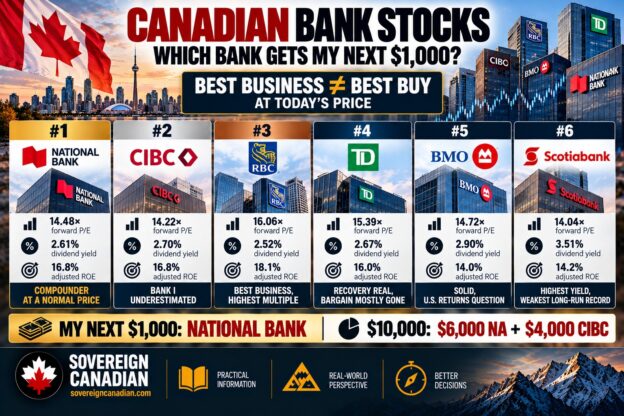
| Bank | Oct. 2 close | Annual dividend | Yield | Forward P/E | Price/book | Forward earnings yield |
|---|---|---|---|---|---|---|
| RBC | $278.91 | $7.04 | 2.52% | 16.06x | 2.66x | 6.2% |
| TD | $168.07 | $4.48 | 2.67% | 15.39x | 2.16x | 6.5% |
| BMO | $236.25 | $6.84 | 2.90% | 14.72x | 1.90x | 6.8% |
| NA | $202.51 | $5.28 | 2.61% | 14.48x | 2.24x | 6.9% |
| CIBC | $158.27 | $4.28 | 2.70% | 14.22x | 2.11x | 7.0% |
| BNS | $129.93 | $4.56 | 3.51% | 14.04x | 1.75x | 7.1% |
Forward earnings yield is the inverse of the forward P/E. StockAnalysis’s book value uses its own definition; RBC’s reported common equity would imply a somewhat higher price-to-book than 2.66x.
The range is narrow. From the cheapest bank to the most expensive is two P/E turns, about 14%. Royal Bank is the most expensive, but only about 14% above Scotiabank, 13% above CIBC and 11% above National Bank. TD, which was a distressed stock two years ago, trades at 15.4x and sits second most expensive. National Bank, the historical premium name, trades at 14.5x, a hair above CIBC and about three percent above Scotiabank.
Backing out the earnings implied by those multiples gives something I found useful. At those prices and forward P/Es, the earnings the market is capitalizing work out to within a few percent of each bank’s third-quarter adjusted EPS annualized. For example, RBC’s $278.91 at 16.06x implies about $17.37 of forward earnings against $17.12 for Q3 times four, and National Bank’s $202.51 at 14.48x implies about $13.99 against $13.56. In other words, the market is paying 14x to 16x not for a growth story but for roughly the earnings power the banks showed in their third quarter, a quarter helped by strong capital-markets and wealth results across the group. TD’s implied $10.92 sits slightly below its Q3 annualized $11.08, which tells me the consensus doesn’t assume that quarter fully repeats there. National Bank’s implied figure is the furthest above its annualized quarter, which fits its growth profile. This is arithmetic on secondary data, not a forecast, but it frames the valuation question correctly: the debate is less about future growth than about whether Q3 earnings are a reliable base.
Is 15x too much for a bank?
Around 15x forward earnings is well above the ten-year average. Brompton’s analysis, using Bloomberg data as of Aug. 27, put the Big Six at 15.2x fiscal 2027 consensus earnings on a market-cap-weighted basis, against a ten-year average of 10.9x. It also cites Scotiabank research for a historical discount of about 28% to the S&P/TSX Composite Total Return Index, which it says has narrowed to a slight discount. I treat all of this as secondary evidence, and Brompton sells bank-focused split-share funds, so its argument that a mid-teens multiple is the new normal is advocacy as much as analysis. Other estimates I have seen put the decade average between 10.8x and 11.2x, so the order of magnitude seems right.
I don’t read the gap as a sentence of 25% downside. The reasons banks might hold higher multiples are not frivolous: capital ratios in the 13% to 14% range, a larger fee-based wealth contribution, less need to chase expensive U.S. acquisitions, a broader pool of buyers, and more room to deploy capital after OSFI lowered the Domestic Stability Bufferto 3.0% from 3.5% in June. Whether those are durable is a judgment, not a measurement. What I do conclude is narrower and, I think, safer. Returns from today’s starting valuations are likely to be lower than the extraordinary returns of the last five years, because those started from much cheaper multiples. RBC’s own numbers show how large the change has been: its price rose 65% in the twelve months to July 31 while trailing diluted EPS rose about 20%, which means its trailing P/E went from roughly 13.5x to roughly 18.5x, and it was about 17.6x at the Oct. 2 close.
I’ll come back to whether waiting makes sense. It matters here that this is a modest dispersion at an elevated level. Whatever I buy, I am buying at about the same multiple as everyone else.
Royal Bank: the best business, at a premium that history partly earns
Royal Bank is the benchmark the other five get measured against. In the third quarter it earned a record $6.0 billion, with an adjusted ROE of 18.1%, an adjusted efficiency ratio of 52.2%, a 13.5% CET1 ratio and a provision ratio of 36 basis points, all from its Q3 report. Its earnings are diversified across personal banking, commercial banking, wealth management, capital markets and insurance in a way no other Canadian bank matches, and it has returned about 16% a year over ten years with dividends reinvested.
The worry is what produced the latest quarter. Wealth Management net income rose 32% and Capital Markets rose 16%, both on record equity markets, strong trading and heavy underwriting. Personal Banking, the core Canadian franchise, earned 1% less than a year ago, with operating leverage of negative 4.2%. RBC’s adjusted EPS grew 11%, the slowest of the six this quarter. Some of that is a higher base, but it means the argument that RBC compounds faster than its peers rests on the historical record, not on the last quarter.
That is where the valuation question gets concrete. RBC trades about 14% above Scotiabank on forward earnings. To close a 14% premium over five years, RBC would need to outgrow Scotiabank by about 2.7 percentage points a year in total return. Because Scotiabank’s yield is about a point higher, that translates to an earnings-growth lead of roughly 3.7 points a year. Over ten years the required earnings-growth lead falls to roughly 2.3 points. Against that, RBC’s ten-year total return exceeded Scotiabank’s by about 5.6 points a year. Starting and ending valuation differences mean I cannot simply attribute the remaining gap to earnings growth, but the size and persistence of the return advantage still suggest that RBC’s superior compounding has historically been more than a valuation effect.
So I don’t think RBC fails on price. It is expensive relative to the other five, but it is not irrationally expensive, and the history gives me reason to believe part of the premium is deserved. What it is not is cheap, and with a forward earnings yield of about 6.2%, the lowest of the six, it offers the least cushion if the capital-markets and wealth tailwind fades. It is also already the largest holding in whatever index fund I own, which weighs on me later.
TD: the recovery is real, and the bargain is mostly gone
TD changed the most while I was working through this. Its group return on equity is easy to confuse with that of its U.S. retail segment, which was 10.2% in the third quarter. The bank as a whole earned an adjusted ROE of 16.0%, adjusted EPS grew 26%, and its CET1 ratio was 14.3%, the highest of the six, all per its Q3 release. Management says it expects to significantly outperform its fiscal 2026 targets of roughly 13% adjusted ROE and 6% to 8% adjusted EPS growth.
The regulatory story hasn’t ended. TD’s U.S. operations remain under the October 2024 resolution described in its filing with the SEC: about US$3.09 billion in penalties, guilty pleas by two U.S. subsidiaries, an independent monitor, and an asset limitation of US$434 billion on its U.S. banking subsidiaries. On the Q3 call, the head of U.S. banking said the consent order is still in place, and TD’s own disclosure says significant remediation milestones remain in calendar 2026 and 2027. The company expects to spend about US$550 million on U.S. AML remediation this fiscal year, up from US$500 million. It plans to open 100 U.S. branches by the end of 2028, subject to regulatory approval. TD also sold its entire remaining Schwab stake in February 2025, so Schwab no longer contributes earnings.
What the research did to my view of TD is straightforward. At the start, TD looked like a regulatory discount, a high-quality franchise priced for a problem. At 15.4x forward earnings and 2.16x book, with the stock up sharply, the market has already recognized much of the recovery. The case for the next leg is different and less dramatic. It rests on earnings growth, on the buyback, and on eventual regulatory normalization.
The buyback is the part I underrated. In the third quarter TD repurchased about 14.5 million shares, roughly 0.9% of its share count in a single quarter, and its Q3 report shows average diluted shares of 1,652 million against 1,719 million a year earlier, a decline of about 4%. TD expects its CET1 ratio to fall to approximately 13% by October 31, 2027. The difference between 14.3% and 13%, applied mechanically to current risk-weighted assets of about $653 billion, is roughly $8.5 billion, around 3% of TD’s market value. That is arithmetic, not guidance, and actual deployable capital will depend on RWA growth, earnings, regulatory requirements and other uses of capital. Management has said that if organic capital generation and RWA growth continue at this year’s pace, TD could repurchase more than $13 billion of shares in fiscal 2027 to reach 13%, because it keeps generating capital along the way. None of that is guaranteed to reach shareholders. But it is real support for per-share growth, and it comes with a regulatory tail that the other five banks do not have.
National Bank: the compounder that is not expensive
National Bank was the candidate I expected to dismiss. It is the smallest of the six, it has a long record of trading at a premium, and I assumed the research would show a great business priced as one. The data didn’t cooperate. At $202.51 it trades at 14.48x forward earnings, only about 0.4 turns above Scotiabank and a quarter-turn above CIBC, and well below RBC and TD.
The historical case, as discussed above, is strong but less precisely documented than I would like. The 2025 acquisition of Canadian Western Bank, about $5 billion, extended its commercial banking into Western Canada, and it diluted shareholders substantially: the share count rose from about 340.6 million to about 391.2 million around the transaction, roughly 14.9%, a figure I computed from share counts in Canjex/Stockwatch’s records. S&P Global-derived data now shows about 383 million shares, so some of that has been bought back. The question is therefore whether per-share growth remains superior after the dilution, and the answer so far is yes. According to its Q3 release, third-quarter adjusted EPS grew 26%, nine-month adjusted EPS grew 17% (to $9.88 from $8.46), and net income rose 23% to $1.307 billion. Adjusted ROE was 16.8% for the quarter (16.1% reported) and 16.7% for the nine months (15.9% reported). The CET1 ratio was 13.5%, the reported dividend payout ratio was 41.1%, which leaves room to grow the dividend, and management reiterated a target of 17% or better adjusted ROE in 2027. Its realized provision ratio was about 31 basis points, the lowest of the six.
The worries are real. The bank is smaller and more concentrated, in Quebec and now in Western Canadian commercial banking, and capital-markets activity is a meaningful part of the mix. Its CET1 ratio has slipped from 13.8% at October 2025 to 13.5%, and management expects it to trend toward roughly 13% by the end of 2027, with the Laurentian retail and SME portfolio acquisition, expected to close late this year, using up part of the cushion. It repurchased only 2.3 million shares in the quarter. And part of its recent return was a rerating: a June 2025 Globe and Mail column put it at 12.3x forward earnings, so the multiple has risen about two turns in sixteen months.
Using the premium-versus-growth framework, the numbers are small. National Bank’s 3% premium to Scotiabank requires only about a 1.5-point annual earnings-growth lead over five years, or about 1.2 points over ten, after allowing for the yield gap. Against CIBC, with a premium of under 2%, the required advantage is a fraction of a point. I had assumed the research would show National Bank was an excellent business with a price to match. It showed an excellent business priced like a normal one.
CIBC: the bank I underestimated
CIBC carries a reputation as the housing-heavy, consumer-credit-heavy bank that blows up when Canada’s economy turns, and the reputation has a history behind it. The numbers I found don’t fit it very well. Over five years CIBC’s total return was about 19.1% a year and over ten years about 16.5%, slightly ahead of Royal Bank at both horizons in the same dataset. The one place its record is less impressive is twenty years, at about 9.9% versus RBC’s 11.3% and TD’s 10.7%, so the recent excellence is not a long-run pattern.
Its third quarter was strong. According to its Q3 results, adjusted EPS grew 26% to $2.73, adjusted ROE was 16.8% (15.2% reported, up from 14.2% adjusted a year earlier), CET1 was 13.4%, and the adjusted efficiency ratio improved to 52.7% from 54.7%. Revenue rose 15% to $8.37 billion, Canadian personal and business banking earned $948 million, up 17%, and CIBC raised its dividend about 10% to $1.07. Provisions for credit losses were $564 million against $559 million a year earlier, essentially flat on a much larger revenue base. Its total PCL ratio was about 37 basis points, while impaired PCL was about 40 basis points, and management cited a gross impaired loan ratio of 65 basis points. It also repurchased 7.5 million shares in the quarter. At 14.22x forward earnings, 2.11x book and a 2.70% yield, the market is asking for roughly what it asks for Scotiabank, a bank earning meaningfully less on equity with a substantially higher current credit-loss ratio.
There are two flags I would not skip. Reported expenses rose about 18% against 15% revenue growth, though some of that reflects items of note, including the sale of CIBC Caribbean; adjusted expenses rose more slowly and the adjusted efficiency ratio improved. And the housing concern is not imaginary. As reported from its third-quarter call, CIBC’s 90-day mortgage delinquency rate rose to 0.51% from 0.36% a year earlier, and on uninsured mortgages in the Greater Toronto Area it rose to 0.66% from 0.44%. Management said it did not expect a material increase in losses given the loan-to-values in the uninsured book, which I discuss in the credit section. The old shorthand, CIBC as the lower-quality bank, is not enough on current evidence, and a stock priced like Scotiabank while delivering returns closer to RBC’s deserves a serious look. But it is also the one bank where I found rising mortgage delinquencies in the data, and I did not reconstruct the others’ delinquency series well enough to say CIBC is unusual.
Scotiabank: a real improvement, a long record of disappointment
Scotiabank gives the strongest income argument in the group. It is the cheapest at 14.04x forward earnings and 1.75x book, and it yields 3.51%, the highest of the six by a wide margin. The operating improvement is also real. In the third quarter, per its Q3 filing, net income was $2.95 billion, adjusted EPS rose 21% to $2.28, and adjusted ROE reached 14.2%, which management says meets its 14% medium-term target a year earlier than planned. Global Banking and Markets earned a record $647 million, up 37%. Its CET1 ratio was 13.1% after buying back 8.6 million shares.
I started this research worried that the gap between reported and adjusted ROE would turn out to be large, and in the third quarter it essentially disappeared: reported ROE was 14.1% against 14.2% adjusted, a gap of about $20 million of net income, or a cent a share. The earlier gap was real, though. In the first quarter reported EPS was $1.73 against $2.05 adjusted, so the exceptional items were large in the recent past. I have not reconstructed the item-by-item reconciliation for the last six quarters, so I can say the recent quarter is clean and I cannot say the earlier charges were truly one-off.
The shareholder record is what bothers me. Scotiabank’s total return was about 13.7% over five years, 10.7% over ten and 8.0% over twenty, the lowest of the six at every horizon. Its dividend has also grown slowly. Using dividend histories compiled by Trendlyne, a secondary source, the quarterly dividend rose from $0.90 in October 2021 to $1.14 now, about 4.8% a year over five years, and it was flat at $1.06 from mid-2023 through January 2025. By comparison, BMO’s dividend grew about 10% a year over the same five years on the same kind of series. The valuation discount is therefore not arbitrary. There is a difference between a stock that is cheap because the market misread it and a stock that is cheap because it has compounded shareholder capital more slowly for a very long time, and Scotiabank’s record belongs to the second category until proven otherwise.
The honest question is whether 14.2% is a durable level. ROE moved from 13.0% in the first quarter to 13.2% in the second to 14.2% in the third, a one-point jump in a quarter when capital markets earned a record. That sequence suggests some cyclical help, and I would underwrite something nearer 13% to 13.5% until two more quarters confirm it. Compared with CIBC, which trades at nearly the same multiple (14.22x versus 14.04x), Scotiabank offers a better yield but lower ROE, a much higher current total provision ratio — 56 basis points against about 37 — and a weaker long-term shareholder record. The yield is the clearest reason I would choose Scotiabank, and it is a good reason only if I care about current income more than expected total return.
BMO: solid, with one unresolved question
BMO’s third quarter looked messy on the surface and decent underneath. Reported net income fell 25% to $1.75 billion because of a $962 million after-tax goodwill-related charge tied to the announced sale of its Transportation and Vendor Finance businesses, and reported ROE was 8.4%. Adjusted net income rose 19% to $2.86 billion, adjusted EPS rose 22% to $3.96, adjusted ROE was 14.0% against 12.0% a year earlier, the adjusted efficiency ratio was 54.9%, and CET1 was 13.0%, all from its earnings release. It also announced a 25 million-share buyback, roughly 3.5% of its shares.
The question is the U.S. business. BMO’s U.S. Banking segment earned an adjusted ROE of 9.8% in the quarter, up 90 basis points from a year earlier, against 14.0% for the bank as a whole, according to its investor presentation. A bank’s cost of equity is somewhere around 9% to 10% by most estimates I know of, so 9.8% is roughly break-even on the capital allocated to it. That doesn’t make the Bank of the West acquisition a failure, and I did not assemble the purchase price, synergy and capital-consumption record needed to say whether it created shareholder value. But the current returns don’t show the surplus the deal needed, and the sale of the transportation and vendor finance business, with a near $1 billion goodwill write-down, shows that earlier acquisitions have also cost something.
At 14.72x forward earnings, 1.90x book and a 2.90% yield, BMO sits in the middle. Its ten-year total return of about 14.2% is respectable, and its dividend growth has been strong, about 10% a year over five years and about 7% over ten by the same Trendlyne series. It is a sound bank. I couldn’t find the thing that makes me want to overweight it over National Bank, CIBC or RBC.
Income: the highest yield is not the best income investment
Scotiabank’s 3.51% yield is a full point higher than Royal Bank’s 2.52%, and on a $10,000 purchase it pays about $351 a year against about $252. That is the argument for it, and it is not nothing. But the more useful comparison is how fast the dividend grows. Royal Bank’s quarterly dividend rose 14% in a year, from $1.54 to $1.76, with a payout ratio near 41%. CIBC raised its dividend about 10%, from $0.97 to $1.07. National Bank went from $1.14 in December 2024 to $1.32 this year, about 16% in 17 months. Scotiabank’s most recent increase was about 4% and its five-year dividend growth about 4.8% a year. I cover the Canadian tax treatment and account-location side of these distributions separately in Dividend Tax Treatment in Canada.
Using my own illustrative assumptions of 8% growth for RBC and 5% for Scotiabank, the annual income after five years on a $10,000 purchase would be about $370 for RBC and about $448 for Scotiabank, so Scotiabank still leads on income. RBC would need to grow its dividend about 12% a year for five years to catch it under those assumptions. Income is also only part of what I would be paid. A bank yielding 3.5% that grows earnings at 5% and a bank yielding 2.6% that grows earnings at 9% to 10% are not close in expected total return if those growth rates persist, and the long-term shareholder returns above show how large that difference can become. If I wanted the highest current income, Scotiabank wins. If I wanted the best long-term income stream, I would be looking at the banks whose dividends are growing faster from sustainable payout ratios.
Housing and credit: what the evidence supports
I would like to give you a clean ranking of which bank is most exposed to a Canadian housing downturn. The disclosures do not support one. Each bank reports its mortgage book on a different basis and date, and putting them in a single table would produce false precision.
What the disclosures do say is that the two banks where I could verify the numbers have large exposure. RBC had about $473 billion of Canadian residential mortgages at July 31, about 81% uninsured, with an average loan-to-value of about 62% on the whole book indexed for house prices, about 70% on new originations, and about $43 billion of home equity lines, per its Q3 report. CIBC, as reported from its third-quarter call, had uninsured mortgages making up about 86% of its Canadian mortgage book, with an average loan-to-value of about 58% on the uninsured portfolio, up from 54% a year earlier as prices softened, about 62% in the Greater Toronto Area and about 53% in Greater Vancouver. It also reported about $19.8 billion of home equity lines and about $71 billion of mortgages, roughly a quarter of the book, renewing over the next four quarters at average loan-to-values of 56% to 62%. TD, Scotiabank and BMO also carry large Canadian mortgage books, but they disclose them on different bases and dates, and I did not reconstruct them well enough to quote here.
Even the two sets I have do not line up: RBC’s 62% is a whole-book figure indexed to prices, CIBC’s 58% covers only the uninsured portfolio. What they share is that more than four-fifths of each book is uninsured and that Ontario and British Columbia are large parts of it. RBC’s own data show that a 15% decline in prices would take its average loan-to-value from about 62% to about 73%, and a 25% decline to about 83%, still below 100% in aggregate; the losses in a real housing downturn would come disproportionately from borrowers with less equity and less capacity to absorb payment stress, which the banks do not disclose in a clean, directly comparable six-bank dataset. I cannot honestly say one of the six is the housing bank and another is insulated.
The more comparable data are the realized provision ratios for the third quarter: about 31 basis points at National Bank, 36 at RBC, about 37 at TD, about 37 at CIBC, 41 at BMO and 56 at Scotiabank. Those are outcomes, not exposures, and Scotiabank’s higher figure reflects more than its Canadian mortgage book. They do say something useful about my earlier assumptions. The concern I had about National Bank’s Canadian credit exposure is not visible in its current results, where it posts the lowest loss ratio of the six, and CIBC’s current total provision ratio is essentially level with TD’s and only slightly above RBC’s. That is not proof that either is safer in a recession. It is a reason not to assume the reverse.
Rates are the other live variable. The Federal Reserve raised its target range to 3.75% to 4.00% on September 16, its first increase since 2023, per the Federal Reserve, and the Bank of Canada held at 2.25% on September 2 while saying upside risks to inflation had increased, per the Bank of Canada. Both central banks announce again on October 28. Higher long-term yields feed into fixed-rate mortgage renewals, which is the channel through which rates reach bank credit. I don’t treat that as a reason to time an entry, but it is the one macro variable I would watch.
Should I just wait for cheaper banks?
The case for waiting is that banks trade at roughly 14x to 16x against a decade average of about 11x. The case against is that waiting has a cost, and the cost is easy to miscalculate. If a bank trading at 14.5x grows earnings 8% a year while its share price goes nowhere, its multiple falls to about 11x in roughly 3.6 years. If instead the multiple stays at 14.5x while earnings grow 8%, the share price has to rise roughly with earnings, and I collect the dividend along the way. Those are very different paths, but either one illustrates the problem with waiting indefinitely for the historical multiple to reappear.
A 10% correction could certainly make the purchase more attractive, but I would need both the correction and the willingness to buy when it arrives. Meanwhile a bank growing earnings at something like 8% and yielding around 3% has a substantial expected-return hurdle for cash sitting on the sidelines. I have no reliable way to assign a probability to the next 10% correction that makes waiting obviously superior.
So I don’t conclude that the banks are too expensive to buy. I conclude that I am being asked to pay full prices for good businesses, that expected returns are probably lower than the last five years, and that for someone who already holds the whole group through an index, the incremental dollar has a high hurdle. Staging a purchase around the October 28 central-bank decisions and the fourth-quarter results in early December is reasonable. Deferring indefinitely for 11x is not.
One bank, or the funds I already own
Most people reading this already own the banks. A cap-weighted Canadian index fund holds the six in proportion to their size, and by my calculation from Oct. 2 market values, Royal Bank and TD together account for more than half of the Big Six’s combined market capitalization, at roughly 32% and 23%, while National Bank is about 6%. An equal-weight fund like ZEB tracks the Solactive Equal Weight Canada Banks Index with a 0.25% management fee and a 0.28% MER, and targets roughly equal weights; at June 30 its holdings had drifted to 17.4% in Royal Bank and 15.8% in National Bank, so it materially lifts the smaller banks relative to a broad index fund.
The reason to buy an individual bank is a conviction that it will beat its weight. That is the same distinction I make more broadly between owning the market and deliberately selecting individual companies: the individual position should be doing something the diversified fund is not already doing for me. For readers working through that broader allocation question, I keep the related material in the Finance & Tax for Canadians roadmap.
The evidence here suggests the excess return from choosing well could be meaningful, but it is not something I can count on, and dispersion in historical outcomes has been wide. That is a reason to choose carefully and to limit the amount, not a reason to avoid choosing. It also means that adding to Royal Bank or TD would deepen a concentration I already have through my funds, whereas adding National Bank or CIBC would not.
Tax
Dividends from the six are eligible Canadian dividends. In a taxable account, the CRA’s rules apply a 38% gross-up, and the federal dividend tax credit is 15.0198% of the resulting taxable amount, with a provincial credit layered on top. The effective tax rate therefore depends on province and income, and there is no single Canadian dividend tax rate. I work through those mechanics in much more detail in Dividend Tax Treatment in Canada.
In a TFSA, investment income and withdrawals are generally tax-free. An RRSP or RRIF shelters investment income while it remains inside the plan, with withdrawals generally taxable when they come out. That difference is one reason account location matters as much as the nominal dividend yield; I cover the broader account trade-off in RRSP vs TFSA: The Decision Changes as Your Income Rises.
Capital gains in a non-registered account are currently subject to a 50% inclusion rate. The proposed increase to two-thirds did not proceed, and the CRA reverted to administering the one-half inclusion rate. I cover the mechanics separately in Capital Gains Taxes in Canada.
For T1135 reporting, the Canada Revenue Agency’s guidance treats shares of non-resident corporations as specified foreign property regardless of whether they are held through a Canadian or foreign broker, while shares of a Canadian-resident corporation can become specified foreign property when they are situated, deposited or held outside Canada. Registered plans including RRSPs, RRIFs and TFSAs are excluded from T1135 reporting.
For a Canadian bank, that means the exchange on which the shares trade does not determine the answer. Buying the NYSE-listed line does not by itself turn a Canadian-resident corporation into foreign property. A Canadian bank share held in Canada through a Canadian brokerage is not T1135 property merely because the security also trades in New York, whereas shares of a Canadian-resident corporation held through a foreign account can be specified foreign property. The filing threshold is based on the total cost amount of specified foreign property exceeding $100,000 at any time during the year, not its market value.
The ranking
I ranked all six for a new incremental investment at Oct. 2 prices, and I did not start from the earlier TD-and-RBC ordering. The evidence moved the order materially.
| Rank | Bank | Forward P/E | Yield | Adj. ROE (Q3) | Long-run record | Main concern |
|---|---|---|---|---|---|---|
| 1 | National Bank | 14.48x | 2.61% | 16.8% | One of the strongest | Size, capital-markets sensitivity, CET1 drift |
| 2 | CIBC | 14.22x | 2.70% | 16.8% | Excellent 5/10 yr, weaker 20 yr | Housing/consumer concentration, rising mortgage delinquencies |
| 3 | RBC | 16.06x | 2.52% | 18.1% | Consistently strong | Highest multiple, market-sensitive growth |
| 4 | TD | 15.39x | 2.67% | 16.0% | Solid | Regulatory tail, no longer cheap |
| 5 | BMO | 14.72x | 2.90% | 14.0% | Middle | U.S. returns near cost of equity |
| 6 | Scotiabank | 14.04x | 3.51% | 14.2% | Weakest of five-bank dataset | Long record of underperformance |
National Bank and CIBC are essentially tied on current valuation and on current earnings power. Both earned an adjusted ROE of 16.8% in the quarter, both carry CET1 ratios of about 13.4% to 13.5%, both trade at 14.2x to 14.5x, and both are buying back stock. The difference between them is the quality and character of the evidence behind each. National Bank’s adjusted and reported ROE sit closer together (16.8% and 16.1%) than CIBC’s (16.8% and 15.2%), its current realized credit losses are the lowest of the six, its dividend is growing quickly from a low payout, and its long-run record, though not precisely measured to the same 2026 endpoint, is among the best. CIBC has equally good recent returns and a better-documented five- and ten-year record, but its twenty-year record is weaker and its principal risk, Canadian housing and consumer credit, is one where mortgage delinquencies have risen over the past year. At the same time, CIBC’s total Q3 provision ratio of about 37 basis points is currently much better than the old reputation would imply.
The fact doing the most work in putting National Bank first is the durability of its record and its current credit results, and the fact that most threatens that ranking is that I could not pin the long-term record down to a single clean same-endpoint 2026 number. If a better dataset showed National Bank’s long-run edge was smaller than I believe, I would call the two a tie, and I would not argue strongly with anyone who preferred CIBC.
Royal Bank sits third because it is the best business and the most expensive, not because I doubt it. If its earnings growth stays above Scotiabank’s by three to four points a year, it earns back the premium within five years or so, and I would be unsurprised if it ended up the best of the group. TD is fourth because the bargain is gone and the regulator still has a say over its growth. BMO and Scotiabank are fifth and sixth, but I am least confident in the difference between them. Scotiabank’s yield and its lowest multiple are real, and its improved ROE could prove structural, but a bank that has trailed the other five banks in the comparable historical dataset at the horizons I examined has to demonstrate that the improvement is durable. One good quarter does not do that.
My next $1,000, $5,000 and $10,000
My next $1,000 goes to National Bank. It combines a long-term compounding record that is among the strongest of the six, the lowest current realized credit-loss ratio in the group, an adjusted ROE of 16.8%, a CET1 ratio of 13.5%, a payout ratio near 41% and a forward multiple of 14.5x, which is not much of a premium. I would be overweighting a bank that has turned its franchise into per-share wealth at a price that doesn’t require me to assume it will keep doing so at an extraordinary rate. And I would be adding to the smallest slice of what my funds already hold.
My next $5,000 still goes to National Bank, all of it, and I would not split it to look balanced. Between $1,000 and $5,000 nothing in the evidence changes the ordering, and a second bank would dilute the one position I have an evidence-based reason to prefer. That reasoning leans on a historical record I could not measure to the same 2026 endpoint as the other five, and if I trusted it less I would start splitting at this size. I might hold a small amount back for the October 28 central-bank decisions and the early-December fourth-quarter results, but that is a timing choice, not a different conclusion.
My next $10,000 is where I would split, but not evenly. I would put roughly $6,000 in National Bank and roughly $4,000 in CIBC. The two trade at nearly the same multiple with the same current adjusted ROE, and the evidence separating them is thin enough that I do not want the whole amount to depend on one of them. They also don’t carry exactly the same main risk: National Bank’s is integration, concentration and capital-markets exposure, while CIBC’s is Canadian housing and consumer credit.
The alternative I weighed seriously is simply adding the $10,000 to a broad Canadian index fund, which has the virtue of requiring no judgment, and for an investor who doesn’t want to monitor individual banks that is a defensible choice. I do not think the evidence supports more than one or two deliberate overweights, and it supports none strongly enough that I would call it a certainty rather than a lean.
I would not put new money into Royal Bank or TD for the purpose of overweighting, mostly because my funds already give me a large weight in both. If I were building a position purely on quality and didn’t care about price, Royal Bank is the one I would pick. At these prices the question is different, and National Bank answers it better.