Part of the Sovereign Canadian Thought Leaders series, profiles of the writers, investors, and thinkers who shaped how I think about money, freedom, and geography. This is personal documentation of what I’ve read and what I’d actually use, not financial advice. Read me as a peer taking notes, not an analyst issuing a rating.
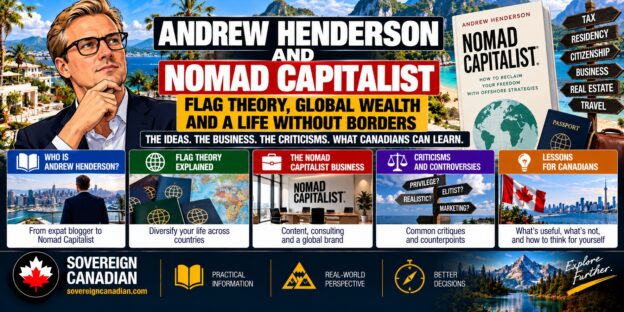
For a lot of people today, flag theory means Andrew Henderson. He didn’t invent it. What he did was attach a slogan to it, then a YouTube channel (I’m a subscriber), a book I really should read, and a consulting firm called Nomad Capitalist, and then repeat the slogan until it stuck: go where you’re treated best.
That’s a real achievement, and it’s why he belongs in this series. His questions are good ones, and I want to read them through a Canadian filter. Henderson is a skilled popularizer and the founder of a consultancy positioned at the premium end of the market, and the hinge of his own story, giving up his American citizenship, is a move Canadians don’t need to make. Take his playbook straight from the American version and you can end up solving a problem we don’t have while missing the ones we do.
So this profile covers who he is, what he actually teaches, what the criticism looks like once the noise is stripped out, and what survives the trip across the border. One note up front: the biography below is Henderson’s own account, drawn from his sites, his book, and his interviews, and I haven’t audited it. Canadians also need a filter, because the playbook was built around an American problem and the useful question is what carries over.
Who Andrew Henderson Is
Henderson grew up in northern Ohio, in the Cleveland area, around broadcasting. His father hosted a talk show alongside a financial services practice, and Henderson drifted into radio himself as a teenager. He ran a lemonade stand at eight, dropped out of Arizona State University at 19, and started a broadcasting company that was earning eight figures in annual revenue by the time he was 22. He sold that business around age 28, also for eight figures, after a few detours through insurance and swimming pools.
The turn came with the travel. He was spending more than half of each year outside the United States and still paying about 43% in tax, with the remainder reinvested in American businesses that generated more tax as they grew. The 2008 financial crisis then supplied the question. A run of U.S. bank failures and a ranking that put American banks near 40th in the world for safety made him ask whether the United States was really the best place to bank, build a business, or live. He started travelling to find out.
He began studying global tax, banking, and immigration in 2007 and founded Nomad Capitalist in 2012. He renounced his U.S. citizenship in 2017, a decision he ties to a grandfather who left Czechoslovakia after the Second World War and never got to go back. He now holds multiple second citizenships and pays a personal tax rate of roughly 1%, a figure that appears in show notes and promotional copy for his interviews. His own money sits in a small family office with a conservative tilt: U.S. equities, plus hospitality real estate in Cambodia.
Go Where You’re Treated Best
He credits the five-word line to his father, who told him in the late 1990s that the writing was on the wall for Cleveland and perhaps for the country. The idea is simpler than the branding. No single country is best at everything, so banking, business, taxes, lifestyle, and family life may each point somewhere different. On his own site he’s explicit that the point was never to abandon your home country. It was to be diversified and to choose rather than default.
His sharpest reframe is treating citizenship as an investment you were handed at birth. He has told a podcast host that his worst investment ever was being born with U.S. citizenship, because nobody asked whether he wanted the deal and it came with a lifetime tax bill attached. You don’t have to adopt that framing to see why it’s useful. Once a passport looks like a portfolio position, rebalancing it stops feeling like betrayal.
Flag Theory Before and After Henderson
The lineage matters, because Henderson is a modernizer rather than an originator. Investment writer Harry Schultz proposed a three-flag version in the 1960s, which Nomad Capitalist describes as a second passport, an offshore business, and playgrounds where you spend your time. In the same account, W.G. Hill expanded it to five in the 1980s and 1990s by adding a legal residence and an asset haven. Henderson’s version for the 21st century has seven parts: second citizenship, business, playgrounds, tax residence, asset havens, digital privacy, and a social flag about where your people are. The six flags in this series on the site, citizenship, residency, business base, asset haven, playgrounds, and digital, track his list closely, minus the social flag.
The most useful part of his version is also the least glamorous. He’s blunt that the old fantasy of a numbered account and an address in Monaco is dead. Governments share information now, and the burden of proof sits with you: where you live, where your family sleeps, where your kids go to school, and what tax you’ve paid there. A second passport, he points out, doesn’t switch off an American’s tax obligations. That emphasis on compliance is the best defence against the caricature of flag theory as a fugitive’s escape plan, and it’s the reason his version is worth reading.
The Trifecta and the Rest of the Toolkit
His lifestyle template is the Trifecta. Rather than spending a month or less in each country, which he did early on and outgrew, you choose three bases and spend roughly three months in each, owning or renting a real home in every one. His example set is Malaysia, Georgia, and Colombia, and he describes a modified split of five months, five months, and two months. He owns his homes and leaves them empty while he’s away. He also holds a Montenegrin residence permit, which he describes as a playground flag rather than a tax move: it lets him spend summers where he wants to be.
The philosophy as a whole is summed up in his E-K-G formula, which his book describes as enhancing your lifestyle, keeping more of your money, and growing it by living, investing, banking, and doing business overseas. The growth half leans toward overseas investing, especially emerging-market property, and it’s the part of his material I find most interesting. He describes seeing arbitrage everywhere he travelled: higher bank yields, better property deals, and good health care at a fraction of the price in places like Malaysia. Part of his own family office sits inside that thesis, through the Cambodian hospitality real estate mentioned earlier. Whether that’s foresight or a founder talking his own book is a fair question, but the idea underneath it, that stocks and real estate in other markets can offer things a Canadian portfolio doesn’t, deserves a serious look. If you want the Canadian-investor version of the emerging-market case, I worked through Vietnam on its own terms.
The Media Machine and the Business
This is where he out-executed almost everyone in the space. The book was first published in 2018 as Nomad Capitalist: How to Reclaim Your Freedom with Offshore Bank Accounts, Dual Citizenship, Foreign Companies, and Overseas Investments, and has since been updated in a second edition titled Nomad Capitalist: Reclaim Your Freedom with Offshore Companies, Dual Citizenship, Foreign Banks, and Overseas Investments. Around it sits a YouTube channel that recent interview listings put past one million followers, a podcast, a web series called Live Like a King that tries to show emerging countries as luxurious rather than risky, and an annual conference, Nomad Capitalist Live, where speakers have included investor and author Doug Casey. The firm also publishes the Nomad Passport Index, which scores passports on travel access, taxation, perception, dual citizenship, and personal freedom rather than visa-free access alone. That’s smart content marketing, and it’s also a genuinely useful reference.
Every piece of it leads to the consultancy, which is how the business works. Nomad Capitalist works on an application basis, mostly with six- and seven-figure entrepreneurs and investors, and sells a bespoke “holistic plan” covering tax, residency, citizenship, banking, and structure. The firm doesn’t publish a price list that I could find, and former clients cite fees in the tens of thousands of USD in public reviews. Treat any figure you see as secondhand.
What the Criticism Actually Says
I’m setting aside anonymous forum posts and sites built around personal attacks, some of which are ugly and have nothing to do with whether the service works. The substantive complaints are consistent. Reviewers describe a content-led sales funnel in which fear of government is part of the hook. Some unhappy clients say a plan sold as bespoke read like a reshuffled template. Others say parts of the information were out of date. One book reviewer called the title a marketing tool for the consultancy that skips the downsides of living abroad, and another described it as more motivating than instructive. At least one of the firm’s public replies to a review calls its service unique and holistic. Customer-review pages show a real split. As of October 2026, SmartCustomer averages about 3.4 out of 5 and carries complaints about price, while Trustpilot’s distribution is substantially more positive, at about 4.7 out of 5 from roughly 200 reviews. Both include clients who credit the plan and the team. These are unverified client reviews, so the complaints above remain allegations, not established facts. That split is roughly what you’d expect from a premium service with a sales funnel. It tells you little about whether you are the right client.
There’s one criticism I can support from primary sources, and it matters more to Canadians than the rest. Nomad Capitalist publishes a report for Canadians leaving the country, dated March 2025. It’s a useful orientation in places. But it presents the choice for Canadians as becoming a non-resident for tax purposes or renouncing citizenship, even though its own residency section later says you can become a non-resident without renouncing. For Canadian tax purposes that isn’t a choice. Canada tests residency, so renouncing Canadian citizenship doesn’t end Canadian tax by itself, and ceasing residency doesn’t require giving up the passport. The report also tells readers that the first CAD 100,000 of departure gains is exempt. I can’t find that in the CRA’s guidance on dispositions of property for emigrants, which lists four categories of excluded property and no general exemption amount. Both points are exactly where an American mental model leaks into a Canadian situation. Check the page yourself before relying on my reading, since firms edit their sites.
Where the American Story Stops Working for Canadians
The United States taxes its citizens on worldwide income wherever they live. An American can move abroad, cut every tie, and still file with the IRS every year. Filing is not the same as owing: the foreign earned income exclusion and the foreign tax credit can reduce the U.S. tax actually payable, sometimes to zero. But the filing obligation stays as long as the passport does, so for that person the passport is the tax leash, and renouncing it is the only way to cut it, which is the path Henderson took. Renouncing can also trigger the U.S. expatriation tax if you are a “covered expatriate,” a status that can arise from a high average tax liability or a net worth of USD 2 million or more, but also simply from failing to certify five years of U.S. tax compliance.
Canada doesn’t work that way. We’re taxed on residency, not citizenship. Stop being a Canadian tax resident properly and Canada largely stops taxing your worldwide income, with your passport still in your pocket. That makes the renunciation ritual at the centre of Henderson’s story irrelevant to us. What replaces it is a different and harder set of problems, and his American-built material was never designed to solve them.
The first is residency itself. It’s a facts test, not a form. The CRA looks at your home, your spouse or partner, and your dependants, then at secondary ties like a driver’s licence, a health card, and bank accounts. The residency flag post walks through it. A half departure, with the family and the house still here, leaves you a Canadian resident who now also owes tax somewhere else.
The second is the departure tax. On the day you cease to be a resident, the Income Tax Act treats most of your property as sold at fair market value and taxes the resulting gains, even though you sold nothing. Your Canadian real estate, RRSP, and TFSA are excluded, along with qualifying Canadian business property used through a permanent establishment in Canada and, for people who were Canadian residents for 60 months or less in the 10 years before leaving, property they owned when they last became residents or have inherited since. What gets caught is non-registered portfolios, private company shares, crypto, and foreign property. You can elect to defer payment of the departure tax, generally without interest until you dispose of the property; if you make that election and the federal tax being deferred exceeds CAD 16,500, the CRA generally requires acceptable security. For an employee with a house and full registered accounts, this is mostly paperwork. For a founder or a serious taxable investor, it’s a project that starts years before the move.
The third is what happens to the accounts you keep. The RRSP and TFSA survive departure, but not gracefully. No new annual TFSA room accrues for years spent entirely as a non-resident, contributions made while non-resident generally draw a 1% monthly tax, and your new country may tax income earned inside the account. The TFSA deep dive has the detail.
The fourth is the Trifecta itself. A home available to you in Canada is a primary residential tie, so a Canadian who keeps the house and family here while rotating through three foreign bases is almost certainly still a Canadian tax resident. That makes it a long snowbird season rather than a tax exit. At the other end, each base can create residency of its own once the days add up, which is the accidental-residency trap in the playgrounds flag post. Henderson’s own flag theory page is right to stress that discipline.
Finally, the passport. Canada’s is a strong travel document, and Canada permits dual citizenship, so a second citizenship is pure optionality for us: a Plan B and something to hand your kids, not an escape hatch. Much of the urgency in second-passport marketing is aimed at people from weaker-passport countries or Americans trying to exit the U.S. system, and it doesn’t transfer at full strength.
What I’d Actually Do
I’d treat Henderson as the person who made the question respectable and then do the Canadian homework myself. In order:
- Read the book for the question, not the instructions. It’s inexpensive, and its real value is permission to treat your default arrangement as a choice. I’d skip the renunciation material entirely.
- Use his free research to build a shortlist. The Passport Index and tax map are good for deciding which jurisdictions deserve a closer look, and his overseas investing ideas, in stocks and in real estate, are worth studying as ideas. Anything touching Canadian rules I’d verify against the CRA, because the American framing leaks.
- Map my residential ties and my deemed-disposition exposure on paper before anything else. The residency flag post shows what the CRA counts, and the departure tax post shows what leaving would cost on my actual balance sheet. You can’t plan an exit you haven’t priced.
- Check descent before paying anyone. A second citizenship through ancestry is the best-value version, and the citizenship flag post covers the four routes.
- Get quotes from a Canadian cross-border accountant and an immigration lawyer for the specific country I care about before paying any firm. If the situation is complex enough to need several jurisdictions coordinated, a firm like Henderson’s may earn its fee. If it’s one move to one country, probably not.
- Test the base before committing. A year living in the place beats any spreadsheet, and the expat living guide for Canadians is where I’d start choosing.
Go where you’re treated best is a good question for a Canadian too. The answer just comes with a different tax test and a different bill at the door.
This post is personal documentation of how I think about my own situation. It is not tax, legal, immigration, or financial advice. Residency, citizenship, and departure tax rules are complicated, change often, and apply differently to every case. Confirm anything here with a qualified Canadian cross-border tax professional and, where relevant, an immigration lawyer before you act. Claims attributed to Andrew Henderson and Nomad Capitalist come from their own materials and public interviews and have not been independently verified unless stated.