In 2015, governments approved a two-phase LNG export terminal at Kitimat, British Columbia. Phase 1 exported its first cargo in June 2025. The partners took a final investment decision on Phase 2 on September 28, 2026, eleven years after the original approval. That long interval between initial approval and a commitment to expand illustrates the challenge Ottawa says it is now trying to address: moving major projects from proposal to construction.
The federal answer is the Building Canada Act, passed in June 2025 as part of Bill C-5, and a new body called the Major Projects Office. The office now lists 18 referred projects and 10 broader “transformative strategies,” which it says represent CAD 194 billion of investment and 200,000 jobs. The statute itself uses the phrase “national interest” rather than “national significance,” and the difference is more than wording, because only two projects have actually received the designation.
That is the first thing readers should hold onto. A project can be announced, referred, designated, permitted, financed, built and operated, and each step is a separate event with a separate probability of happening. Canada has extraordinary resources and real industrial capability, and building the infrastructure to use them would widen the country’s economic options. But national importance, commercial success and shareholder returns are three different things. This article tries to keep them apart.
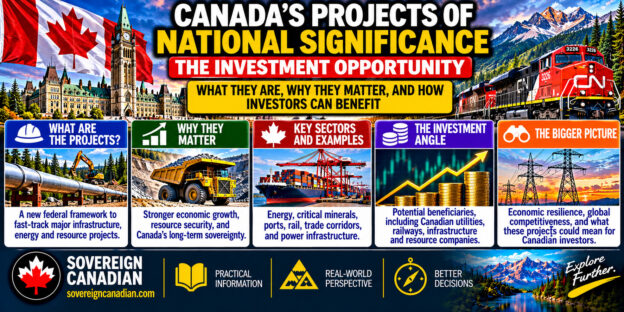
What Are Projects of National Significance?
The Building Canada Act lets cabinet list a project on Schedule 1 as a project of national interest. Before that happens, the Major Projects Office assesses the project against factors in the Act, consults Indigenous peoples, the relevant province and federal departments, and Cabinet publishes a notice in the Canada Gazette. The factors include whether a project strengthens Canada’s autonomy, resilience and security, delivers economic benefits, has a high likelihood of successful execution, advances the interests of Indigenous peoples and contributes to clean growth. Cabinet may also weigh any other factor it considers relevant, which gives it wide discretion.
Listing does not approve construction. It replaces a string of separate federal permits and decisions with a single “conditions document” issued through the Major Projects Office, with certain findings deemed to be made in the project’s favour. The government’s stated goal is a federal review of two years or less. The Act also bars new listings after its fifth anniversary, which falls in June 2030.
The terminology around the process is slippery, so it helps to separate the stages.
| Stage | What it means | Where things stand on November 3, 2026 |
|---|---|---|
| Announced | A government names a project or ambition | Dozens of projects and strategies |
| Referred to the MPO | Ottawa agrees to coordinate and support it | 18 projects, 10 strategies |
| Designated (listed on Schedule 1) | Cabinet declares it in the national interest | Two: Pacific Link (October 1) and Roberts Bank Terminal 2 (October 30) |
| Regulatory approvals | Permits and authorizations in hand | Varies widely; several projects were approved before referral |
| Final investment decision | Owners commit the capital | LNG Canada Phase 2 (Sept 28); Roberts Bank is targeted for mid-2027 |
| Construction | Work underway | Contrecoeur, Matawinie, North Coast Transmission Line Phase 1, Darlington’s first unit |
| Operating | Producing | McIlvenna Bay is ramping up; LNG Canada Phase 1 is exporting |
Two features of this record deserve attention. First, the first listing came roughly 15 months after the Act passed. Second, several of the projects now advancing, including Contrecoeur, Matawinie and the first Darlington unit, were permitted or financed substantially before or alongside referral. The office’s most visible contribution so far looks less like new approvals and more like financing coordination and sequencing.
The framework is also contested. Nine Ontario First Nations filed a constitutional challenge in July 2025 targeting sections 6 and 22 of the Act, the provisions that deem approvals and allow exemptions from other laws. In October 2026, Cold Lake First Nations sought judicial review of the Pacific Link designation in Federal Court, and no court has yet ruled on it. Ottawa says it consulted more than 130 Indigenous communities along the potential routes before listing. Meanwhile Bill C-39, introduced September 21, would create “regions of national interest” and shorten federal review timelines further. It passed second reading on October 8 and was before a House of Commons committee on November 3. It is not law, and its measures remain proposals.
What Is Canada Planning to Build?
The Major Projects Office project list is the best official inventory. The table summarizes it, using each project’s stated figures. Where a figure could not be verified, the cell says so.
| Project | Proponent | Stage | Stated cost |
|---|---|---|---|
| Pacific Link oil pipeline | Alberta; Trans Mountain, Alberta Petroleum Marketing Commission, Pembina | Listed Oct 1, 2026; conditions document targeted Sept 1, 2027 | CAD 35.2 to 43.7 billion (Alberta estimate) |
| LNG Canada Phase 2 | Shell, Petronas, PetroChina, Mitsubishi, KOGAS | Final investment decision Sept 28, 2026 | CAD 33 billion (government figure) |
| Ksi Lisims LNG | Nisga’a Nation, Rockies LNG, Western LNG | Federal and BC approvals Sept 2025; FID not announced | CAD 30 billion plus (with pipeline and power line) |
| Darlington New Nuclear | Ontario Power Generation | First unit under construction | CAD 7.7 billion first unit; CAD 20.9 billion for four |
| North Coast Transmission Line | BC Hydro | Phase 1 construction began Sept 3, 2026 | CAD 3.9 billion committed by Canada and BC to phases 1 and 2 |
| Deep Geological Repository | NWMO | Under consideration for listing; impact assessment ongoing | Not verified |
| Taltson Hydro; Iqaluit hydro | GNWT; Nunavut Nukkiksautiit | Referred | Not verified |
| McIlvenna Bay | Eldorado Gold | First concentrate June 2026, ramping up | Not stated |
| Red Chris expansion | Newmont 70%, Imperial Metals 30% | BC authorizations June 2026; JV decision expected later in 2026 | Canada committing CAD 500 million; capex not verified |
| Crawford nickel | Canada Nickel | Federal decision statement received; financing outstanding | See text |
| Matawinie graphite | Nouveau Monde Graphite | Construction began May 2026 | CAD 1.8 billion |
| Sisson tungsten-molybdenum | Northcliff Resources | Approved federally 2017; construction decision targeted late 2027 | Not verified |
| Roberts Bank Terminal 2 | Vancouver Fraser Port Authority | Listed Oct 30, 2026; FID targeted mid-2027 | CAD 5.9 billion |
| Contrecoeur terminal | Montreal Port Authority | Construction began April 2026 | Not verified; CAD 1.16 billion CIB loan |
| Mackenzie Valley Highway; Grays Bay; Arctic corridor | GNWT; West Kitikmeot; Tlicho, Dene, GNWT | Notice or consultation stage | Not verified |
Energy and pipelines
Pacific Link is the flagship. It would carry one million barrels per day roughly 1,250 kilometres from Bruderheim, Alberta to a deepwater terminal near Delta, mostly along the Trans Mountain corridor. Alberta’s estimate of CAD 35.2 to 43.7 billion is an estimate, not a budget; the route is not final, and no final investment decision has been taken. Trans Mountain, a federal Crown corporation, and Alberta’s marketing commission are expected to own equal shares of everything beyond Pembina’s 10% economic interest through construction, with Pembina able to rise to 20% once the line operates. Indigenous communities are to be offered at least 10% ownership.
LNG Canada Phase 2 is different. It is a private, foreign-owned investment already past its decision point, adding 14 million tonnes per year. Ksi Lisims has binding supply agreements with Uniper and, since October 26, SEFE, plus heads of agreement with Santos and Centrica; the Canadian Press reports binding contracts for 7 of its 12 million tonnes a year of capacity. The partners aim to decide this year, but no final investment decision had been announced by November 3, and signed offtake does not guarantee financing.
Nuclear and electricity
Darlington is the first of four planned small modular reactors, backed by a CAD 3 billion equity commitment from the Canada Growth Fund and the Building Ontario Fund. The North Coast Transmission Line would more than double clean power availability in the northwest and is the enabling infrastructure for Ksi Lisims and the Golden Triangle mines. The Deep Geological Repository is a roughly 175-year commitment funded entirely by nuclear waste owners, and it is not an investment opportunity so much as a precondition for the nuclear industry’s social licence.
Critical minerals and mining
The mining list is the most uneven. McIlvenna Bay is already producing. Matawinie is under construction and supported by a government take-or-pay offtake of 30,000 tonnes a year for seven years. Crawford has its federal decision statement, issued July 31, but not its financing; the federal page cites CAD 5 billion of investment across the mine and downstream refining and steel plans, while company estimates reported elsewhere put initial capital near USD 2 billion, and the two figures are not the same measure. Sisson has been federally approved since 2017 and still has no construction decision.
Ports and transportation
Roberts Bank Terminal 2 would add about 2.4 million containers of annual capacity, roughly 50% more at Canada’s largest port, and listing could move its opening from 2039 to 2035. Contrecoeur would lift Montreal’s container capacity by about 60% and is financed in part by a CAD 1.16 billion repayable Canada Infrastructure Bank loan.
What Could These Projects Mean for Canadians?
The government’s totals are projections, not commitments or guaranteed outcomes, and costs and employment could come in above or below them. The CAD 194 billion figure counts announced project value, most of it private and some of it foreign, and the 200,000 jobs figure carries a footnote that matters: it measures full-time positions during construction, assuming steady capital spending. These are estimated construction positions, not 200,000 permanent jobs. The number employed at any particular time will depend on project schedules and the pace of capital spending.
The individual projects show the pattern. Darlington’s four units are expected to create 18,000 annual jobs during construction and sustain 2,500 in operation. LNG Canada Phase 2 cites about 6,000 direct construction jobs and up to 240 operating jobs across the plant and pipeline. McIlvenna Bay expects about 450 jobs at full production. Construction employment is real and regionally significant, but it ends. The projects that matter most for lasting employment are mines and nuclear plants, and even they employ far fewer people than they build with.
On export diversification, the logic is sound but incomplete. Roughly 90% of Alberta’s oil is sold into the United States, so a tidewater pipeline would give producers a second customer base. Capacity, however, is not demand. A pipeline that exists without committed shippers, or a terminal that exists without buyers, is an underused asset. Ksi Lisims has signed buyers for more than half its planned capacity, which is the model that works. Pacific Link, by the sources reviewed, has not shown the same breadth of commercial commitments yet.
The productivity case is the weakest to prove. Infrastructure raises productivity when it lowers the cost of moving goods and power relative to the cost of building it. Port capacity and transmission lines can do that. A road to a deepwater Arctic port, or a graphite mine that depends on a government offtake, depends on future demand that nobody can guarantee. Ottawa estimates that without Roberts Bank 2, port congestion could add between 800 million and 900 million dollars annually to transportation costs, beginning as early as 2031. That is a government projection, and independent estimates were not located.
The sovereignty argument is real but modest. The objective is not zero trade with the United States. It is the ability to say no, or to sell elsewhere, because the infrastructure exists. Our piece on Canada’s closer relationship with the EU covers the diplomatic side of that diversification. Infrastructure is the physical side.
Fiscal exposure needs its own accounting, because “CAD 194 billion” is not government spending. Pacific Link is largely public: the Crown corporation and Alberta’s marketing commission would own roughly 90% through construction, before any Indigenous equity offering. The Darlington project carries CAD 3 billion in public equity commitments and about CAD 715 million in Indigenous loan guarantees. Matawinie has government loans of CAD 459 million, a CAD 113 million Canada Growth Fund commitment and the take-or-pay offtake. The Canada Infrastructure Bank loan to Contrecoeur is repayable. LNG Canada Phase 2 is private capital, supported by tax measures. Our overview of the Canada Strong Fund covers the federal fund announced in April, a planned Crown corporation seeded with CAD 25 billion over three years to invest alongside private investors. Ordinary investors cannot buy into it today, though Ottawa intends to launch a retail product. When a project is publicly owned, taxpayers carry the cost overruns, and shareholders do not.
Can Canadians Invest in These Projects?
For the largest projects, mostly no. LNG Canada’s owners are Shell, Petronas, PetroChina, Mitsubishi and KOGAS. Ksi Lisims belongs to the Nisga’a Nation and two private partners. Darlington belongs to a provincial Crown corporation, the transmission line to BC Hydro, the ports to port authorities. Indigenous equity programs, which are significant, are not open to retail investors.
What remains is exposure at the edges, and it comes in five forms: direct project owners, contractors, equipment suppliers, infrastructure operators, and diversified funds. The table classifies each by its relationship to the projects. It does not rate the investment.
| Company | Ticker | Project link | Relationship | Stage |
|---|---|---|---|---|
| Pembina Pipeline | TSX: PPL; NYSE: PBA | 10% economic interest in Pacific Link through construction under a non-binding agreement, option on 10% more in operation | Direct, minority | Established |
| TC Energy | TSX, NYSE: TRP | Coastal GasLink Phase 2 | Confirmed, indirect to LNG | Established |
| Fluor | NYSE: FLR | LNG Canada Phase 2 engineering, procurement, fabrication, construction and commissioning (JGC joint venture) | Confirmed contractor | Established |
| Eldorado Gold | TSX: ELD; NYSE: EGO | McIlvenna Bay, 100% | Direct, one asset among several | Producer |
| Imperial Metals | TSX: III | 30% of Red Chris | Direct, minority, partner-operated | Producer |
| Canada Nickel | TSXV: CNC | Crawford, 100% | Direct | Development |
| Nouveau Monde Graphite | TSX: NOU; NYSE: NMG | Matawinie | Direct | Construction, pre-revenue |
| Northcliff Resources | TSX: NCF | 88.5% of Sisson | Direct | Development |
| AtkinsRealis | TSX: ATRL | Darlington SMR engineering | Confirmed contractor | Established |
| Aecon | TSX: ARE | Darlington SMR construction; Contrecoeur in-water works | Confirmed contractor | Established |
| BWX Technologies | NYSE: BWXT | Darlington reactor pressure vessel | Confirmed supplier | Established |
| Finning, Toromont, Wajax | TSX: FTT, TIH, WJX | Regional equipment dealers | Speculative | Established |
| CN, CPKC | TSX: CNR, CP | No project-specific link verified | Indirect | Established |
Two clarifications are worth making here. Foran Mining, the name most often attached to McIlvenna Bay, has been absorbed by Eldorado Gold, which completed the acquisition in April 2026. Exposure to the mine now means buying Eldorado, where it sits next to a Greek development project and operating gold mines. And Pembina, the listed name most associated with Pacific Link, is contributing development and execution expertise under an agreement it described in July as non-binding, and it keeps full discretion over its own final investment decision. Everything beyond its stake is expected to sit with two public owners, subject to the Indigenous ownership offer.
Developers. These offer the most direct exposure and the most risk. Canada Nickel’s market value, about CAD 375 million in early September, sits next to a project whose initial capital is measured in billions. Its full financing package is targeted for the first quarter of 2027, and it has relied on a USD 32 million bridge loan and a CAD 21 million placement in the meantime. Nouveau Monde’s share count roughly doubled, from about 152 million in 2025 to about 329 million after its 2026 financing, which is what financing a mine looks like from a shareholder’s side. Northcliff’s controlling shareholder held more than 81% of the company in 2025, leaving a thin free float. Dilution is not a side effect of mine development. It is the cost.
Contractors and suppliers. AtkinsRealis holds an engineering execution contract of about CAD 450 million at Darlington, and Aecon leads the partnership building the first unit, with a share of about CAD 1.3 billion. Aecon is also, alongside Pomerleau, doing the in-water works at Contrecoeur. Those are documented. So is the largest contract tied to any of these projects: on September 29, Fluor announced that its joint venture with JGC was selected to build LNG Canada Phase 2, with Fluor’s share valued at about USD 7.5 billion. Fluor is listed in New York, so Canadians would buy it in U.S. dollars. A contract value is not a profit, and the release does not say whether the work is reimbursable or lump-sum, which decides who absorbs cost overruns. It is a confirmed relationship, not evidence of an attractive return. Finning, Toromont and Wajax sell and service heavy equipment in regions where mines, pipelines and ports are planned, and aftermarket parts and service can recur for decades, but this research did not find confirmed orders tied to these projects, and Canadian projects may be small against their global operations. Treat them as plausible, not proven. Our earlier electrification piece covers the equipment and grid side in more depth.
Railways and energy. None of the listed project pages names a railway. Roberts Bank and Contrecoeur are rail-connected ports, but which carrier captures which flows was not verified, and the two railways should not be assumed to benefit equally; our CN versus CPKC comparison covers their different exposures. Among energy names, TC Energy has confirmed Coastal GasLink Phase 2 work, and it says the commercial structure limits its construction-cost exposure. Enbridge has no verified role in these projects; for that business, see our Enbridge analysis. Cameco is an indirect beneficiary of nuclear demand in general, not a documented supplier to Darlington.
Funds. I did not find a Canadian-listed ETF built around these projects. The closest candidates are sector funds, and their holdings differ from what the headlines suggest. XEG, the iShares energy ETF, charges a 0.55% management fee and is dominated by producers such as Canadian Natural, Suncor and Cenovus, not pipeline builders. Global X’s equal-weight pipeline ETF, PPLN, held Keyera, TC Energy, Enbridge and Pembina at roughly 20% each in mid-2026, with a 0.74% fee, so it carries indirect exposure to Pacific Link and Coastal GasLink through just a few names. HURA, the Global X uranium ETF, charges 0.75% and held Cameco at about 21% in early 2026, with most of the rest in global uranium names. Global X’s PAVE, launched in April 2026, holds U.S. infrastructure companies and gives no exposure to Canadian projects at all. Our comparison of ETFs, mutual funds and individual stocks explains how to weigh these trade-offs.
Investment Opportunities Versus Investment Risks
A good project, a good company and a good investment at today’s price are three separate claims. Pacific Link may be a strategically valuable pipeline, but its economics accrue mostly to Crown owners. LNG Canada Phase 2 is a good project whose profits go largely to foreign owners. Pembina illustrates the third claim. Whether its shares offer an adequate return depends on the price paid, not on the strategic merits of the pipeline. The 9.5% annual return hurdle used here for screening shows what a price asks. As a simplified illustration, a stock yielding approximately 4% would require roughly 5.5% annual share-price appreciation to approach a 9.5% total return. Actual compounded returns would depend on dividend growth, reinvestment and the price paid relative to future earnings and cash flows. That is arithmetic about a hypothetical stock, not a forecast for Pembina.
Compounding at 9.5% over ten years means turning each dollar into about 2.5 dollars. For an established operator with dividends and earnings, that hurdle can be tested against reported cash flows. For development-stage companies with no revenue, it cannot. Crawford, Sisson and Matawinie have no cash flows to discount until financing closes and construction finishes, and assigning a price target to them would mean inventing inputs. The honest answer for these names is that a credible valuation cannot be built yet. That is itself useful information, because it tells you the position is a venture bet, and sizing should follow.
Pembina also shows how financing works at scale, and how much is still undecided. Its 10% is an economic interest, and the sources reviewed do not say whether that means a matching share of construction capital, or how much would be funded with project debt or guarantees. Pembina said in July that it will commit no development capital before a final investment decision, which is its own to make. Its eventual exposure depends on a financing structure that has not been finalized, and for a project estimated at tens of billions of dollars the terms matter more than the headline percentage.
The risks cluster in four places. Regulatory and legal risk comes from consultation and the challenges now before the courts. Financial risk comes from cost overruns, financing costs, dilution and public guarantees. Commercial risk includes commodity prices, competing suppliers, underused capacity and technology change; the first LNG Canada phase has faced equipment problems of its own. Political risk includes the fate of Bill C-39, a change of government and trade disputes. These risks do not make the projects uneconomic, and Indigenous and environmental objections are not, by themselves, reasons a project fails commercially. They are reasons the timeline and the cost may differ from the announcement, and that matters to anyone paying today’s price for a future cash flow.
The Bigger Picture: Canadian Economic Sovereignty
A country that can extract and process its resources, generate dependable power and ship to more than one buyer has more economic options than one that cannot. That is the strongest version of the government’s case, and it holds up better than the jobs and GDP totals do. Building a second route to tidewater does not end trade with the United States. It changes the negotiating position.
But infrastructure sovereignty and personal financial sovereignty are not the same thing. The Toronto Stock Exchange already leans heavily on energy, materials and financials. Buying more Canadian resource developers adds to a concentration many Canadian households already carry through their jobs, homes and index funds. A person whose income depends on Alberta oil, whose house is in Calgary and who adds Pembina to the portfolio has not diversified. Our overview of investing in global markets from Canada lays out the alternative.
Conclusion
The Major Projects Office has not yet shown that it can deliver projects that would not have been delivered otherwise. Its record so far is two designations in fifteen months, one final investment decision on a project approved eleven years earlier, and a set of projects that were already moving. That is an assessment of the evidence available so far. What would have happened without the office cannot be observed, so it is not proof that the office has produced no benefit. The assessment may change as the Federal Court challenges are resolved, Bill C-39 is amended or passed, and projects reach their next milestones.
The useful signals are specific and datable: the Pacific Link conditions document, due by September 1, 2027; the Roberts Bank final investment decision, targeted for mid-2027; Canada Nickel’s financing package, targeted for the first quarter of 2027; the Red Chris joint venture decision, expected later in 2026; and the Federal Court rulings. Each of those either moves a project forward or it does not. Press releases do not count.
For an investor, the discipline is the same one that applies everywhere else. Own what you understand, at a price that leaves room for error, in a size that survives being wrong. A country can build well and still leave its shareholders with a mediocre return, and a flawed project can still reward someone who bought it cheaply. What separates those outcomes is price, position size and patience, and none of them appears in an announcement.
This article is general information, not personalized investment, tax or legal advice. The author is not a registered advisor, and any market data cited may be out of date. Verify figures with primary sources and consult a licensed professional before acting.