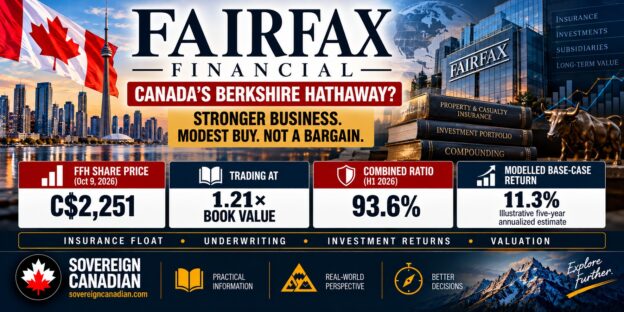
Prem Watsa has been called Canada’s Warren Buffett for so long that the label has become part of Fairfax Financial’s identity. The comparison isn’t careless. Both men built holding companies around property-and-casualty insurance, used the premiums their insurers collect to fund long-term investing, wrote candid annual letters, and judged themselves by growth in book value per share over decades. By Fairfax’s own accounting, book value per share has compounded at 18.7% a year since 1985, including dividends. Few Canadian companies can point to anything like that.
The record isn’t a straight line, though. Fairfax compounded spectacularly in the 1980s and 1990s, made a fortune on credit-default swaps in 2007 and 2008, and then spent most of 2011 to 2020 growing book value at roughly 2.4% a year while hedging a market that kept rising. From 2021 to 2025 book value per share compounded at 22.5% a year, the combined ratio fell below 94%, and the stock went from about 0.7 times book value (end of 2020) to about 1.5 times (end of 2025).
That recovery changes the question. Whether Watsa can repair Fairfax has been answered. What remains is whether the repaired Fairfax can earn enough on its equity to justify about 1.2 times book value. My answer is that it probably can, with a margin of safety thin enough that I’d call the stock a modest buy rather than a bargain.
Continue reading