Tag Archives: Financial

Investing in global stock markets from Canada, featuring international markets in North America, Europe, Asia and emerging economies, with a Canadian flag and world map.

Investing Directly in Global Stock Markets: A Canadian Investor’s Guide

A Canadian investor can buy Royal Bank, Apple or an S&P 500 ETF in a few clicks. An online brokerage makes it feel as though every listed company is available. It isn’t. If the company you want trades mainly in Zurich, Tokyo, London or Frankfurt, you may find a US ADR, an OTC quotation, a secondary listing or no North American line at all. Direct access to the foreign exchange opens up more companies, along with a longer list of complications.

This is the last of four articles on how stock markets work. TSX vs NYSE vs Nasdaq covered where stocks trade, S&P 500 vs Nasdaq vs Dow Jones vs TSX covered what indices measure, and OTC Stocks, ADRs and Pink Sheets covered depositary receipts. This one covers buying ordinary shares on the foreign exchange itself.

Continue reading →
OTC stocks, ADRs and Pink Sheets guide for Canadian investors covering OTC market tiers, foreign depositary receipts, RRSP and TFSA eligibility, liquidity and trading risks.

OTC Stocks, ADRs and Pink Sheets: What Canadian Investors Need to Know

Most Canadians who own foreign stocks never think about where the shares actually trade. The ticker shows up in the app, the price looks fine and the order goes through. Then the spread is wider than expected, or a TFSA purchase gets flagged, or a dividend arrives smaller than announced. In each case the problem wasn’t the business. It was the security, and how it trades.

Not Every Stock Trades on a Major Exchange

Not every stock worth owning trades on the NYSE, Nasdaq or TSX. Nestlé, one of the world’s largest food companies, is listed in Switzerland, and its US line is quoted over the counter. Plenty of speculative microcaps trade in the same general market. Those are very different situations.

Continue reading →
Stock market indices comparison for Canadian investors featuring the S&P 500, Nasdaq, Dow Jones and S&P/TSX Composite, with Canadian and American financial markets.

S&P 500 vs Nasdaq vs Dow Jones vs TSX: Understanding Stock Market Indices

Financial headlines tell you the Dow gained 300 points, the Nasdaq fell 2%, the S&P 500 hit another record and the TSX outperformed Wall Street. Each sentence describes a different group of companies, counted by different rules. A 300-point move in the Dow isn’t comparable with a 300-point move in the S&P 500. A rising Nasdaq-100 doesn’t mean the average American stock is doing well. A strong TSX doesn’t mean Canada’s economy is beating the United States.

Stock market indices are how we summarize markets, and index funds are how most of us own them. When you buy an index ETF, you’re buying a methodology: which companies, in what proportions, measured in which currency. This is the second article in the Understanding Stock Markets series. It covers what the major benchmarks measure, why they diverge and what that means for a Canadian portfolio.

Continue reading →
TSX vs NYSE vs Nasdaq comparison for Canadian investors, featuring the Toronto and New York stock exchanges, trading currencies and key differences.

TSX vs NYSE vs Nasdaq: A Canadian Investor’s Guide to Stock Exchanges

From a single self-directed brokerage account, a Canadian can buy Royal Bank, Berkshire Hathaway, Microsoft, Shopify or a small mining company in the same afternoon. Those securities sit on different exchanges, meet different listing standards and, in some cases, trade in different currencies. The investor sees a ticker and a buy button. Behind it sits a market structure most people never look at.

For the large, liquid companies that fill most portfolios, that structure matters less than most explainers imply. It isn’t irrelevant, though. Canadian stock exchanges and their American counterparts differ in which companies they list, how easily shares change hands, which currency a trade settles in and how much disclosure you can count on. This is the first article in a four-part series, Understanding Stock Markets. It covers where your stock is listed, what separates the major North American exchanges, and which differences deserve your attention.

Continue reading →
TFSA deep dive for Canadians covering contribution limits, tax-free investment growth, withdrawals, investment options, common mistakes and advanced strategies.

TFSA Deep Dive: The Sovereign Canadian Guide

The Tax-Free Savings Account is the most quietly powerful account most Canadians own, and also the most misunderstood. Its name undersells it. People hear “savings account” and picture a place to park an emergency fund at 2% interest, when in fact it is one of the few tools in the Canadian system capable of sheltering a lifetime of investment growth from tax entirely.

This is a working guide to using it well. We will cover what the account actually is, how contribution room is built and rebuilt, where people get into trouble with the Canada Revenue Agency, and the strategic questions that matter most: TFSA versus RRSP, asset location, early retirement withdrawals, estate planning, and what happens if you leave the country. The goal is not to celebrate the account, but to help you treat it as what it is — a long-term pool of independently controlled, tax-free capital.

Continue reading →
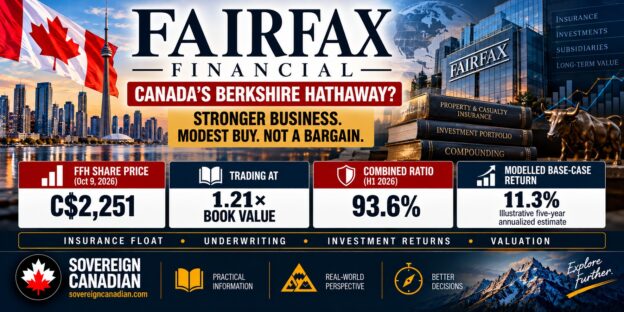
Fairfax Financial stock analysis comparing share price, price-to-book valuation, insurance combined ratio and projected investment returns.

Fairfax Financial Stock: Is Canada’s Berkshire Hathaway Still a Good Investment?

Prem Watsa has been called Canada’s Warren Buffett for so long that the label has become part of Fairfax Financial’s identity. The comparison isn’t careless. Both men built holding companies around property-and-casualty insurance, used the premiums their insurers collect to fund long-term investing, wrote candid annual letters, and judged themselves by growth in book value per share over decades. By Fairfax’s own accounting, book value per share has compounded at 18.7% a year since 1985, including dividends. Few Canadian companies can point to anything like that.

The record isn’t a straight line, though. Fairfax compounded spectacularly in the 1980s and 1990s, made a fortune on credit-default swaps in 2007 and 2008, and then spent most of 2011 to 2020 growing book value at roughly 2.4% a year while hedging a market that kept rising. From 2021 to 2025 book value per share compounded at 22.5% a year, the combined ratio fell below 94%, and the stock went from about 0.7 times book value (end of 2020) to about 1.5 times (end of 2025).

That recovery changes the question. Whether Watsa can repair Fairfax has been answered. What remains is whether the repaired Fairfax can earn enough on its equity to justify about 1.2 times book value. My answer is that it probably can, with a margin of safety thin enough that I’d call the stock a modest buy rather than a bargain.

Continue reading →
Cottage Airbnb first summer results showing rental revenue, occupancy, operating costs, profitability, challenges and lessons learned

Our First Summer Renting a Cottage on Airbnb: $21,375 in Revenue and What We Learned

Earlier this year, I wrote about our experience after the first month of renting our cottage in Port Franks, Ontario. At that point, we had only a handful of bookings behind us. We were still figuring out pricing, cleaning, minimum stays, guest expectations and whether the entire idea of combining a family cottage with a short-term rental actually made sense.

Now the first summer is over.

We deliberately approached 2026 differently than someone buying a cottage primarily for personal use. Our objective for the first year was to establish the property as a rental, build reviews and generate as much revenue as reasonably possible. We didn’t spend a single night there recreationally as a family during the rental season.

The result was just over $21,000 in rental revenue, 75 nights booked through Airbnb, and a much better understanding of both the potential and limitations of trying to make a cottage help pay for itself.

This is what our first full season actually looked like.

Continue reading →
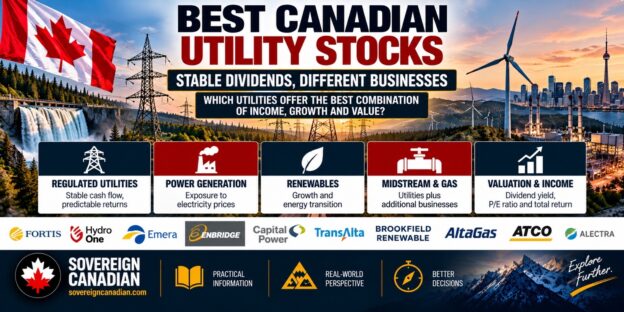
Best Canadian utility stocks comparing Fortis, Hydro One, Emera, Enbridge, Capital Power, TransAlta, Brookfield Renewable, AltaGas, ATCO and Algonquin

Best Canadian Utility Stocks: Fortis vs Hydro One, Emera, Enbridge and Six More Compared

Canadian utility stocks usually get filed under a single heading, boring dividend investments, and that heading hides more than it reveals. Owning Hydro One means owning an Ontario transmission and distribution monopoly with no power plants and one regulator. Owning Fortis means owning a collection of regulated utilities spread across Canada and the United States, with most of the assets south of the border. Owning Capital Power or TransAlta means accepting real exposure to the price of electricity. Brookfield Renewable is a global renewable investment platform that happens to pay a distribution. AltaGas is partly a regulated gas utility and partly a midstream and propane export business. Enbridge, which most Canadians would include on any list of dependable dividend payers, is not really a utility at all.

Continue reading →
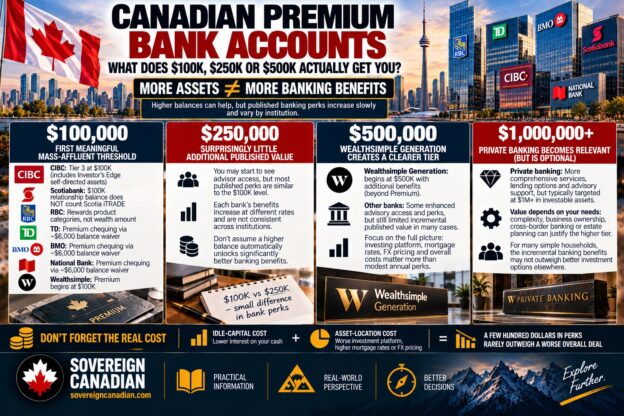
Canadian premium bank accounts comparing benefits at $100,000, $250,000, $500,000 and $1 million in assets

Canadian Premium Bank Accounts: What Do You Actually Get for Keeping $100,000, $250,000 or $500,000 at One Bank?

Once you have accumulated real money, you might expect your bank to start treating you differently. If you have $100,000, $250,000 or $500,000 spread across an RRSP, a TFSA and a taxable account, surely handing all of it to one institution must buy something. I wanted to know what.

I do not mean private banking, and I do not mean someone with a family office. I mean the much larger group of Canadians who have built a few hundred thousand dollars of investments, own a house with a mortgage or a HELOC, carry a premium credit card, and keep financial accounts scattered across several institutions because that is how they accumulated. For that household, the question is practical: does giving one bank more of my financial life actually pay?

Continue reading →
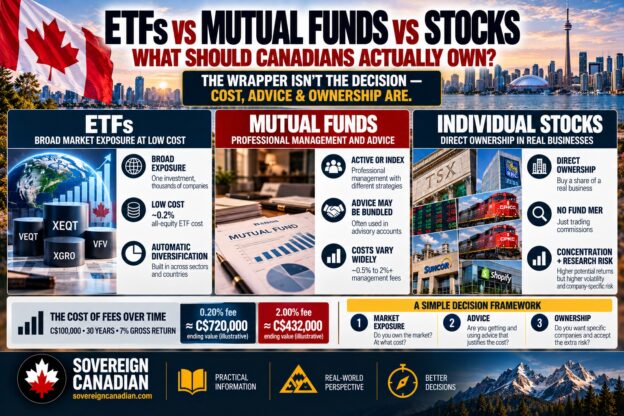
ETFs versus mutual funds versus individual stocks in Canada comparing costs, diversification, advice and direct ownership

ETFs vs Mutual Funds vs Individual Stocks: What Should Canadians Actually Own?

A Canadian who has been investing for fifteen or twenty years and logs into every account at once will often discover that they own all three categories already. There is a balanced mutual fund at the bank, opened when an adviser suggested it and never revisited. There is a one-ticket ETF of the XEQT or VEQT variety, accumulated in the TFSA more recently and with considerably more conviction. And in the non-registered account there are the holdings someone chose on purpose: a Canadian bank or two, Enbridge, CN or CPKC, Brookfield, perhaps Berkshire Hathaway. Each came from a different decision, made at a different time, for a different reason, and most of them have never been compared with each other on any common basis.

The question that follows from that picture is not “which investment type is best?” That framing invites a tournament, and tournaments produce slogans. The more useful question is what job each holding is doing, what it costs, and whether it is earning its place. I own funds, ETFs and individual companies myself, and the purpose of this exercise is not to defend one camp. It is to work out which parts of a portfolio deserve to be paid for, which deserve to be owned directly, and which are simply inherited habits.

Continue reading →