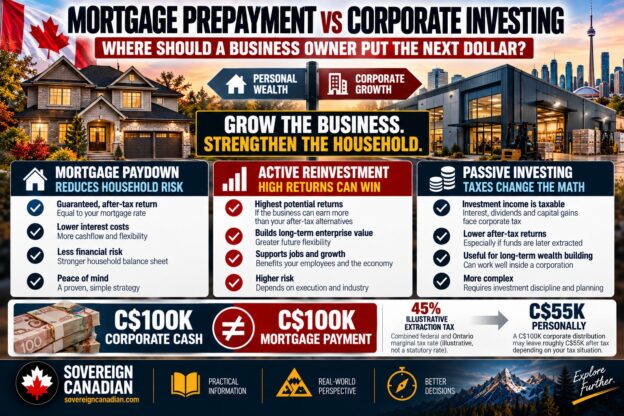
The previous articles in this series compared mortgage prepayment with a TFSA, RRSP, non-registered investing and an RESP. Corporate investing is a different problem because the money may not start on the personal side of the balance sheet at all.
Suppose I own a profitable Canadian corporation. The company earns more than I currently need to fund its operations or my lifestyle, and I still have a mortgage on my house. I could retain the money inside the corporate structure and use it to grow the operating business, fund an acquisition or build an investment portfolio. Alternatively, I could extract additional money personally, pay whatever tax applies to that extraction, and use the remainder to reduce my mortgage.
Continue reading