Tag Archives: Financial

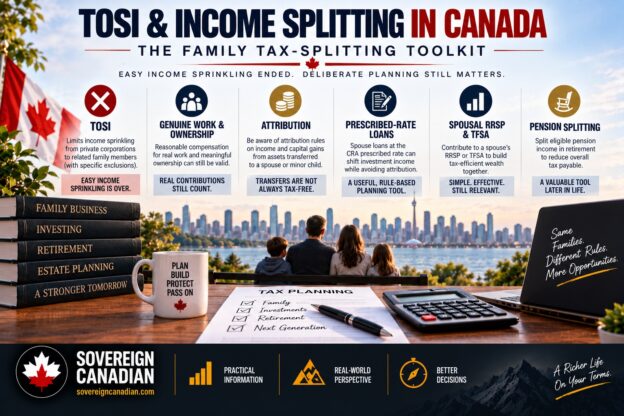
TOSI and income splitting in Canada showing family tax planning strategies for business owners, couples and retirees

TOSI and Income Splitting: The Family Tax-Splitting Toolkit

Ask any Canadian business owner what happened to income splitting and you will get the same answer: TOSI killed it. Before 2018, a private corporation could pay dividends to a spouse who did nothing, to adult children away at school, to whoever in the family sat in the lowest tax bracket that year. Then the rules changed, and the general understanding is that this entire category of planning simply stopped working.

That understanding is half right, which is the most dangerous kind of half right. What actually happened is narrower and more interesting than “income splitting is dead.” The Tax on Split Income did shut down one specific manoeuvre: paying private-company income to family members whose only qualification was being related to the person who owned the business. That manoeuvre is genuinely closed. But it was never the whole of income splitting, and treating it as though it were has left a lot of Canadian households ignoring a real, current, and in some cases newly attractive set of tools, while continuing to half-remember advice that stopped being true eight years ago.

Continue reading →
Multi-generational wealth in Canada showing capital and opportunity being passed from one generation to the next

Multi-Generational Wealth in Canada: How Do You Actually Build Wealth That Survives Generations?

CIBC has cited estimates that roughly a trillion CAD will change hands between Canadian generations from 2024 through 2026, the largest transfer of its kind in the country’s history. Statistics Canada reports that the average size of a monetary gift to first-time home buyers rose 73% to $115,000 between 2019 and 2024. Nearly a third of first-time home buyers are now getting help from family to close the deal, up from a fifth in 2019. Whatever else is true about the Canadian economy right now, this is happening, and it is happening at a scale that will shape who owns what in this country for the next generation. It is worth noting, for reasons that will become clear a few sections from now, that some of CIBC’s own wealth commentary on this transfer repeats the claim that seventy percent of family wealth disappears by the second generation. It is a small, useful demonstration of how far that number has travelled, and how little scrutiny it has received along the way.

Continue reading →
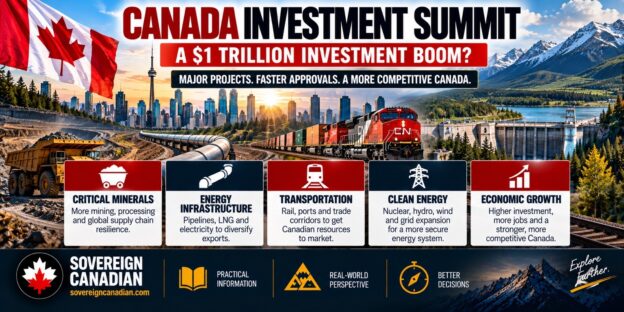
Canada Investment Summit infographic showing a proposed $1 trillion investment boom in critical minerals, energy infrastructure, transportation and clean energy

Canada’s $1 Trillion Investment Boom: What the Investment Summit Actually Means for Canadians

Canada just held its first national investment summit, and if you read the headlines coming out of Toronto, the numbers are extraordinary.

Nearly $500 billion in new investment commitments. More than $100 trillion of assets represented in the room. A $50 billion Canadian infrastructure fund. A $52.5 billion AI infrastructure project in Saskatchewan. Hundreds of billions of dollars of bank financing. And behind all of it, the federal government’s much larger ambition to catalyse $1 trillion of investment in Canada over five years.

Those are numbers large enough to make almost anything sound transformational.

They are also numbers that require some unpacking.

Continue reading →
Living in Cambodia as a Canadian with Angkor Wat, Canadian passport and Cambodian tropical landscape

Living in Cambodia as a Canadian

Cambodia has never been on my radar. I have looked seriously at Thailand, Malaysia, Vietnam, Indonesia, the Philippines, and Singapore. Cambodia never made the list, and I never asked myself why not. That omission is the actual starting point for this piece, because an omission that goes unexamined for years is either a very good instinct or a very lazy one, and I wanted to find out which.

The honest answer, after several weeks of research, is that it is a bit of both. Cambodia has real, documented reasons an affluent Canadian would rationally rank it behind Thailand and Malaysia for almost every serious use case. It also has a genuine, underrated case as a place to watch, and in a couple of narrow respects, a place to use right now. What it does not have is the thing that would justify treating it as a final answer rather than a chapter.

Continue reading →
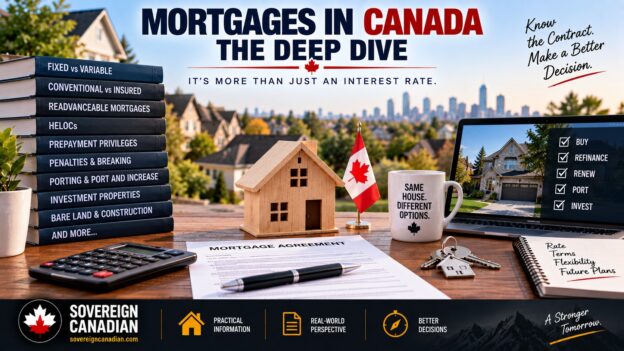
Mortgages in Canada deep dive covering fixed and variable rates, penalties, HELOCs, porting, refinancing and prepayment privileges

Mortgages in Canada: The Deep Dive

I want to start with the sentence this entire article is built around. The mortgage with the lowest rate is not necessarily the cheapest mortgage.

Most Canadians shop for a mortgage the way they shop for a toaster. They compare a number on a rate sheet, pick the smaller one, and sign. Then, three years later, life happens. They get a job in another city. They have a third kid and need a bigger house. Their marriage ends. They get an inheritance and want to pay down a chunk of principal. They want to buy a rental property. And in that moment, the mortgage they picked because it was 0.10 percent cheaper than the alternative turns out to be a contract that punishes them for doing the ordinary things people do with their lives.

Continue reading →
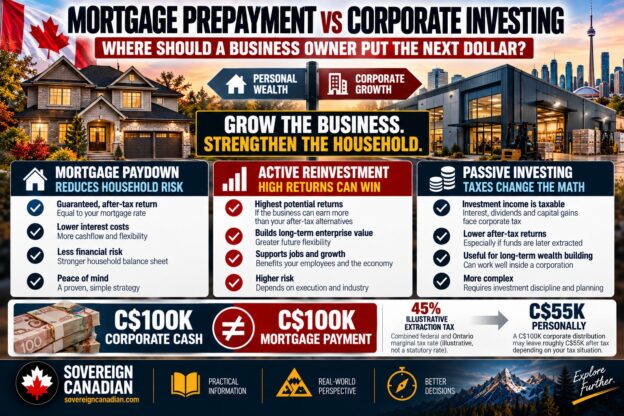
Mortgage prepayment versus corporate investing in Canada comparing household debt reduction, business reinvestment, passive investing and corporate taxes.

Mortgage Prepayment vs Corporate Investing: Should a Business Owner Leave Money in the Company or Pay Down the House?

The previous articles in this series compared mortgage prepayment with a TFSA, RRSP, non-registered investing and an RESP. Corporate investing is a different problem because the money may not start on the personal side of the balance sheet at all.

Suppose I own a profitable Canadian corporation. The company earns more than I currently need to fund its operations or my lifestyle, and I still have a mortgage on my house. I could retain the money inside the corporate structure and use it to grow the operating business, fund an acquisition or build an investment portfolio. Alternatively, I could extract additional money personally, pay whatever tax applies to that extraction, and use the remainder to reduce my mortgage.

Continue reading →
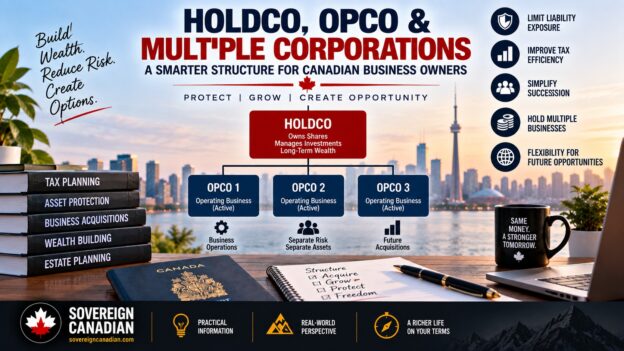
Canadian HoldCo and OpCo structure showing a holding company owning multiple separate operating corporations

HoldCo, OpCo & Multiple Corporations: When Does a Canadian Business Need More Than One Company?

I do not own an incorporated business yet. That is actually one of the reasons I have been thinking about corporate structure now rather than after the fact.

If I acquire a business, the first question is relatively straightforward: what corporation buys and operates it? The more interesting question comes next. What happens if that business succeeds, starts accumulating cash, and I eventually want to buy another one? Does the first corporation buy the second business? Do I own two corporations personally? Should there be a holding company above both? Where should accumulated cash and investments sit? And if one of the businesses gets sued, how much of everything else have I unnecessarily exposed?

Continue reading →
Mortgage prepayment versus RESP in Canada comparing debt reduction with education savings and CESG grants

Mortgage Prepayment vs RESP: Should You Pay Down the Mortgage or Save for Your Kids?

The previous articles in this series compared mortgage prepayment with investing inside a TFSA, an RRSP, and a non-registered investment account. The RESP creates a different decision because there are really two RESP comparisons hiding inside the same account.

The first is whether I should contribute enough to receive the available Canada Education Savings Grant or put that money against the mortgage instead. The second is what I should do after I have already captured the grant. Should another dollar go into the RESP without receiving any additional CESG, into my TFSA if I still have room, or against the mortgage?

Continue reading →
Mortgage prepayment versus non-registered investing in Canada comparing debt reduction with taxable investment returns

Mortgage Prepayment vs Non-Registered Investing: Where Should a Canadian Put Their Extra Money?

The first two articles in this series compared mortgage prepayment with investing inside a TFSA and an RRSP. The TFSA comparison was relatively clean because both sides could be considered largely on an after-tax basis: paying down a non-deductible mortgage avoids an after-tax borrowing cost, while investment growth inside a TFSA is generally tax-free. The RRSP complicated the comparison because the contribution can generate a valuable tax deduction today while withdrawals become taxable income later.

Non-registered investing creates a third version of the same decision, and in some ways it is the hardest one.

Continue reading →
Living in Singapore as a Canadian with Marina Bay skyline, Singapore flag and Canadian passport

Living in Singapore as a Canadian: Excellence Without Access

Every country in this series so far has sold some version of the same trade. You get access, and you give up certainty. Thailand lets you stay for years on a chain of visas that never quite becomes permanence. Vietnam gives you presence without the paperwork to make it stick. Malaysia formalizes the temporariness so cleanly that it becomes its own kind of stability. The Philippines hands out durable permission but keeps dependability conditional. Indonesia is the purest version of the trade: extraordinary attachment to a place, with almost no institutional tenure underneath it.

Singapore does something none of the other five do. It does not ask you to trade certainty for access. It gives you the certainty, in full, and then makes access the scarce resource instead.

Continue reading →