Tag Archives: Financial

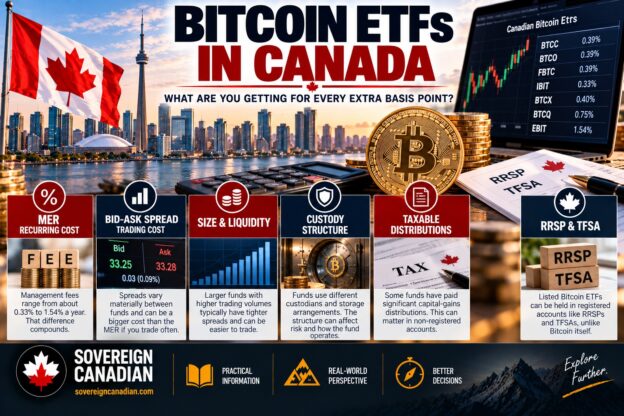
Bitcoin ETFs in Canada comparing MERs, bid-ask spreads, liquidity, custody, taxable distributions and registered accounts

Bitcoin ETFs in Canada: Which One Should You Actually Buy?

A Canadian can buy a Bitcoin ETF that costs about 0.33% a year, or one that costs more than 1.5%. Either way, the investor ends up with exposure to the same Bitcoin. On CAD 100,000, that is roughly CAD 330 a year versus CAD 1,540 a year, before any compounding.

So what is the more expensive fund doing for the extra money?

The answer is more nuanced than “buy the cheapest one.” The annual fee recurs, but bid-ask spreads are paid when you trade. Custody structures differ. In a taxable account, some of these funds have paid out large capital-gains distributions. And Canadians are not limited to Canadian-listed funds, even inside an RRSP or TFSA.

This article assumes you have already decided you want Bitcoin through an ETF. It does not argue for or against owning Bitcoin. Figures are dated throughout because they come from different measurement periods and are not simultaneous quotes.

Continue reading →
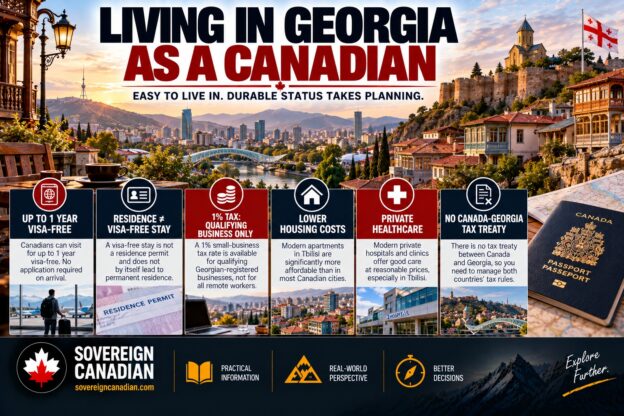
Living in Georgia as a Canadian with Tbilisi skyline, Georgian flag and Canadian passport highlighting visa-free stays, residence and taxes

Living in Georgia as a Canadian: Is Georgia Actually a Good Place to Live?

Picture a 35-year-old Canadian consultant who lands in Tbilisi with a laptop and a one-way ticket. Canadians can stay in Georgia visa-free for a year, so there is no application to file at the airport. The consultant rents a modern apartment in Saburtalo, signs up for fibre internet, learns the Metro and the Bolt app, and keeps working for Canadian and American clients exactly as before. Within a few weeks there is a favourite cafe, a gym, a bank card and a routine. By any ordinary measure, this person has moved to Georgia.

Legally, something quieter has happened. The visa-free stay is not a residence permit. Nothing about it starts the clock that eventually leads to permanent residence. The consultant’s Georgian life can look far more permanent than their Georgian status is, and, separately, nothing in that arrival has told the Canada Revenue Agency that this person stopped being a Canadian tax resident.

Continue reading →
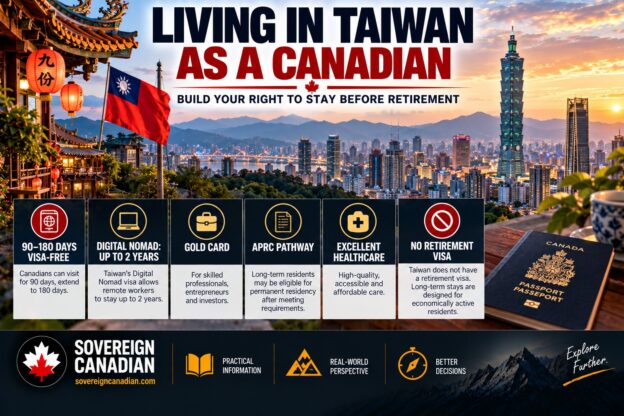
Living in Taiwan as a Canadian with Taipei skyline, Taiwan flag and Canadian passport highlighting Gold Card and permanent residency pathways

Living in Taiwan as a Canadian: Is Taiwan Actually a Good Place to Live?

Picture two Canadians who both decide, at different points in their lives, that they want to retire in Taiwan.

The first moves at 45. She’s a product manager clearing a strong salary, and Taiwan’s Employment Gold Card lets her get a resident permit without a Taiwanese employer sponsoring her. She spends the next several years actually living there — building a career, paying Taiwanese tax, learning the neighbourhoods — and eventually converts that residency into permanent status. By the time she’s ready to slow down, Taiwan isn’t a retirement plan. It’s just where she lives.

The second Canadian spends his career in Canada, retires comfortably at 65, and only then decides Taiwan looks like exactly the kind of place he’d like to spend his later years — safe, walkable, cheap food, excellent hospitals, a short flight from the rest of Asia. He has the same net worth as the first Canadian. Possibly more.

Taiwan’s immigration system treats these two people completely differently. The first one built her right to be there while she still had something Taiwan’s system was designed to reward: an income, a skill set, an employer relationship, a professional category. The second one shows up with money and time and discovers that neither, on its own, is a currency Taiwan’s immigration architecture accepts.

Continue reading →
Snowbird versus full relocation for Canadian retirees comparing tax residence, RRSP and RRIF treatment, pension splitting, OAS, healthcare and foreign taxes

Snowbird vs Full Relocation: Should Canadian Retirees Actually Leave Canada?

A CAD 400,000 gap in how Canada taxes a RRIF at death looks like the whole answer, until you ask how much of that RRIF you will actually have left, and where you will genuinely be living when it matters.

Picture two Ontario retirees who started in nearly identical positions. Both retired at 55 with a RRSP worth about CAD 1.5 million. Both are now in their late eighties, widowed, with no spouse left to roll a RRIF over to. One still lives in Ontario. The other genuinely moved away years ago and has been a non-resident of Canada ever since.

If each of them dies this year with a CAD 1.5 million RRIF still sitting there, the Canadian tax difference between them can be roughly CAD 400,000. The resident’s RRIF is generally included in income on the final return, pushing much of a large balance into Canada’s highest marginal tax brackets. For a genuinely non-resident annuitant, the best-supported Canadian treatment is instead a deemed RRIF payment subject to Part XIII withholding, normally at 25 percent.

Continue reading →
Private REITs and real estate syndicates in Canada comparing illiquid private investments with publicly traded REITs

Private REITs and Real Estate Syndicates in Canada: Are the Higher Yields Worth Giving Up Liquidity?

Say you have $100,000 to invest.

Option one: you buy $100,000 of a Canadian REIT ETF. Tomorrow morning you can check what it is worth. If the bond market has a bad week, you might open your account and see $85,000. You will not like that number, but you will know it, and you can hit sell before lunch if you want to.

Option two: you put the same $100,000 into a private apartment REIT or a five-year real estate syndication. Your statement barely moves. The marketing materials talk about a 7 percent preferred return, a 5 percent cash distribution, institutional-quality buildings and “low historical volatility.” It feels calmer. Nothing is flashing red on a screen.

Continue reading →
Living in Bali as a Canadian with signs for Canggu, Sanur, Ubud, Denpasar and Uluwatu highlighting schools, healthcare and airport access

Living in Bali as a Canadian: Where on the Island Should You Actually Build Your Life?

Bali is not physically large. On a normal map, Canggu, Sanur, Ubud, Jimbaran and Denpasar look almost absurdly close together, a cluster of names you could imagine strolling between over a long weekend. Read the map that way and choosing a base becomes a lifestyle question: do I want the surf-and-café scene, the rice terraces, the calm beachfront, the cliffs?

That map is misleading. Twenty kilometres in Bali does not mean twenty minutes. A house that appears perfectly placed can put you on the wrong side of the island’s road network from the school, hospital or airport your life actually depends on. And the failure is rarely a steady, predictable slowness. It is variance: the same trip that takes a comfortable half hour on a good afternoon becomes an hour and a half on a bad one, and you find out on the day it matters.

So I want to start from a different question. Not “Where in Bali would I most like to live?” but “Which journey in my life cannot afford to fail?” The answer changes with your age, your work, whether you have children, and how your health is holding up. It determines which parts of Bali are options for you and which are traps that look like options.

Continue reading →
Investing in Japan for Canadian investors with Tokyo skyline, weak yen, Japanese equities and corporate reform

Investing in Japan: Is the Weak Yen Creating an Opportunity for Canadian Investors?

I am writing this from Japan. My family and I are here for a few weeks, moving between Osaka, Kyoto and Nara, and the weak yen is impossible to ignore. I was here more than a decade ago, and the difference this time shows up within the first day. Meals that would feel properly expensive back in Ontario come out costing a fraction of that once I convert. Local trains barely register as an expense. Even convenience store snacks, the onigiri and canned coffee that quietly add up on any trip, feel almost free.

I have already looked at Japan from the other direction in Living in Japan as a Canadian: what it costs to live here, how residency works, and where the country fits as an expat destination. This is a different question entirely.

Anyone who has glanced at CAD/JPY over the last couple of years already knows the yen has been weak. But standing in a train station doing currency math in my head, a different question kept nagging at me. If my Canadian dollar buys an unusual amount of Japan at the restaurant, the convenience store and the ticket machine, does it also buy an unusual amount of value on the Tokyo Stock Exchange?

The answer, after spending real time on this, is not necessarily.

Continue reading →
Living in South Korea as a Canadian with Seoul skyline, traditional Korean architecture and a Canadian passport

Living in South Korea as a Canadian: Is It Actually a Good Expat Destination?

South Korea is one of the most technologically advanced, safest, most convenient, and clinically capable countries a Canadian could reasonably consider living in. Its trains run on time to the minute. Its broadband is faster than almost anything in North America. Its hospitals are excellent. Its cities feel orderly, humane, and extraordinarily easy to move through. And Canadians can walk into the country for up to six months without a visa at all.

That last part sounds almost absurdly easy. It is easy. But the question this article actually asks is a different one: does a country being exceptionally good at running itself mean it is exceptionally good at absorbing you into it? Those are not the same question, and the gap between them is where most expat regret lives.

Continue reading →
HOOPP pension deep dive showing defined benefit income, early retirement, bridge benefits, CPP, OAS and retirement investments

HOOPP Pension Deep Dive: What Is It Actually Worth, and How Should It Change Your Financial Plan?

Picture two households, both 55, both about to retire.

Household one has $1 million sitting in RRSPs and non-registered accounts. No pension. They look at their net worth statement and feel good about it. A million dollars is a million dollars.

Household two has $600,000 in investments and a HOOPP pension that will pay roughly $45,000 a year for the rest of their life, starting now. Their net worth statement, the conventional kind, says they have $600,000. Six hundred thousand dollars looks a lot smaller than a million.

So which household is actually in the stronger position?

Continue reading →
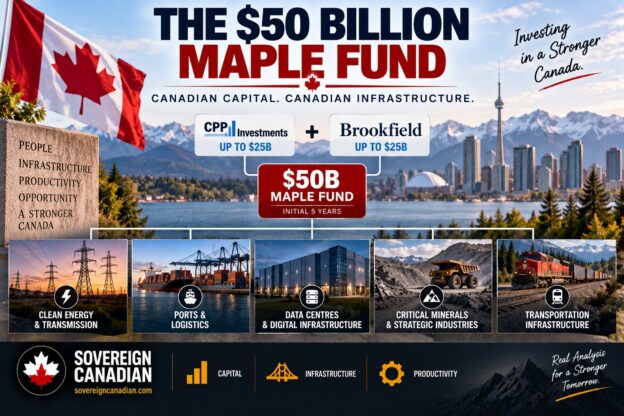
Canada's $50 billion Maple Fund showing CPP Investments and Brookfield funding Canadian infrastructure and strategic industries

Brookfield’s $50 Billion Maple Fund: Can Individual Canadians Invest Alongside It?

One of the announcements that caught my attention coming out of this week’s Canada Investment Summit was the creation of something called the Maple Fund.

The headline number is enormous: $50 billion.

CPP Investments and Brookfield Asset Management have created a new framework to pursue some of the largest infrastructure and strategic investments in Canada. Each organization could put as much as $25 billion into it over the next five years.

Continue reading →